
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.
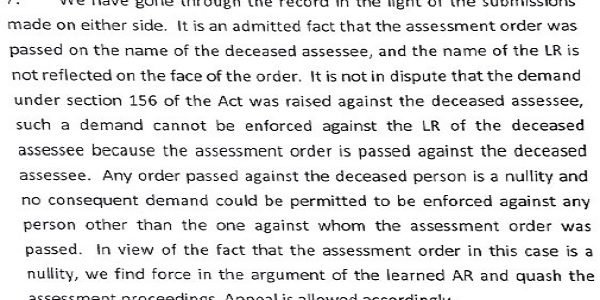
ITAT Hyderabad Quashes Reassessment Made in the Name of Deceased Assessee
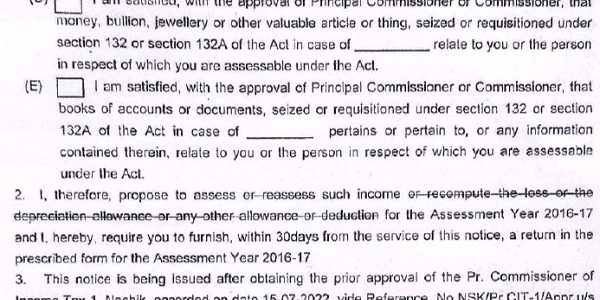
Pune ITAT: AY 2016-17 Reassessment Quashed; PCIT Sanction Invalid Beyond 3 Years
Pune ITAT: 25% Addition Limited to ₹16.54 Crore Unproved Purchases, Not to Entire Purchases
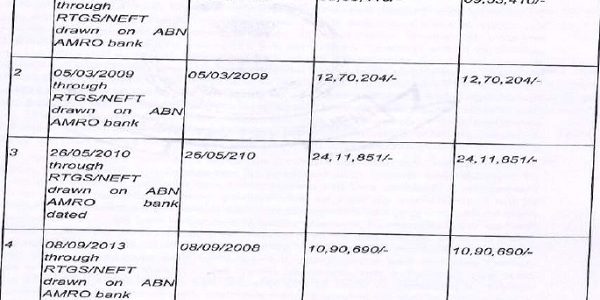
Pune ITAT: Reopening Beyond 3 Years Quashed; ₹12.56 Lakh Escapement Below ₹50 Lakh Threshold

Mumbai ITAT: 19 Search Appeals Restored for 153A, 153D Approval & Limitation Review

Mumbai ITAT: LP Steam Not Nil-Cost By-Product; ₹32.20 Crore Section 80-IA Deduction Allowed

Loose Sheets Without Corroboration Cannot Sustain Capitation Fee Addition: Karnataka HC

Bangalore ITAT: TDR Sale Taxable as Capital Gains After Deducting Surrendered Land Value

Karnataka HC: No TDS on Compensation for Compulsory Land Acquisition
Karnataka HC: Capitation Fee Additions Deleted Following Earlier Judgment
Karnataka HC: Section 41(1) Addition Deleted for Lack of Evidence of Liability Cessation
Karnataka HC Upholds Section 12A Registration; No Automatic Sections 11–12 Exemption
Karnataka HC: CAT Can Reconsider Pay Parity Claim as Fresh Decision Not Barred by Res Judicata
Karnataka HC: Section 271(1)(c) Penalty Reconsideration Ordered After Assessment Revival
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

