
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

Section 10(10B) Exemption Allowed on BSNL VRS Compensation: ITAT Ahmedabad
On-Money Addition Restricted to Co-owner’s Investment Share: ITAT Ahmedabad

Section 2(47)(v) Capital Gains Deleted as Section 53A Conditions Not Satisfied: ITAT Bangalore

Section 40(a)(i) Disallowance Deleted Applying DTAA Non-Discrimination Clause: ITAT Delhi

SC Denies Section 80-O Deduction for Marine Product Procurement Services

Section 80P(2)(d) Deduction Allowed on Cooperative Bank Interest: ITAT Pune

Section 80P(2)(a)(i) Deduction Allowed as Assessee Not a Cooperative Bank: ITAT Panaji

Section 148 Reassessment Notice Upheld for Failure to Fully Disclose Material Facts: Gujarat HC
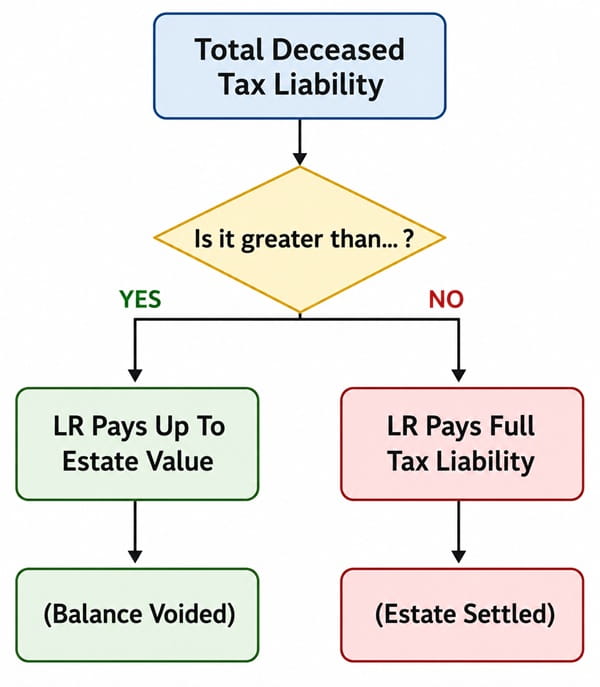
Section 159 Income Tax Rules on Legal Representative’s Liability After Taxpayer’s Death

Section 54B: Time to Revisit Rural Agricultural Land Withdrawal Rules

Assessment Quashed as ACIT Lacked Pecuniary Jurisdiction: ITAT Kolkata

Section 148A(3) Appeal Dismissed as Not Appealable Under Section 253: ITAT Jaipur
Section 69 Addition Deleted for Lack of Cross-Examination & Corroborative Evidence: ITAT Delhi
Section 68 Addition Deleted as Advance Recovery Explained by Evidence: ITAT Delhi
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

