
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

Sold Shares & Equity Mutual Funds? Here’s Your Tax Liability

Section 80P(2)(d) Deduction Allowed on Interest from Co-operative Bank Deposits: ITAT Pune
Debt vs Equity Mutual Funds: Why Broker Capital Gain Reports Can Mislead ITR Filing
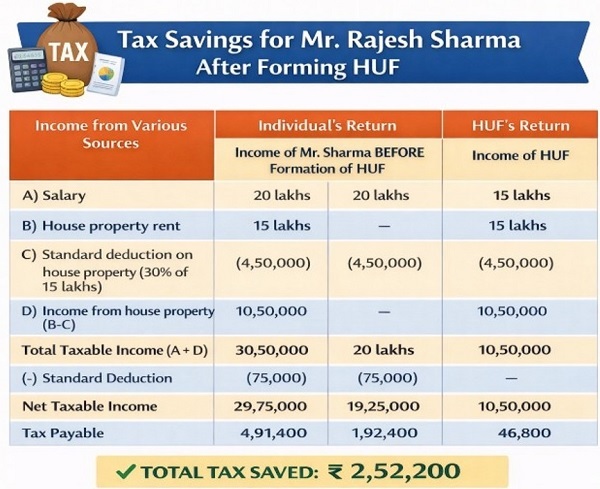
HUF Tax Benefits, Eligibility, Deductions & Separate Tax Status
Section 154 Rectification Rejected as Wrong Deductor Details Required Verification: ITAT Pune

Gratuity Trust Contribution and Export Commission Allowed After Subsequent Trust Approval: ITAT Mumbai

Section 153A Additions Rejected for Absence of Search Incriminating Material: Bombay HC

Section 148 Reassessment Appeal Dismissed as Proceedings Continued Against Deceased Assessee: Calcutta HC
False Income Tax Verification Sustains Conviction Under Section 277: Jharkhand HC

Section 68 Addition on Demonetisation Cash Deposits Deleted for Recorded Cash Sales: ITAT Jaipur
Section 37(1) Business Expenditure Allowed Following Consistent Earlier ITAT Rulings: ITAT Pune

Penalty Appeal Decided as Assessment Appeal Violates Section 250(6): ITAT Indore

Cash Deposits for Digital Money Transfers Not Unexplained Income: ITAT Kolkata
Interest on Surplus Bank Deposits Eligible for Section 80P(2)(a)(i) Deduction: ITAT Kolkata
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

