
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

Delhi ITAT: Section 44AD Cannot Be Forced Without Assessee’s Option

Delhi ITAT Quashes Reassessment for No Section 143(2) Notice, Section 292BB Inapplicable

ITAT Chennai: SBI Not Assessee in Default – HC Interim Order Barred TDS on Foreign LFC

ITAT Raipur Quashes Reassessment Where PCIT Approved Notice Beyond Three Years

Delhi HC: Reassessment Fails – PCIT Lacked Authority to Grant Approval Beyond Three Years
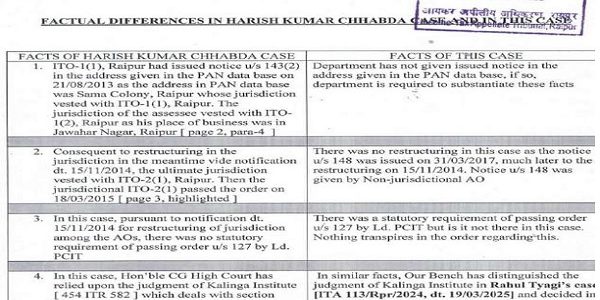
ITAT Raipur: Reassessment Set Aside – Jurisdiction Failed Due to Missing Section 127 Transfer Order

ITAT Surat: Property Addition Set Aside – CIT(A)’s Order Based on Incorrect Facts

ITAT Mumbai: Section 56(2)(x) Addition Deleted – Stamp Value on Earlier Allotment Date Applies
No Capital Gain Taxation on Untransferred JDA Land: ITAT Pune
Delhi ITAT Deletes ₹7.15 Crore Protective Addition After Substantive Assessment Quashed
ITAT Mumbai Restores R&D Deduction Claim Under Section 35(1)(i) After DSIR Rejection

ITAT Pune Rejects Section 80P Claim for Failure to Prove Co-operative Society Status
Kerala HC: Bank Cannot Rely on Expired Income Tax Prohibitory Order to Freeze Account

Kerala HC: Appeal Restored After 10 Years – Form 35 E-Filing Transition Caused Confusion
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

