
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

Madras HC Allows Section 37(1) Deduction for Mandatory Site Restoration Cost

Gujarat HC: VAT Department Covered as Law Enforcement Agency Under Tax-Effect Exception

ITAT Ahmedabad Rejects 2376-Day Delay Condonation Citing Gross Assessee Negligence

P&H HC Quashes ₹19.10 Crore Income Tax Refund Adjustment Against Stayed Demand

Gujarat HC: Section 154 Rectification Application to Be Decided Within 3 Months

ITAT Delhi Quashes Section 153C Assessments for Invalid Satisfaction & Limitation

Delhi HC: Section 147A Amendment Confirms Concurrent FAO- JAO Jurisdiction
ITAT Delhi: Leftover Material Sales Supported by GST Records Cannot Attract Section 69A

Mere Tax Payment Delay Insufficient for Section 276C(2) Prosecution: Madras HC
Ahmedabad ITAT: Section 54F Covers Post-Purchase Reconstruction; Cost Includes Renovation

ITAT Deletes ₹4.34 Lakh Addition Where Foreign Currency Belonged to Sister-in-Law

Jaipur ITAT: Section 153(3) Not Applicable to U/s 12AB/80G; CIT(E) Must Allow Records
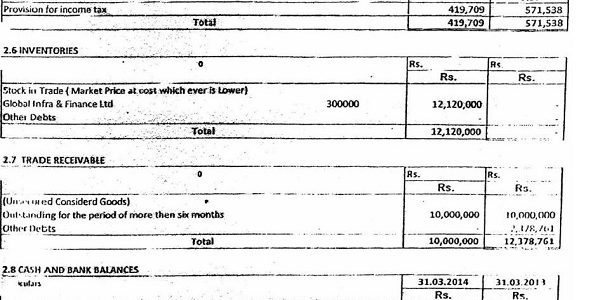
Kolkata ITAT Upholds ₹2.79 Crore Section 68 Addition on Penny Stocks; Credit Need Not Be Cash

Section 48 bars Double Deduction of Interest on Borrowed Capital for House Property
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

