
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.
Section 13 Cannot Be Invoked to Deny Section 12A Registration: Gujarat HC

Incidental Rental Income Used for Charitable Objects Does Not Deny Sections 11 & 12 Exemption: ITAT Chandigarh

Mumbai ITAT: Reassessment Beyond Three Years Quashed; Escaped Income Below ₹50 Lakh

Co-op Housing Society Entitled to Section 80P(2)(d) Deduction on Bank Interest: ITAT Mumbai

Delhi ITAT: Section 153C Assessment Quashed; Assumed Higher Assured Returns-Based On-Money Addition Deleted

Family Disputes & Mental Distress Are Valid Grounds for Delay Condonation: ITAT Delhi

No Coercive Income Tax Recovery After 7-Year Delay in Appeal Disposal: Andhra Pradesh HC
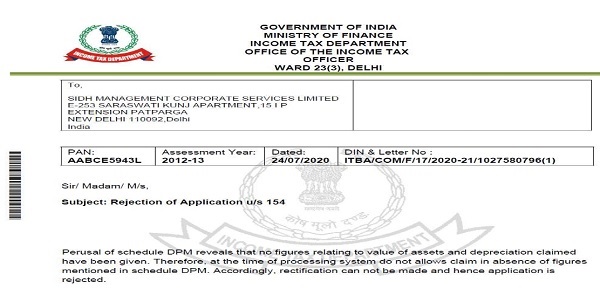
Delhi ITAT: Genuine Depreciation Claim Cannot Be Denied for Schedule DPM Omission
Delhi ITAT: Section 12AB Registration Cannot Be Cancelled for Engaging Builder for Staff Housing Project
Delhi ITAT: Enhanced Security Expenses During Directors’ Dispute Are Allowable Business Expenditure
Alleged Commission Addition Cannot Rest on Loose Third-Party Papers & WhatsApp Chats: ITAT Delhi
Uncorroborated WhatsApp Chats Alone Cannot Sustain Section 69A Addition: Delhi ITAT

Section 68 Addition Deleted for Loan Funded from Bank Borrowing: ITAT Rajkot
Donations from Identified Donors Cannot Be Taxed as Anonymous Donations: Delhi ITAT
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

