
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

Section 153C Assessments for 7 AYs Quashed as Deemed Date Fell After 01.04.2021: Bangalore ITAT

37% Surcharge Deleted on AOP Income Below ₹50 Lakh: Mumbai ITAT
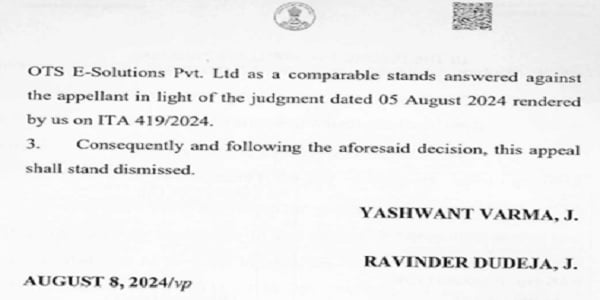
AMP Spend Not International Transaction Without AE Arrangement: Delhi ITAT

Section 56(2)(viib) Inapplicable to Holding-Subsidiary Transaction: ITAT Delhi

Property Registration Alone Cannot Trigger Section 56(2)(x): ITAT Mumbai
Form 3CLA Uploaded Before ITR Due Date Is Valid Compliance for Section 35(2AB: Bombay HC

SaaS Receipts Not FIS Without ‘Make Available’ of Technology: ITAT Delhi

Final Assessment Quashed as DRP Objection Intimation Failure Was Bona Fide: P&H HC

₹12.50 Lakh FDR Wrongly Reported as ₹12.50 Crore: Reassessment Quashed by Patna HC

Bright Line Test Cannot Determine AMP International Transaction: Delhi High Court

8% Profit Estimation Excessive for Wholesale-Retail Medicine Business: ITAT Amritsar

SC Upholds No Separate Section 68 Addition in Best Judgment Assessment
Separate Section 68 Addition Not Permissible in Best Judgment Assessment: Allahabad HC

₹22.41 Lakh Cash Salary Disallowance Remanded for Genuineness Verification: ITAT Surat
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

