
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

₹165-Crore Section 80P Deduction Cannot Be Denied on Unidentified Members: ITAT Jodhpur)

5% Commission Formula Insufficient: Political Donation Allowed u/s 80GGC, Section 69A Addition Deleted
ITAT Remands Reassessment, Donation & Cash Deposit Issues for Speaking Order U/s 250(6)

Reassessment Without Live Nexus or Reason to Believe Quashed: Bombay HC

Excess TDS Refund Cannot Be Denied in Section 148 Return: ITAT Delhi
ITAT Deletes Section 69A Addition, Allows Section 10(38) LTCG Despite Penny-Stock Suspicion
₹40 Lakh Bank Loan Repaid Same Year: Section 68 Addition Deleted
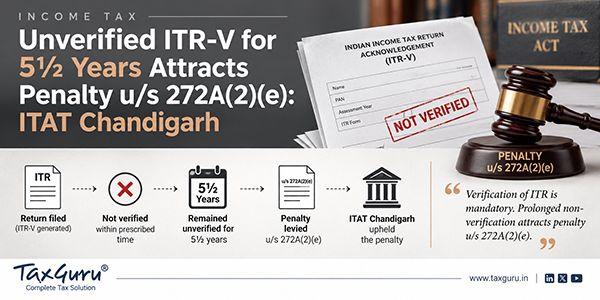
Unverified ITR-V for 5½ Years Attracts Penalty u/s 272A(2)(e): ITAT Chandigarh

Kirana Cash Deposits During Demonetisation Not Unexplained u/ss 68 & 69A: ITAT Chandigarh

Seven Clear Days Mandatory-AO’s Five-Day Notice Invalid u/s 148A(b): ITAT Raipur

Revenue’s 15-Ground Appeal Fails as ITAT Upholds Consistency on Tax and Transfer Pricing Issues

FADS 2026: A Practical Guide to Disclosing Unreported Foreign Assets and Income
Withdrawn Donation Claim Cannot Justify 200% Penalty u/s 270A: ITAT Ahmedabad
Reopening on “Cash Loan”, Addition for “Bogus LTCG” – Ahmedabad ITAT Quashes Reassessment U/s 147
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

