
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.
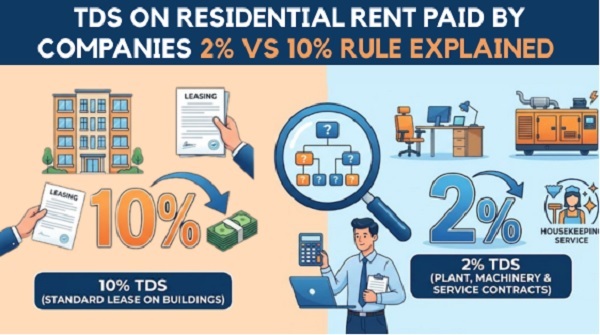
TDS on Residential Rent paid by companies : 2% vs 10% rule

ITAT Upholds Section 154 Rectification as Payments from Accumulated Funds to Registered Trusts Escaped Assessment
Mumbai ITAT Rejects Excess PE Attribution: Revenue Sharing with UK Office Upheld in Cross-Border M&A Deals
Mumbai ITAT Reiterates: Surplus from Members’ Contributions Not Taxable Under Doctrine of Mutuality
Suspicion Cannot Replace Evidence When Property Investment Is Fully Explained: ITAT Mumbai
Mumbai ITAT Deletes Entire Bogus Purchase Addition: General Hawala Statements Cannot Override Site-Level Evidence

No addition regarding commission income earned by PSPL as it was not an undisclosed income

Section 127 & 263 Orders Quashed as Assessee Was Denied Fair Hearing During COVID
Kerala HC Condones 676-Day ITAT Appeal Delay Due to Auditor Lapse
ITAT Allows Indexation on Construction Cost as Sale Deed Already Contained Building Details

ITAT Deletes Bogus Purchase Addition as Cross-Examination Was Not Granted
Employee Cannot Be Punished for Employer’s TDS Default: Bangalore ITAT
Reassessment Proceedings Held Void as Jurisdiction Was Assumed Beyond Limitation Period

ITAT Allows Final Section 35D Deduction and ESOP Recharge Expense
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

