
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

Section 263 Revision Invalid if CIT Failed to Show Assessment Was Erroneous
International Business- Income Tax Sections to be remembered
Compulsory Income Tax Scrutiny Guidelines FY 2026-27: CS01–CS06 Explained
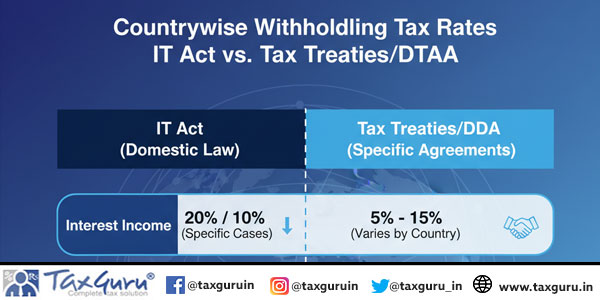
Countrywise Withholding Tax Rates: IT Act vs. Tax Treaties/DTAA

Countrywise Withholding Tax Rates / Chart as per DTAA
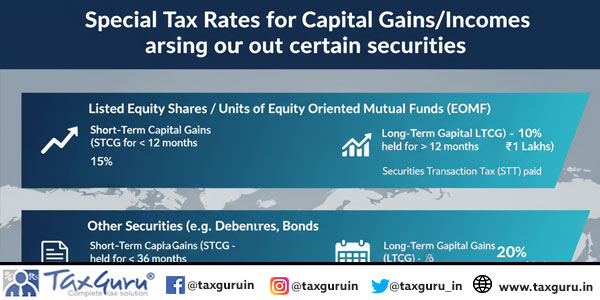
Special Tax Rates for Capital Gains/Incomes arising out of certain securities

Residence in India for the purpose of Income-tax Act, 1961

ITAT Excludes Incomparable Companies as Functional Differences & Turnover Distorted TP Analysis
Computer Software Eligible for 60% Depreciation: ITAT Chennai
Compounding of offence under the Income-tax Act, 1961
ITAT Allows 60% Depreciation on Software Forming Integrated Part of Computer

ITAT Allows Bad Debt Deduction as Unrecoverable Subsidy Already Been Recognised as Income

ITAT Deletes Section 56(2)(viib) Addition as AO Changed Valuation Method Contrary to Rule 11UA
Important definition under Income-tax Act, 1961
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

