
Courts: ITAT Delhi
Find latest ITAT Delhi judgments, orders and case laws on income tax covering assessments, transfer pricing, international taxation, deductions, TDS, reassessment and penalties.
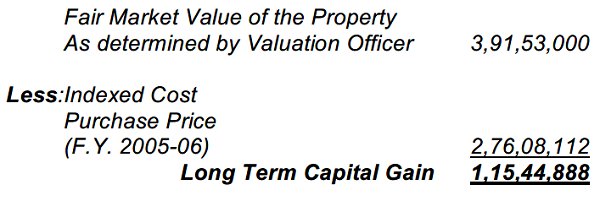
Section 50C not applicable on Right to Purchase a Building

Fees for use of Software is revenue in nature and allowable U/s. 37
Non compete fee is not an eligible intangible asset for depreciation U/s. 32
S.68 Addition cannot be made merely because Investor Company was from Kolkata
Revision u/s 263 for denying Deduction u/s 80-IA is Invalid if both conditions not satisfied
Sec. 292 cannot cure mistake of sending notice in the Name of Deceased Assessee
Late Fee U/s. 234E for TDS Default Committed prior to 01/06/15 not leviable: ITAT
AO cannot add notional interest for ICD made at Bank FD Rate
Protective Assessment can’t be made against Shareholder If Overseas Companies already been assessed on substantive basis
Applicability of Section 50C on Transfer of property through transfer of shares in company
S. 32(1)(ii) Depreciation on non-compete fee as intangible assets: HC sends matter back to AO
Mere dismissal of SLP without giving any reasons, cannot be equated with exposition of law
Service tax does not form part of gross receipts for computation U/s. 44BB
Payment of Upfront Fees by DIAL held to be Revenue Expenditure
ITAT Delhi judgments and orders constitute a substantial body of appellate case law under the Income-tax Act. This page compiles ITAT Delhi decisions concerning assessments, additions, deductions, exemptions, business income, capital gains, transfer pricing, international taxation, TDS, reassessment, unexplained income, penalties, limitation and procedural disputes. Companies, individuals, Chartered Accountants, advocates and tax professionals can use this collection to research Tribunal precedents relevant to income-tax matters. TaxGuru brings together recent and significant earlier ITAT Delhi judgments and orders, providing a convenient resource for following developments in direct tax jurisprudence and researching recurring issues arising in assessments and appeals.

