
Courts: ITAT Delhi
Find latest ITAT Delhi judgments, orders and case laws on income tax covering assessments, transfer pricing, international taxation, deductions, TDS, reassessment and penalties.

Mere change of head of income not amounts to furnishing of inaccurate particulars of income
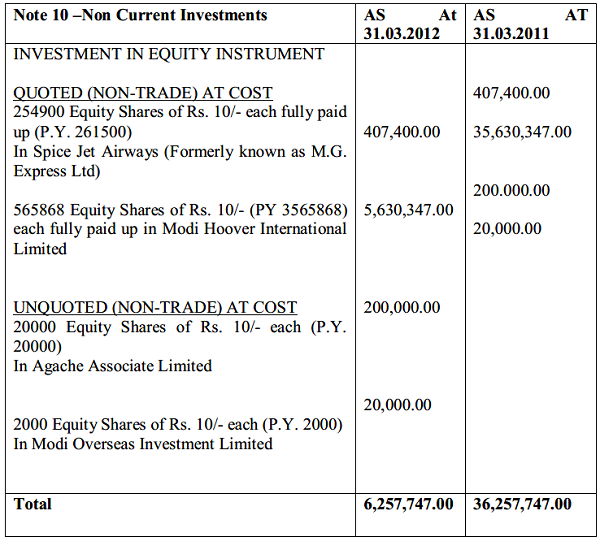
No Disallowance U/s. 14A on strategic investments out of Commercial expediency
Builder to pay tax based on completion stage if significant risk and reward are transferred to buyer
In Absence of service of notice U/s. 143(2) assessment order passed by AO is not sustainable
Addition U/s. 68 cannot be made for mere no reply of notice U/s. 133(6) by creditors
No addition based on Seized Document if same do not contain Name or Signature of Assessee
Merely because tax has been deducted at source on unreported income, it cannot be said that there was no escapement of income
Disputed Commission cannot be taxed unless received
No Deemed Dividend U/s. 2(22)(e) If Assessee is not a Shareholder in Payer Company

Section 54/ 54F Flat booked with builder can be considered as construction of flat
No addition in case of unabated assessment which had attained finality on search date if no incriminating material found during search
Sec 54F not prescribe any condition as to date of commencement of construction of new house property
In absence of search Penalty u/s 271AAA cannot be levied
Late fees U/s. 234E cannot be levied for the period prior to 01/06/2015
ITAT Delhi judgments and orders constitute a substantial body of appellate case law under the Income-tax Act. This page compiles ITAT Delhi decisions concerning assessments, additions, deductions, exemptions, business income, capital gains, transfer pricing, international taxation, TDS, reassessment, unexplained income, penalties, limitation and procedural disputes. Companies, individuals, Chartered Accountants, advocates and tax professionals can use this collection to research Tribunal precedents relevant to income-tax matters. TaxGuru brings together recent and significant earlier ITAT Delhi judgments and orders, providing a convenient resource for following developments in direct tax jurisprudence and researching recurring issues arising in assessments and appeals.

