
Courts: ITAT Delhi
Find latest ITAT Delhi judgments, orders and case laws on income tax covering assessments, transfer pricing, international taxation, deductions, TDS, reassessment and penalties.

Expense to get finance for normal business operations was revenue expense
Satellite transmission services provided by USA based company in India cannot be taxed as Royalty
Addition for undisclosed stock not justified for mere difference in closing stock valuation
Addition pursuant to search operation on matter dealt during original assessment
Construction expense cannot be disallowed merely based on Inspector Report
Addition justified for Unverified corpus donation
Cash Sale of Car cannot be doubted without inquiry| Addition not justified
Mere Magnitude of disallowance cannot be the basis for restricting disallowance
Loss claimed on forward contracts is allowable
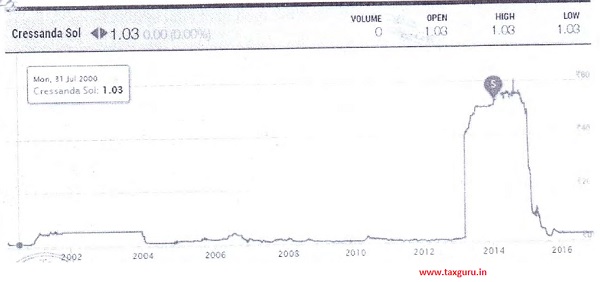
ITAT upheld addition for accommodation entry receipts as LTCG

Addition for cash deposit in bank justified if Assessee fails to explain source of deposit
Issuance & service of notice u/s 143(2) at wrong address within knowledge of AO was invalid
Interest on FD taxable on accrual basis if Assessee follows mercantile system of Accounting
Exemption u/s 11 allowable on donation by a charitable trust to other for utilization towards charitable objects
ITAT Delhi judgments and orders constitute a substantial body of appellate case law under the Income-tax Act. This page compiles ITAT Delhi decisions concerning assessments, additions, deductions, exemptions, business income, capital gains, transfer pricing, international taxation, TDS, reassessment, unexplained income, penalties, limitation and procedural disputes. Companies, individuals, Chartered Accountants, advocates and tax professionals can use this collection to research Tribunal precedents relevant to income-tax matters. TaxGuru brings together recent and significant earlier ITAT Delhi judgments and orders, providing a convenient resource for following developments in direct tax jurisprudence and researching recurring issues arising in assessments and appeals.

