
#Section 148
Log in to FollowLatest Section 148 updates, provisions, case laws, compliance requirements, tax implications and expert analysis under Income-tax law on TaxGuru.
Income Tax
Income Tax
Delhi ITAT Quashes Reassessment for ‘Reason to Suspect’ – Cash Deposits Alone Can’t Justify Reopening
Income Tax
Income Tax
ITAT Quashes Reassessment as Confidential Reopening Materials Were Not Supplied
Income Tax
Income Tax
ITAT Reduces Section 271(1)(b) Penalty by treating Multiple Notice Defaults as One
Income Tax
Income Tax
Mere Acceptance of Political Donation Addition Doesn’t Justify Penalty
Income Tax
Income Tax
Loans via Banking Channels not Bogus Merely on ‘Shell Company’ Allegation
Income Tax
Income Tax
Reassessment Quashed for Ignoring Reply Filed Under Section 148A(b): ITAT Slams ‘Borrowed Satisfaction’
Income Tax
Income Tax
Goat Trader Fails to Explain ₹7.10 Crore Bank Deposits: ITAT Upholds Section 69A Addition Despite U/s 44AD Claim
Income Tax
Income Tax
No 270A Penalty When Income Declared in 148 Return Is Accepted: ITAT Deletes ₹4.91 Lakh Penalty
Income Tax
Income Tax
Premature Surrender of Pension Policy Not Taxable as Income from Other Sources: ITAT Ahmedabad
Income Tax
Income Tax
Cancelled Property Deal Cannot Trigger Section 69 Addition: ITAT Deletes ₹4.96 Lakh Unexplained Investment Addition
Income Tax
Income Tax
U/s 153C Assessments Quashed – Mere Seized Material Not Enough Unless AO Shows Its Bearing on Total Income
Income Tax
Income Tax
Hyderabad ITAT Upholds Reopening Beyond 3 Years Though Final Addition Was Below ₹50 Lakhs – Jurisdiction Based on Reopening Information
Income Tax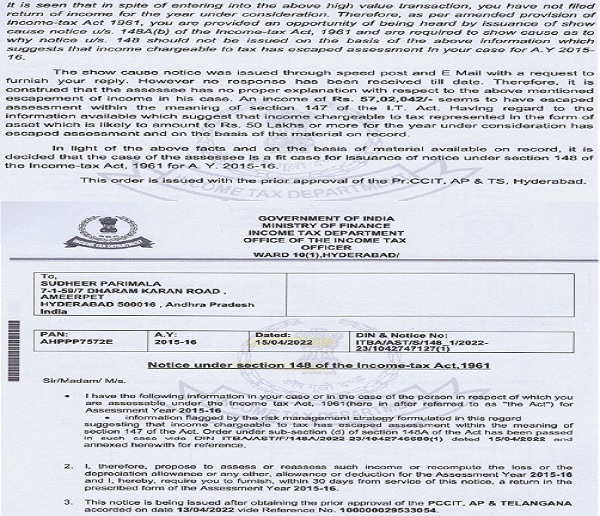
Income Tax
Hyderabad ITAT Quashes AY 2015-16 Reopening – Notice u/s 148 Issued After 6 Years Held Time-Barred Despite ₹50 Lakh Escape Claim
Income Tax
Income Tax
Chennai ITAT Quashes Reassessment – Notice u/s 148 Beyond 3 Years Needs PCCIT Approval, Not PCIT Approval
Explore the latest Section 148 updates on TaxGuru, including relevant Income-tax Act provisions, rules, notifications, circulars, judicial decisions and compliance guidance. The coverage highlights important tax positions, procedural requirements, assessments, deductions, penalties and litigation developments to help taxpayers and professionals understand the practical implications of changes in income-tax law.

