
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

ITAT Slams Enhancement in Section 264 Proceedings – Past Salary Savings During Demonetisation Accepted

Educational Trust Registration Renewal Cannot Be Denied Over Earlier Allegations
ITAT Slams Ad-Hoc Profit Estimation & Deletes Family Loan Addition u/s 68
Navigating the New Era: Comprehensive Guide to TDS/TCS Restructuring for FY 2026-27 under Income Tax Act, 2025
ITAT Bangalore Quashes ₹7,778 Cr 143(1) Adjustment After 143(2) Notice

Important Income Tax Return Due Dates for Financial Year 2025-2026
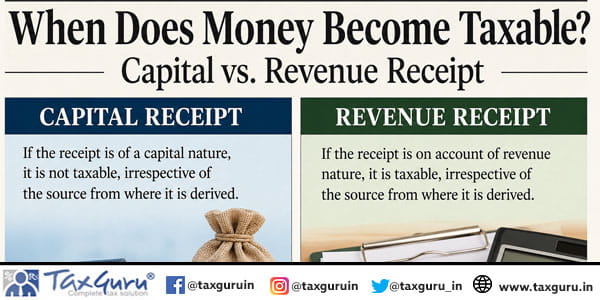
When Does Money Become Taxable? Capital vs. Revenue Receipt
TDS & Advance Tax: Meaning, Rules, Compliance & Penalties – Income Tax Act, 1961

Key ITR Filing Mistakes to Avoid for AY 2026-27

ITAT Deletes Section 40A(3) Disallowance as No Single Cash Payment Exceeded Rs. 10,000
Notional Interest Addition Deleted Because Only Real Income Can Be Taxed: ITAT Delhi

Calcutta HC Orders Refund as Section 245 Adjustment Exceeded 20% of Disputed Demand
CIT(A) cannot enhance income on issues not examined by AO: ITAT Mumbai

ITAT Indore Remands TDS Credit Dispute for Verification of Form 16A and Form 26AS
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

