
ACIT Vs Raj Diamonds (ITAT Bangalore)
Bogus Purchase Addition Deleted – Suspicion from STR Report Insufficient When Purchases Supported by Evidence
The assessee, a partnership firm engaged in the business of gold and diamond jewellery, filed its return for AY 2018-19 declaring income of ₹92.24 lakh. Based on a Suspicious Transaction Report (STR) alleging that certain suppliers were accommodation entry providers, the AO reopened the assessment and treated purchases of ₹2.49 crore from two entities as bogus, adding the entire amount to income u/s 147.
Before the CIT(A), the assessee produced documentary evidence such as purchase invoices, ledger accounts, bank statements, confirmations, GST returns and stock records. The CIT(A) accepted that sales were not doubted and therefore restricted the addition to 7.37% of purchases (₹18.37 lakh) based on the weighted average gross profit of the previous three years.
The Tribunal observed that the reopening itself was based merely on suspicion arising from the STR report and the AO had failed to establish with cogent evidence that the purchases were bogus. The assessee had produced substantial evidence demonstrating the genuineness of transactions, including payments through banking channels, invoices, confirmations and GST records. The Tribunal emphasized that suspicion, however strong, cannot replace proof, and the Revenue had not found any defect in the books of account or supporting documents.
The Tribunal further held that once the genuineness of purchases was supported by evidence and the Revenue failed to rebut the same, even the estimated addition sustained by the CIT(A) was not justified. Accordingly, the Tribunal deleted the entire addition of ₹2.49 crore and allowed the assessee’s cross-objection while dismissing the Revenue’s appeal.
FULL TEXT OF THE ORDER OF ITAT BANGALORE
This appeal at the instance of the revenue is directed against the order of ld. Commissioner of Income Tax (Appeals)-2, Panaji dated 17/03/2025 vide DIN: ITBA/APL/M/250/2024-25/ 1074591942(1) passed u/s. 250 of the Income Tax Act, 1961 (in short “the Act”) for the AY 2018-19. The assessee has also filed a cross objection in CO No. 20/BANG/2025 against the said appeal of the revenue in ITA No.1361/BANG/2025.
2. The revenue has raised the following Grounds of appeal:-
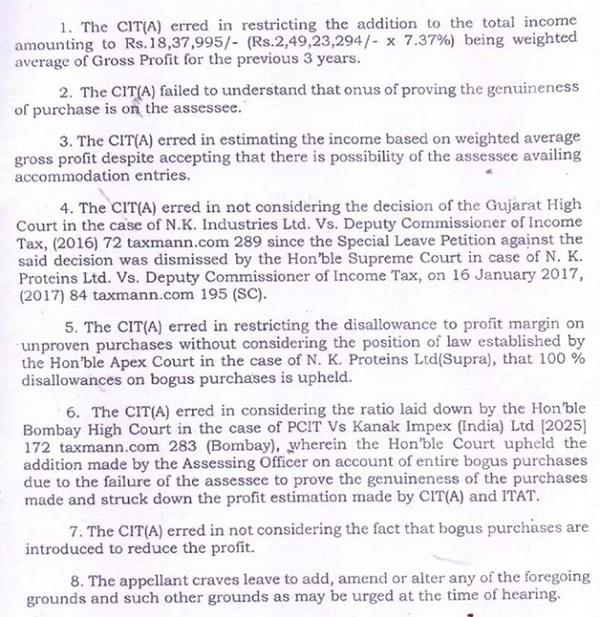
3. The assessee firm has raised the following Grounds in the Cross objection:-





