
Courts: ITAT Mumbai
Find latest ITAT Mumbai judgments, orders and case laws on income tax covering assessments, transfer pricing, international taxation, capital gains, TDS, reassessment and penalties.

Section 272A(1)(d) penalty not leviable if reasonable cause for non-compliance shown

AO cannot change his opinion in immediate next assessment year without there being any change in facts

Penalty not sustainable when addition itself is on a weak footing

Reopening of assessment with incorrect reasons is bad in law

Expense on Pen drives, laptop adapters, batteries & hard disk are revenue expenditure

Section 40A(2)(b) not applies to loan given at lower interest rate for business purpose to related parties

Invalid IDS, 2016 Declaration not a Reasonable Cause for Non-filing of ITR- ITAT upheld section 271F penalty

Further Profit Attribution not required if Indian AE is remunerated at ALP

Section 54F- Source of funds is irrelevant & Possession date is Purchase date

No section 14A disallowance if Assessee’s own funds exceeded investments

Constitute special bench to resolve dispute of taxability of share capital/premium u/s 68: ITAT
No capital gains tax on sale of TDRs in absence of cost of acquisition
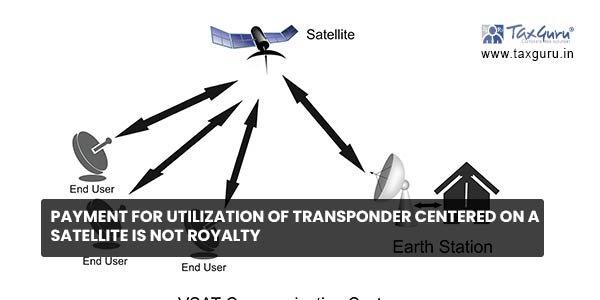
Payment for Utilization of Transponder Centered on A Satellite is not Royalty

Income from Unsold Flats shall be treated as Business Income
ITAT Mumbai judgments and orders represent an extensive body of income-tax appellate jurisprudence covering individuals, businesses, companies and other taxpayers. This TaxGuru page brings together decisions relating to assessments, additions, deductions, exemptions, business income, capital gains, transfer pricing, international taxation, TDS, reassessment, unexplained income, penalties and procedural disputes. Chartered Accountants, advocates, companies, taxpayers and tax professionals can use this collection to research ITAT Mumbai precedents and follow important developments under the Income-tax Act. The page includes recent as well as significant earlier Tribunal decisions published on TaxGuru, providing a comprehensive reference point for direct tax case-law research and appellate practice.

