
Courts: ITAT Mumbai
Find latest ITAT Mumbai judgments, orders and case laws on income tax covering assessments, transfer pricing, international taxation, capital gains, TDS, reassessment and penalties.

Donation to research Institute cannot be disallowed for subsequent withdrawal of registration
Addition cannot be made for mere credit in form 26AS without examination
Penalty cannot be imposed when income was estimated by applying a percentage
Section 68 additions cannot be made merely on doubts, conjectures or surmises
Registration cannot be cancelled for mere non-intimation of amendments in Trust Deed
Surplus from assignment of loan to third party was not cessation or extinguishment of liability u/s 41(1).
S. 56(2)(viib): AO cannot discard assessee’s method of Share Valuation
Bogus Share Capital: ITAT criticises casual approach of Department

All transactions in penny stocks cannot be regarded as bogus for SCAM in some penny stocks
Section 54EC Deduction cannot be disallowed for Investment not made with in prescribed time due to non-availability of REC Bonds
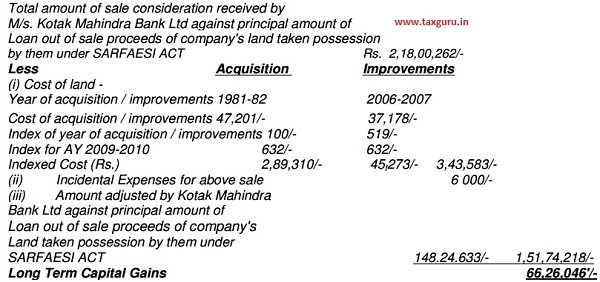
No deduction for payment for discharge of outstanding loan liability
Section 234E Fees for each purchased flat justified for delay in and for non-filing of Form 26QB
Depreciation allowable on non-compete fee (intangible asset)
Deduction U/s. 10AA cannot be scale down merely because assessee makes extraordinary profit
ITAT Mumbai judgments and orders represent an extensive body of income-tax appellate jurisprudence covering individuals, businesses, companies and other taxpayers. This TaxGuru page brings together decisions relating to assessments, additions, deductions, exemptions, business income, capital gains, transfer pricing, international taxation, TDS, reassessment, unexplained income, penalties and procedural disputes. Chartered Accountants, advocates, companies, taxpayers and tax professionals can use this collection to research ITAT Mumbai precedents and follow important developments under the Income-tax Act. The page includes recent as well as significant earlier Tribunal decisions published on TaxGuru, providing a comprehensive reference point for direct tax case-law research and appellate practice.

