
Courts: ITAT Delhi
Find latest ITAT Delhi judgments, orders and case laws on income tax covering assessments, transfer pricing, international taxation, deductions, TDS, reassessment and penalties.

ITAT Restores Matter To CIT(A) for proper examination & verification of documents

Income Tax: Section 2(22)(e) Act can be invoked in respect of shareholder

Invocation of jurisdiction under Section 147 is not alternative to Section 263

Income from technical handling services to other Airlines is exempt under Article 8 of India Netherlands DTAA

Assessment order on issue other than reasons recorded for reopening is unsustainable

No section 271(1)(b) Penalty Unless Conduct of Assessee Is Contumacious
Section 154 cannot be invoked for Applicability of section 14A to section 115JB provisions
Section 147/143(3) Assessment is null & void in absence of service of Section 148/143(2) notice
Loss on Sale of Asset allowable As Application of income to Charitable Trust
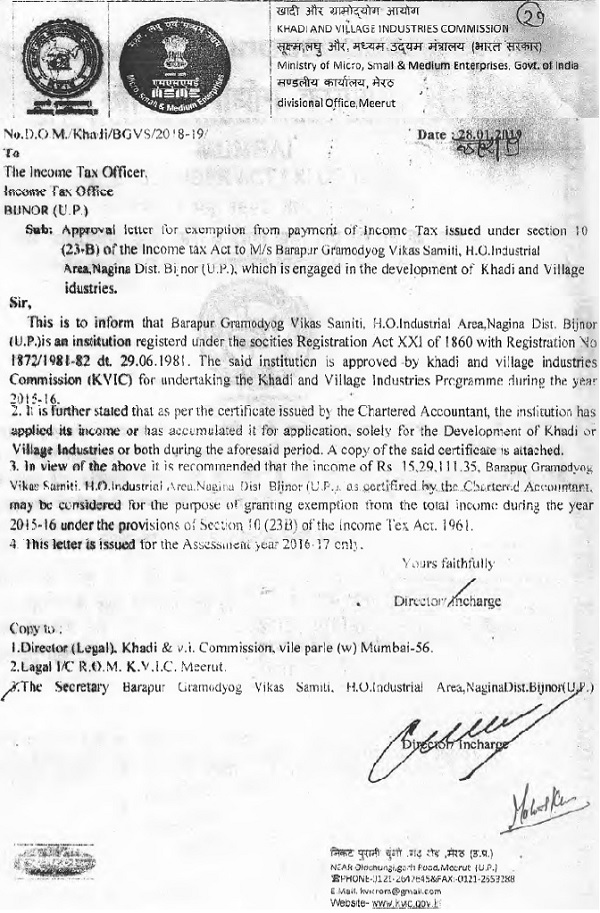
Section 10(23B) Exemption cannot be denied for Mere Technical Violation
Mere reproduction of conclusions of investigation report in own words by AO is borrowed satisfaction
Section 50C not applies to transfer of Leasehold Right in Land or Building or both
Section 271(1)(c) penalty quantification dependent upon additions to income
Expense cannot be denied under section 40(A)(2)(b) on surmises & conjectures
ITAT Delhi judgments and orders constitute a substantial body of appellate case law under the Income-tax Act. This page compiles ITAT Delhi decisions concerning assessments, additions, deductions, exemptions, business income, capital gains, transfer pricing, international taxation, TDS, reassessment, unexplained income, penalties, limitation and procedural disputes. Companies, individuals, Chartered Accountants, advocates and tax professionals can use this collection to research Tribunal precedents relevant to income-tax matters. TaxGuru brings together recent and significant earlier ITAT Delhi judgments and orders, providing a convenient resource for following developments in direct tax jurisprudence and researching recurring issues arising in assessments and appeals.

