
Courts: ITAT Mumbai
Find latest ITAT Mumbai judgments, orders and case laws on income tax covering assessments, transfer pricing, international taxation, capital gains, TDS, reassessment and penalties.

Purchases cannot be treated as bogus if supplier admits genuineness of transaction
AO cannot reopen the case without bringing something new on record
Loss from sale of unlisted shares to relative and set off of same against capital gains from sale of Property
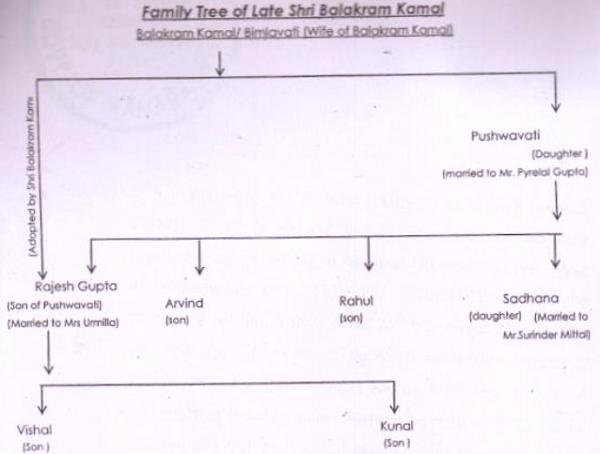
Existence of legal claims & disputes not necessary for validity of a family arrangement
Income from letting of warehouse is business income: ITAT Mumbai
Deduction U/s. 10AA on Interest on electricity deposit/assaying income/refining income and sale of residual dust
Addition of 12.5% out of bogus purchases meets the end of justice
Sec. 56(2)(viib) Assessee can adopt a method of his choice to determine FMV of shares transferred
Notional rental value cannot be computed for Unsold property which is held as stock in trade
Compensation for letting of terrace and hall constitutes the business activity
Cost inflation index in case of Property inherited from previous owner
Penalty u/s 221 cannot be levied for non-payment of self-assessment tax
TDS u/s 194C applicable in case contract requires semi-skilled staff
Technical provided by Machines would not fall U/s. 194J for TDS
ITAT Mumbai judgments and orders represent an extensive body of income-tax appellate jurisprudence covering individuals, businesses, companies and other taxpayers. This TaxGuru page brings together decisions relating to assessments, additions, deductions, exemptions, business income, capital gains, transfer pricing, international taxation, TDS, reassessment, unexplained income, penalties and procedural disputes. Chartered Accountants, advocates, companies, taxpayers and tax professionals can use this collection to research ITAT Mumbai precedents and follow important developments under the Income-tax Act. The page includes recent as well as significant earlier Tribunal decisions published on TaxGuru, providing a comprehensive reference point for direct tax case-law research and appellate practice.

