
Courts: ITAT Mumbai
Find latest ITAT Mumbai judgments, orders and case laws on income tax covering assessments, transfer pricing, international taxation, capital gains, TDS, reassessment and penalties.

AO not justified in not allowing standard deduction from annual letting value
Appeal filed with ITAT signed / verified by ex-director of company not valid
Interest paid by Indian Branch to Its foreign HO allowable
Income of Indian Plastics Institute from technical lectures, seminars and workshop is exempt
ITAT on addition for share application money received from bogus shareholders
Addition for ON MONEY received on Sale of Flat should be based on evidence found during search
TDS U/s. 195 on Grant of license for copyrighted software for internal business purposes
ITAT allows Proportionate Vacancy Allowance for period of Vacancy
Deduction U/s. 54 on Investment in 4 adjacent flats made into single residential house
TDS not deductible on reimbursement of management charges to overseas HO
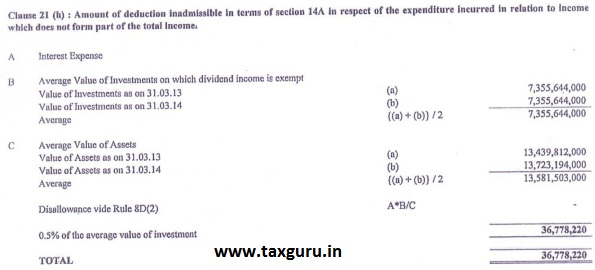
Section 14A could only be invoked in presence of exempt income
AO has to strike off & specify the limb to initiate penalty proceedings
Web Hosting Services to Indian Entities cannot be treated as FTS
Gain from High volume of trade in shares held for very short period is Business Gain
ITAT Mumbai judgments and orders represent an extensive body of income-tax appellate jurisprudence covering individuals, businesses, companies and other taxpayers. This TaxGuru page brings together decisions relating to assessments, additions, deductions, exemptions, business income, capital gains, transfer pricing, international taxation, TDS, reassessment, unexplained income, penalties and procedural disputes. Chartered Accountants, advocates, companies, taxpayers and tax professionals can use this collection to research ITAT Mumbai precedents and follow important developments under the Income-tax Act. The page includes recent as well as significant earlier Tribunal decisions published on TaxGuru, providing a comprehensive reference point for direct tax case-law research and appellate practice.

