
Courts: ITAT Jaipur
Find latest ITAT Jaipur judgments, orders and case laws on income tax covering assessments, additions, deductions, exemptions, capital gains, reassessment, TDS and penalties.

No default due to Non Deduction of TDS on Interest where Form 15G is Submitted
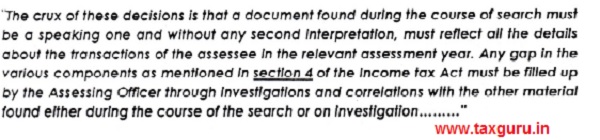
Additions for unexplained cash cannot be made solely based on section 132(4) statements

Addition for Bonus shares – Section 56(2)(vii)- ITAT explains Law
Differential Sales Tax paid for non-deposit of forms is allowable as deduction

In case of unaccounted sales only profit therefrom can be taxed

Income already disclosed under PMGKY, 2016 cannot be treated as Unexplained Income u/s 68
AO cannot treat Share Premium as Bogus without proper investigation
Section 271(1)(c) penalty cannot be levied on additions based on estimate
Amount taxed in the head of related entities, cannot be taxed in the hand of Appellant
Invocation of Section 263 to initiate Penalty proceeding not sustainable when addition itself deleted by ITAT

ITAT condones delay due to misplacement of Order by tax consultant
Interest cannot be disallowed for advance made for Business Purpose
No Rejection of Claim u/s 10(23C) if CIT(E) failed to establish that Assessee Existed for Purposes of Profit
Validity of Addition solely based on section 132(4) search statement
ITAT Jaipur judgments and orders cover numerous issues arising in income-tax assessments and appeals. This page brings together Tribunal decisions relating to additions, deductions, exemptions, capital gains, business income, unexplained income, reassessment, TDS, penalties, limitation and procedural matters. Taxpayers, businesses, Chartered Accountants, advocates and consultants can use this collection to research ITAT Jaipur case laws and locate precedents relevant to their disputes. TaxGuru provides access to recent and significant earlier ITAT Jaipur decisions published on the website, helping readers follow developments in direct tax jurisprudence.

