
Courts: ITAT Ahmedabad
Find latest ITAT Ahmedabad judgments, orders and case laws on income tax covering assessments, additions, deductions, exemptions, TDS, reassessment and penalties.

Ahmedabad ITAT: ₹18.31 Lakh Cash Deposit Addition Restored for Bank Verification
Ahmedabad ITAT: Ex-Parte Order Set Aside, ₹35.50 Lakh Deposit Issues Remanded
Ahmedabad ITAT: ₹13.68 Crore Demonetisation Deposits Not Taxable u/s 69A on Suspicion Alone
ITAT Ahmedabad Upholds Section 80GGC Disallowance as Political Donation Was Accommodation Entry
ITAT Ahmedabad Upholds Section 80GGC Disallowance on Bogus Political Donation
ITAT Ahmedabad Allows Section 80JJAA Deduction Despite Delayed Form 10DA Filing
ITAT Ahmedabad Deletes Section 270A Penalty on Political Donation Disallowance
Ahmedabad ITAT: Bogus Purchase Addition Limited to 12.5% Profit Where Sales Accepted
ITAT Ahmedabad Rejects 2376-Day Delay Condonation Citing Gross Assessee Negligence
Ahmedabad ITAT: Section 54F Covers Post-Purchase Reconstruction; Cost Includes Renovation
Section 263 Not Invocable for Non-Initiation of Section 270A Penalty: ITAT Ahmedabad
Reassessment on Borrowed Satisfaction Invalid; Section 153C Must Apply: ITAT Ahmedabad
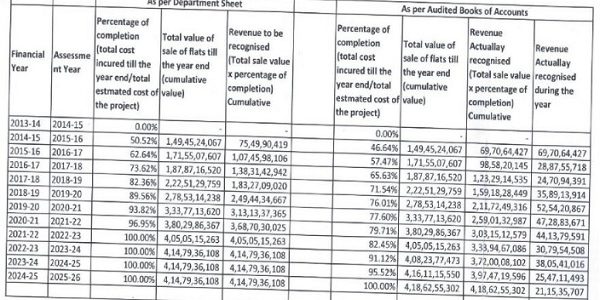
AO Cannot Recompute POCM Profits Without Rejecting Books: Ahmedabad ITAT
Time-Barred Reassessment Under Section 153 Invalid, Entire Addition Fails: ITAT Ahmedabad
ITAT Ahmedabad judgments and orders provide an extensive source of appellate case law under the Income-tax Act. This page compiles ITAT Ahmedabad decisions dealing with assessments, additions, deductions, exemptions, business income, capital gains, unexplained income, reassessment, TDS, transfer pricing, penalties and procedural issues. Taxpayers, businesses, Chartered Accountants, advocates and tax professionals can use this dedicated page to research Tribunal precedents relevant to income-tax controversies. TaxGuru brings together recent and important earlier ITAT Ahmedabad case laws, making it easier to follow developments in direct tax jurisprudence and identify decisions relevant to assessments and appeals.

