
#section 143(2)
Log in to FollowLatest section 143(2) updates, provisions, case laws, compliance requirements, tax implications and expert analysis under Income-tax law on TaxGuru.
Income Tax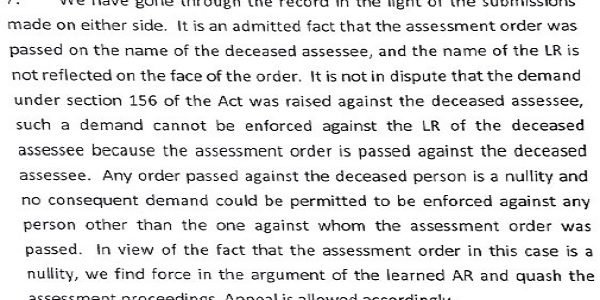
Income Tax
ITAT Hyderabad Quashes Reassessment Made in the Name of Deceased Assessee
Income Tax
Income Tax
Mumbai ITAT: LP Steam Not Nil-Cost By-Product; ₹32.20 Crore Section 80-IA Deduction Allowed
Income Tax
Income Tax
Loose Sheets Without Corroboration Cannot Sustain Capitation Fee Addition: Karnataka HC
Income Tax
Income Tax
Bangalore ITAT: TDR Sale Taxable as Capital Gains After Deducting Surrendered Land Value
Income Tax
Income Tax
ITAT Delhi Remands Expense Disallowance for Fresh Assessment After Business Transfer
Income Tax
Income Tax
ITAT Delhi Quashes Section 263 Revision for Inadequate Inquiry by AO
Income Tax
Income Tax
Section 263 Revision Cannot Apply Where AO Conducted Specific Enquiry & Accepted Reimbursement: Bombay HC
Income Tax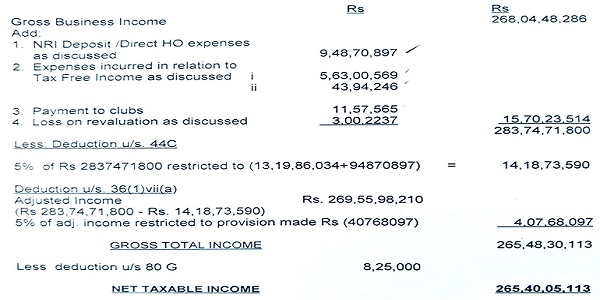
Income Tax
NRI Desk Expenses Attract Section 44C; 36(1)(viia) Deduction to Precede It: ITAT Mumbai
Income Tax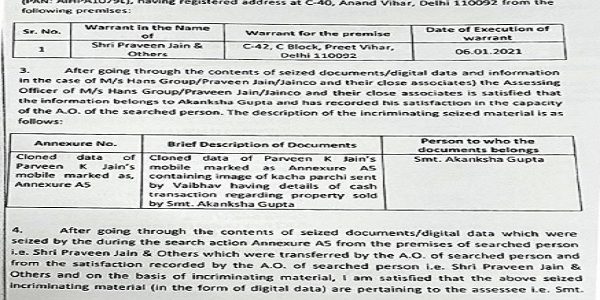
Income Tax
ITAT Delhi Holds Section 143(3) Assessment Invalid Where Section 153C Applied
Income Tax
Income Tax
Business Loss on NPA Sale; Section 263 Cannot Override Binding ITAT Precedent: Nagpur ITAT
Income Tax
Income Tax
Section 68 Addition Cannot Stand Without Reconciling Discrepancies: Cochin ITAT
Income Tax
Income Tax
Korea Salary Not Taxable Merely Due to Indian Payment or TDS: Bangalore ITAT
Income Tax
Income Tax
Gujarat HC Quashes Reopening Beyond 4 Years as 2(22)(e) Conditions Were Not Met
Income Tax
Income Tax
ITAT Mumbai Deletes Section 56(2)(x) Property Addition Within 10% Tolerance Limit
Explore the latest section 143(2) updates on TaxGuru, including relevant Income-tax Act provisions, rules, notifications, circulars, judicial decisions and compliance guidance. The coverage highlights important tax positions, procedural requirements, assessments, deductions, penalties and litigation developments to help taxpayers and professionals understand the practical implications of changes in income-tax law.

