
#Section 147
Log in to FollowLatest Section 147 updates, provisions, case laws, compliance requirements, tax implications and expert analysis under Income-tax law on TaxGuru.
Income Tax
Income Tax
U/s 153C Assessments Quashed – Mere Seized Material Not Enough Unless AO Shows Its Bearing on Total Income
Income Tax
Income Tax
Hyderabad ITAT Upholds Reopening Beyond 3 Years Though Final Addition Was Below ₹50 Lakhs – Jurisdiction Based on Reopening Information
Income Tax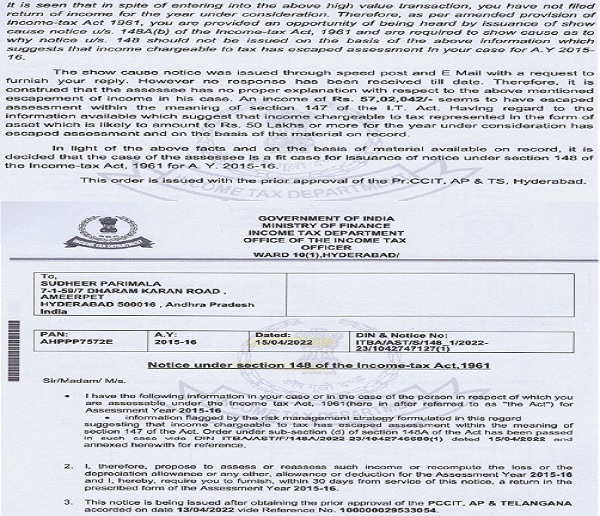
Income Tax
Hyderabad ITAT Quashes AY 2015-16 Reopening – Notice u/s 148 Issued After 6 Years Held Time-Barred Despite ₹50 Lakh Escape Claim
Income Tax
Income Tax
Chennai ITAT Quashes Reassessment – Notice u/s 148 Beyond 3 Years Needs PCCIT Approval, Not PCIT Approval
Income Tax
Income Tax
ITAT Quashes Reassessment as AO Changed Reason from Fake Loan Entries to Penny Stock LTCG
Income Tax
Income Tax
5-Day Share Trade Cannot Automatically Become ‘Bogus Penny Stock’: ITAT Mumbai
Income Tax
Income Tax
Accrued Income Cannot Be Deferred Just Because Receipt Is Delayed – ITAT Upholds Taxability on Mercantile Basis
Income Tax
Income Tax
ITAT Deletes Bogus Purchase Addition as No Evidence Linked Assessee to Alleged Accommodation Entries
Income Tax
Income Tax
No Section 56 Addition as Property Value Difference Was Within 10% Tolerance Band
Income Tax
Income Tax
SC Upholds Reassessment Quash Order Due to Mere Suspicion Without ‘Reason to Believe’
Income Tax
Income Tax
Calcutta HC Quashes Reassessment Due to Mere Suspicion Without Independent Inquiry
Income Tax
Income Tax
Third-Party Loose Papers Cannot Justify Addition Without Cross-Examination: ITAT Delhi
Income Tax
Income Tax
Section 56(2)(x) not Apply to Redevelopment Flats as Transaction Is Exchange of Existing Rights
Income Tax
Income Tax
Bombay HC Quashes Reassessment Due to Approval by Wrong Authority
Explore the latest Section 147 updates on TaxGuru, including relevant Income-tax Act provisions, rules, notifications, circulars, judicial decisions and compliance guidance. The coverage highlights important tax positions, procedural requirements, assessments, deductions, penalties and litigation developments to help taxpayers and professionals understand the practical implications of changes in income-tax law.

