
#income tax act 1961
Log in to FollowLatest income tax act 1961 updates, provisions, case laws, compliance requirements, tax implications and expert analysis under Income-tax law on TaxGuru.
Income Tax
Income Tax
Issuance of notice & all consequential proceedings in the name of deceased assessee are null & void
Income Tax
Income Tax
Interest reimbursement received under Technology Up-gradation Fund Scheme is capital receipt
Income Tax
Income Tax
Taxation on Non-convertible debentures (NCDs)
Income Tax
Income Tax
Cost of Goods Cannot be Included in Denominator of Profit Level Indicator when comparable are Business Auxiliary Service providers
Income Tax
Income Tax
Order passed u/s 148A(d) would remain subject to order to be ultimately passed in reassessment proceeding u/s 148
Income Tax
Income Tax
Addition u/s 40A(3) unsustainable as in liquor business strict adherence to payment via banking channel not practicable
Income Tax
Income Tax
Business profit not taxable in India in absence of Permanent Establishment
Income Tax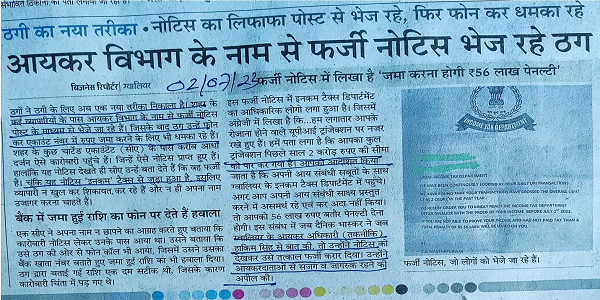
Income Tax
Protecting Taxpayers: Safeguarding Against Fake Income Tax Notices
Income Tax
Income Tax
Addition towards on-money receipts sustained by invoking statue presumption u/s 292C
Income Tax
Income Tax
Addition based on rough notes with corroborative evidence sustained
Income Tax
Income Tax
Legal Absurdity of Income Tax Notices Issued to Deceased Individuals
Income Tax
Income Tax
Credit for advance tax and TDS granted on upload of migration order
Income Tax
Income Tax
Addition in absence of any incriminating material found during search is unsustainable
Income Tax
Income Tax
Significance of Show Cause Notice in Income Tax Proceedings
Explore the latest income tax act 1961 updates on TaxGuru, including relevant Income-tax Act provisions, rules, notifications, circulars, judicial decisions and compliance guidance. The coverage highlights important tax positions, procedural requirements, assessments, deductions, penalties and litigation developments to help taxpayers and professionals understand the practical implications of changes in income-tax law.

