
Rotary Bangalore Orion Gateway Trust Vs ITO (Exemptions) (ITAT Bangalore)
Leadership Changeover Excuse Accepted – Natural Justice Violated – Tribunal Sends Rotary Trust’s 80G Back for Fresh Look
Bangalore ITAT in the case of Rotary Bangalore Orion Gateway Trust, Rajajinagar Vs ITO (Exemptions), dealt with cancellation of approval u/s 80G. Assessee, a public charitable trust formed on 08.06.2019, was granted provisional approval u/s 80G(5) on 23.09.2021, valid up to AY 2024-25. On 29.06.2024, it filed application in Form 10AB seeking final approval. CIT(E) issued notices dated 18.10.2024 & 09.11.2024 calling for documents, but Assessee did not respond. Consequently, CIT(E) cancelled the approval on 04.12.2024, holding that Assessee failed to establish genuineness of its activities.
Before Tribunal, Assessee submitted that cancellation was hasty & mechanical without providing a final opportunity of hearing, amounting to violation of principles of natural justice. It explained that due to the annual changeover of office bearers in June 2024, there was a lapse in internal coordination, resulting in non-compliance with notices. Assessee also filed minutes of board meetings & proof of charitable activities, praying for one more opportunity to substantiate its case.
Tribunal noted that CIT(E) had rejected the application solely for non-response without giving a final opportunity. This, it held, was a gross violation of natural justice. Considering Assessee’s explanation & readiness to produce documents, Tribunal restored the matter to CIT(E) for fresh adjudication. It directed CIT(E) to provide reasonable opportunity of being heard & examine all documents, while also warning that in case of further default, no leniency would be shown. Accordingly, Tribunal partly allowed the appeal for statistical purposes, remanding the case back to CIT(E) for fresh decision in accordance with law.
FULL TEXT OF THE ORDER OF ITAT BANGALORE
This appeal at the instance of the assessee is directed against the order of the ld. CIT(Exemptions) Bangalore dated 4.12.2024 vide DIN & Notice No. ITBA/EXM/F/EXM45/2024-25/1070875708(1) cancelling the approval u/s 80G of the Act of the Income Tax Act, 1961 (in short “The Act”).
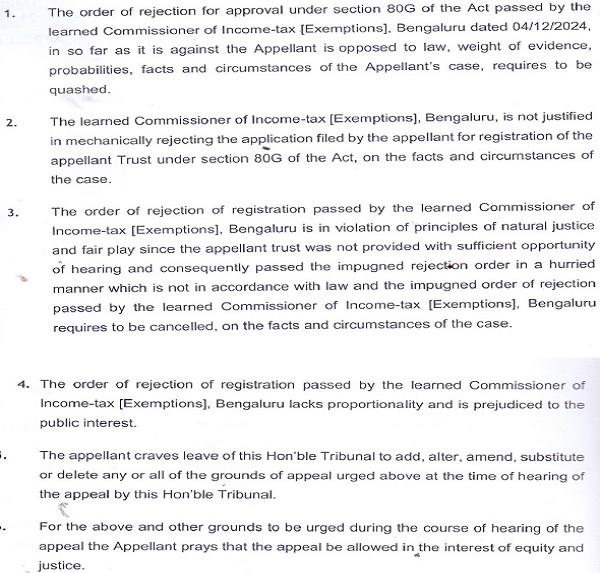
2. In this appeal, the assessee has raised the following grounds of appeal:-
3. Brief facts of the case are that the assessee is a Public Charitable Trust formed vide registered trust deed dated 08/06/2019. The assessee trust has been granted provisional approval u/s 80G(5) of the Act in Form 10AC dated 23/09/2021 bearing URN- AADTR4924PF20216 which was valid up to assessment year 2024-25. The assessee trust filed application in form 10AB dated 29.06.2024 for final approval u/s 80G(5) of the Act. On receipt of aforesaid application, the ld. CIT(E) granted opportunity of being heard vide notices dated 18.10.2024 and 9.11.2024, wherein the assessee was required to appear before the ld. CIT(E), either in person or through an authorized representative along with the documents/details. However, the assessee had not responded. The CIT(E) was of the view that the assessee was mandated to submit necessary documents to prove the genuineness of the activities of the Trust or institution and fulfillment of all the conditions laid down in clauses (i) to (v) of section 80G of the Act and in the present case, assessee has not responded and failed to appear before CIT(Exemptions) and submit the necessary details/documents called for and hence, the ld. CIT(E) rejected the application filed in form 10AB dated 29/06/2024 for the approval u/s 80G(5) of the Act & Approval was cancelled.
4. Aggrieved by the order of ld. CIT(E) dated 04/12/2024, the assessee filed the present appeal before this Tribunal. The assessee has also filed written submission along with the copy of minutes of meetings of the board, proof of charitable activities along two orders of the coordinate bench of the ITAT relied on by the assessee.
5. Before us, the ld. A.R. of the assessee submitted that the ld. CIT(E) hastily & mechanically passed the order cancelling the approval u/s 80G(5) of the Act without providing sufficient opportunity of being heard to the assessee which is a gross violation of the principles of natural justice and accordingly prayed to grant one more opportunity before the ld. CIT(E) to substantiate its claim.
6. Ld. D.R. on the other hand relied on the order of ld. CIT(E) and submitted that the assessee in very callous in the proceedings before the ld. CIT(E).
7. We have heard the rival submissions and perused the materials available on record. On going through the annexure attached to Form No.10AD dated 04/12/2024, we take note of the fact that the ld. CIT(E) Bangalore has rejected the application for approval on the sole ground that the assessee has not filed any reply/documents in response to hearing notices dated 18/10/2024 & 09/11/2024. We also observe that the ld. CIT(E) failed to provide a final opportunity of being heard before rejecting the application which in our opinion is a gross violation of the principles of natural justice Before us, the ld. A.R. of the assessee submitted that in June, 2024, the trust underwent its scheduled annual changeover of the office bearers. However due to an inadvertent lapse in internal coordination arising from the Trust’s annual transition of leadership, these notices could not be timely acted upon. Further, before us, the ld. A.R. of the assessee submitted that one more opportunity may be granted to the assessee trust to represent its case before the ld. CIT(E) for fresh consideration. This being so, in the interest of justice and fair play and as requested by the ld. A.R. of the assessee, we deem it fit and proper to remit the entire issue in dispute to the file of ld. CIT(E) to decide afresh in accordance with law. Needless to say, a reasonable opportunity of being heard must be granted to the assessee. At the same time, we also direct the assessee to produce/submit all the necessary details/documents/record/ financials/reports in support of its claim. We make it clear that in case of further default, the assessee shall not be entitled for any leniency. It is ordered accordingly.
8. In the result, appeal of the assessee is partly allowed for statistical purposes.
Order pronounced in the open court on 1st Sep, 2025







