Subham Verma Vs Commissioner of Customs (Port) (CESTAT Kolkata)
CESTAT Kolkata held that onus cast on appellant u/s 123 not having been discharged, hence concluded that contraband gold smuggled from a third country of origin is liable to absolute confiscation.
Facts- On specific information received by P & I Branch, the appellants were intercepted at Howrah Railway Station.
They were brought to the Customs House after issuing spot summon on them. 6 pcs. of gold bars believed to be of foreign origin having inscription “PMAP SUISSE 1 KILO GOLD 995.0 PMAP ESSYEUR FONDEUR” with tampered Sl.No. were recovered from the packets in the bag with them. The value of the goods was assessed as Rs.1,68,58,500/-. The said gold was seized on the same day on a reasonable belief that that the gold bars had been smuggled into India through an unauthorized channel and is liable for confiscation.
In the statement, the Appellant Nos. (1) to (4) stated that they were gold carriers of Appellant No.(5) and the impugned gold has been obtained by them on 18.05.2015 from Shri Sashikant Patil. They proceeded for Howrah Station on 19.05.2015 to Board the Chambal Express. At the time of search, they were not having any documents with regard to ownership of the gold. It is stated that the said gold is to be handed over to Appellant No (5). They were arrested and produced before the CMM, Bankshal Court on 20.05.2015 and bail was rejected.
On 19.05.2015, the Customs officials visited the premises of Shri Sashikant Patil, but did not find any contraband goods at the said premises.
A show-cause notice was issued to all the Appellants on 28.04.2016 for confiscation of the seized gold and imposition of penalty under Section 112 (b) and 114AA of the Customs Act, 1962. The adjudicating authority confirmed absolute confiscation of seized pieces of gold and imposed penalties. Being aggrieved, the present appeal is filed.
Conclusion- Held that the department has successfully discharged its primary onus at the preliminary stage and with the onus cast onto the appellants under Section 123, not having been discharged in the least, the order assailed warrants no interference and is required to be upheld. Having thus arrived at the irresistible conclusion that contraband gold smuggled from a third country of origin is liable to absolute confiscation and the appellants subjected to imposition of penalty.
Held that the Order-in-Original, confiscating absolutely the said 6kg foreign marked gold alongwith the other items and also uphold the imposition of penalty as contained in operative part of the adjudication order (i) to (xiv).
FULL TEXT OF THE CESTAT KOLKATA ORDER
1. The appellants are in appeals against the impugned order for confiscation of 6 kg gold recovered on 19.05.2015 from Appellant No.(1) to (4 ) and imposition of penalty on all the appellants.
2. The facts of the case are that on specific information received by P & I Branch, CC (P), WB, Kolkata on 19.05.2015, the Appellant Nos. (1) to (4) were intercepted at Howrah Railway Station. They were brought to the Customs House after issuing spot summon on them. 6 pcs. of gold bars believed to be of foreign origin having inscription “PMAP SUISSE 1 KILO GOLD 995.0 PMAP ESSYEUR FONDEUR” with tampered Sl.No. were recovered from the packets in the bag with them. The value of the goods was assessed as Rs.1,68,58,500/-. The said gold was seized on the same day on a reasonable belief that that the gold bars had been smuggled into India through an unauthorized channel and is liable for confiscation. In the statement recorded in the said date, the Appellant Nos. (1) to (4) stated that they were gold carriers of Appellant No.(5) and the impugned gold has been obtained by them on 18.05.2015 from Shri Sashikant Patil @ Banti at Dhanalaxmi Bullion Pvt. Ltd., 43 Nalini Seth Road, 1st Floor, Room No.101, Sona Patty, Kolkata-700007. They proceeded for Howrah Station on 19.05.2015 to Board the Chambal Express. At the time of search, they were not having any documents with regard to ownership of the gold. It is stated that the said gold is to be handed over to Appellant No (5). They were arrested and produced before the CMM, Bankshal Court on 20.05.2015 and bail was rejected.
2.1 On 19.05.2015, the Customs officials visited the premises of Shri Sashikant Patil, but did not find any contraband goods at the said premises. Shri Sashikant Patil was not present , but his cousin brother, Shri Ashish Patil stated that he does not know the Appellant No.(1) to (4) intercepted by the Customs Officers from Customs Appeal No. 79461 of 2018 Howrah Station. Thereafter, on 23.06.2015, summon was issued in the name of Shri Sashikant Patil for his appearance and letter was received by Shri Jiban Ghosh stated that Shri Sashikant Patil was not attending the shop for a few days.
2.2 On 3rd July, 2015, the Hon’ble High Court of Calcutta granted bail to Appellant No.(2) and subsequently, the Appellant Nos. (1), (3) & (4) were also granted bail.
2.3 Again, on 09.07.2015, summon was issued to Shri Sashikant Patil for appearance on 17.07.2015, but he could not appear on the said date as summon was received by him on 23.07.2015. Voluntary statements of Appellant No.(1) to (4) were recorded, who gave contradictory statement in respect of taking delivery of the gold from M/s Dhanlaxmi Bullion Pvt. Ltd.. Thereafter, summon was issued to Appellant No. (5) on 23.09.2015 to appear on 05.10.2015 before the Customs Authorities, but he did not appear.
2.4. On 30.09.2015, the notice of pre-trial disposal of the seized gold, was given by the Customs authorities to Appellant Nos. (1) to (4). On the basis of the said Notice, on 12.10.2015, the said Appellants opposed and objected to the pre-trial disposal of the seized gold and prayed to return the same to the original owner i.e. Appellant No.(5). The Appellant No.(5) also made a prayer for release of the seized gold.
2.5 On 16.10.2015, the statement of Shri Sashikant Patil was recorded, who denied having relation with the Appellant No.(5) and also denied having sold any gold of Appellant Nos. (1) to (4). The Appellant No.(5) also tendered his statement on 26.10.2015 stating that he was engaged in the business of purchase and sale Customs Appeal No. 79461 of 2018 of the gold jewellery at Delhi, Mumbai & Kolkata. He also stated that he knew the Appellant No.(1) to (4), who worked for him. The seized gold was also actually purchased by the Appellant No.(5) from Shri Prodeep Kumar Bhathra of M/s Snehal Gems Pvt. Ltd., Mumbai, Appellant No.(6), against the invoices. The statements of the Directors of said Appellant Companies were recorded on 08.01.2016, who stated that they know the Appellant No. (5) and also accepted that he has sold 6 kgs of gold to Appellant No.(5) against the invoices and tendered the payment related documents.
2.6. On 15.02.2016 and 16.02.2016, the Appellant No. (1) to (4) stated before the Superintendent of Customs that the seized gold were given to them by Appellant No.(5) at Allahabad for the purposes of getting gold jewellery in exchange of the said gold from Kolkata and the statements given by them on 19.05.2015 is not proper and not voluntary. Thereafter, a show-cause notice was issued to all the Appellants on 28.04.2016 for confiscation of the seized gold and imposition of penalty under Section 112 (b) and 114AA of the Customs Act, 1962. The said show-cause notice was contested by all the Appellants, but the adjudicating authority passed the following orders :
(i) I order for absolute confiscation of the seized o6 (six) pieces of smuggled gold bars of foreign origin having total weight of 6 (six) kgs. and valued at Rs.1,68,54,000/- under Section 111 (b) and Section 111 (d) of the Customs Act, 1962.
(ii) I order for confiscation of the 03 (three) clothen pockets especially designed for carrying smuggled gold bars of foreign origin, of cream color (dirty), Ash color & Violet color along with torn papers and brown adhesive tape under seizure, having no commercial value, under Section 119 of the Customs Act, 1962.
(iii) I order confiscation of the 05 (five) old and used mobile phones (1) Micromax Mobile Phone Model No.X258 bearing IMEI No.911335303708505 & 911335303708513, (2) Intex Aqua Star 5.0 Mobile Phone bearing bearing IMEI No.911403851549273 & 911403851599278, (3) Samsung Mobile Phone Model No.SM-G355H bearing IMEI No.356894061942096 & 356895061942093, (4) Samsung Mobile Phone Model No.GT-C3322i bearing IMEI No.35432206582382501 & 35432306582382301 and (5) IRIS Fuel 60 Mobile Phone bearing IMEI No.911417050367444 & 91417050367451 under seizure, under Section 111 (b) and Section 111 (d) of the Customs Act, 1962.
(iv) I impose a penalty of Rs.5,00,000/- on Shri Raghendra Kumar Dhuriya, Noticee No.1 under Section 112 (b) of the Customs Act, 1962.
(v) I impose a penalty of Rs.5,00,000/- on Shri Sourabh, Noticee No.2 under Section 112 (b) of the Customs Act, 1962.
(vi) I impose a penalty of Rs.5,00,000/- on Shri Subham Verma, Noticee No.3 under Section 112 (b) of the Customs Act, 1962.
(vi) I impose a penalty of Rs.5,00,000/- on Shri Golu Verma, Noticee No.4 under Section 112 (b) of the Customs Act, 1962.
(vii) I impose a penalty of Rs.10,00,000/- on Shri Rinku Verma, Noticee No.5 under Section 112 (b) of the Customs Act, 1962. Customs Appeal No. 79461 of 2018
(viii) I impose a penalty of Rs.10,00,000/- on Shri Raghendra Kumar Dhuriya, Noticee No.1 under Section 114AA of the Customs Act, 1962.
(ix) I impose a penalty of Rs.10,00,000/- on Shri Sourabh, Noticee No.2 under Section 114AA of the Customs Act, 1962.
(x) I impose a penalty of Rs.10,00,000/- on Shri Subham Verma, Noticee No.3 under Section 114AA of the Customs Act, 1962.
(xi) I impose a penalty of Rs.10,00,000/- on Shri Golu Verma, Noticee No.4 under Section 114AA of the Customs Act, 1962.
(xii) I impose a penalty of Rs.50,00,000/- on Shri Rinku Verma, Noticee No.5 under Section 114AA of the Customs Act, 1962.
(xiv) I impose a penalty of Rs.50,00,000/- on Shri Pradeep Kumar Bothra, Noticee No.6 under Section 114AA of the Customs Act, 1962.
Against the said order, the appellants are before us.
3. The ld.Counsel appearing on behalf of the appellants, submitted that the ownership of the impugned gold has been claimed by the Appellant No.(5), who has purchased the said gold from Appellant No. (6) through proper Invoices and also placed the copies of invoices issued by Appellant No. (6) on record. The Appellant No. (6) also joined the investigation and submitted all records of purchase, sale invoice, bank statements etc., which certifies that the impugned gold has been sold by the Appellant No.(6) and the payment of the same was made by Appellant No.(5) through proper channel. Therefore, the Appellant No.(5) has also discharged the burden in terms of Section 123 of the Customs Act, 1962 as it has been disclosed the source of procurement of impugned gold and also payment particulars, which was made by through banking channel. He further submitted that initially, the Appellant Nos. (1) to (4) have submitted that they have acquired the possession of the said gold from Mr. Sashikant Patil, but later on, they have stated that they have received the said gold from the Appellant No.(5), Shri Rinku Verma and the revenue proceeded to investigate the matter further to reveal the truth. During investigation, it has come on record that the Appellant No.(5) has acquired the gold through proper channel from Appellant No. (6) and also placed documents were on record, which are not denied any cogent evidence by the adjudicating authority. As the burden in terms of Section 123 of the Customs Act, 1962, has been discharged, in that circumstances, the impugned proceedings are not sustainable. He further submitted that the adjudicating authority failed to give any finding to controvert the transactions between the Appellant No.(5) & Appellant No. (6), but only held that the Appellant No.(1) to (4) altered their version on the direction of Appellant No.(5) in a futile bid to conceal the smuggled nature of the seized gold. The adjudicating authority without establishing the fact, has given the finding that the Appellant Nos. (1) to (4) are habituatal offender without ascertain the fact whether the Appellant Nos. (1) to (4) are involved in such activity in the past. In that circumstances, the gold is not liable for confiscation under 111 (b) & (d) of the Customs Act, 1962 and therefore, the impugned gold is to be released and penalties on the Appellants are not imposable. To support his contention, he relied on following decisions of the Tribunal as well as the Hon’ble High Court, in the cases of
(i) Nitya Gopal Biswas : 2016 (344) ELT 209 (Tri.-Kol.),
(ii) Ratan Kumar Saha : 2012 (275) ELT 435 (Tri.Kol.),
(iii) Impiaz Ikbar Pohiwala : 2019 (365) ELT 167 (Bom.),
(iv) Gopal Prasad : 2018 (362) ELT 309 (Kol.) which has been affirmed by the Hon’ble Patna High Court as reported in 2020 (371) ELT 243 (Patna).
(v) Nand Kishore Somani : 2016 (333) ELT 448 (Tri-Kol), which has been affirmed by the Hon’ble Calcutta High Court as reported in 2016 (337) ELT 10 (Cal.).
(vi) M/s Hari Manthan Jewellery House Pvt. Ltd. vide Final Order No.75480-75484/2022 dated 17.08.2022.
4. On the other hand, the ld.A.R. appearing on behalf of the Revenue, supported the impugned order and submitted that initially when the gold was recovered from the possession of Appellant Nos.(1) to (4), they have stated that they acquired the possession of gold from Shri Patil and later on, at the time of pretrial disposal notice, they have changed their version to cover illicit possession of gold. He also submitted that the Appellant No.(5) has procured the invoices from Appellant No.(6) to make legalized the transactions and the possession of the seized gold is afterthought. Therefore, the said documents cannot be relied upon. To support his contention, he relied upon the decision of the Hon’ble Patna High Court in the case of Md.Akhtar Vs. Commissioner of Central Excise, Customs & Service Tax, Patna Vs. 2015 (323) ELT 136 (Pat.), which was upheld by the Hon’ble Apex Court as reported in 2015 (323) ELT A-27 (SC). He also relied on the decision the Tribunal in the case of R.K.Angangbi Singh Vs. Commissioner of Customs (Prev.), Shillong reported in 2018 (361) ELT 1062 (Tri.-Kolkata). He also relied on the decision of the Hon’ble High Court Kerala in the case of Commissioner of Customs, Cochin Vs. Om Prakash Khatri reported in 2019 (366) ELT 402 (Ker.) He also submitted that the Appellant Nos. (1) to (4) were failed to discharge their onus in terms of Section 123 of the Customs Act, 1962. He, therefore prayed that the impugned order is to be upheld.
5. Heard the parties in detail and considered the records placed before us.
6. We find in this case, initially at the time of investigation on 19.05.2015, 6 kgs. of gold bars were recovered from the possession of Appellant Nos.(1) to (4), who stated that they acquired the possession of gold from Shri Sashikant Patil. Although, the premises of Shri Sashikant Patil was visited on the same day, but Shri Sashikant Patil was not available. No summons were issued to Shri Sashikant Patil to join investigation at that time. Further, we find that at the time of pre-trial notice for disposal of the seized gold, the Appellant Nos.(1) to (4) claimed that the impugned gold pertains to Appellant No.(5) and the Appellant No.(5) also joined the investigation. The investigating team also investigated the Appellant No.(5) to find out whether the Appellant No.(5) is the true owner of the seized gold or not and continued to investigate the matter. The Appellant No.(5) has produced the invoices of seized gold purchased from Appellant No.(6) and the Appellant No.(6) also joined investigation, who produced all the records for verification of the impugned transactions with regard to possession of the seized gold of Appellant No.(5). The said documents have not been rejected by the adjudicating authority or the investigating team during investigation itself and did not discard the same. It is further found out that source of procurement of the impugned gold by licit means by the Appellant No.(6). As the Appellant No.(5), who claims to be the owner of the seized gold, has discharged his burden under Section 123 of the Customs Act, 1962 by producing purchase invoices and the Appellant No. (6) has supported the same. In that circumstances, we are of the view that the Appellant No.(5) has discharged his onus in terms of Section 123 of the Customs Act, 1962 in the light of the decision of the Tribunal in the case of Nitya Gopal Biswas (cited supra), wherein this Tribunal has observed as under :
“6. It is observed from the case records that Smt. Chhabi Biswas and Shri Joy Gopal Biswas were intercepted on 5-9-2000, moving in a Tata Sumo vehicle near Doltala with 60 foreign marked gold biscuits in their possessions. None of those two persons could furnish any document regarding licit possession of the gold biscuits at the time of interception and the said gold biscuits were seized on the ground that they were smuggled when read with Section 123 of the Customs Act, 1962. Both Smt. Chhabi Biswas & Shri Joy Gopal Biswas also stated that these gold biscuits are believed to have come from Bangladesh. Shri Joy Gopal Biswas in his first statement also stated that these foreign marked gold biscuits were obtained from one Joynal for the fourth time. By another statement dated 22-9-2000 of Shri Joy Gopal Biswas, recorded by the investigation in Judicial custody, it was stated that these 60 gold biscuits were handed over to him by his younger brother Shri Nitya Gopal Biswas. Shri Nitya Gopal Biswas also lodged his claim and produced a purchase Bill No. 422, dated 29-8-2000 from one Shri Laljibhai K. Soni, a gold dealer of Ahmedabad. Investigation accepted the statement and followed the Ahmedabad trail by carrying out the investigation at Ahmedabad in detail to refute the claim of Shri Nitya Gopal Biswas. Department never took any initiation to carry out any investigation to trace out whereabouts of Joynal named by Shri Joy Gopal Biswas in his statement dated 5-9-2000 which Revenue is claiming it in their favour. The very fact that the present consignment was the fourth one received from Joynal by Shri Joy Gopal Biswas, investigation should have taken further details about the correct address, mobile number, etc. of Joynal to know as to how Shri Joy Gopal Biswas was contacting Joynal regularly. Simultaneously, following this trail could have easily established the true nature of origin of 60 foreign marked gold whether smuggled or otherwise. Having not done that the whole effort of the department was concentrated to deflate refute the authenticity of purchase bill No. 422, dated 29-8-2000 produced by claimant Shri Nitya Gopal Biswas.
6.1…………………………………
6.2…………………………………
6.3…………………………………
6.4 Adjudicating authority in his finding is also giving a finding in the order-in-Original that there is no legal requirement to mention the details of gold bars in the register but in the same breath continues to say that it is a normal business requirement for proper accounting of stock register, which is astonishingly not done by Gold and Silver ornament merchants. It is observed that If there is no legal requirement to mention details of foreign marked gold bars in the stock register maintained by M/s. Laljibhai K. Soni then neither the seller nor buyer of such gold bars in the present transaction can be held responsible for not mentioning the details of gold markings in the bill. On this issue CESTAT, Mumbai in the case of S.K. Chains v. Commr. of Customs (Prev.), Mumbai [2000 (09) LCX 0202 = 2002 (127) E.L.T. 415 (Tri. – Mumbai)] made following observations in paras 4 to 7 of this order :-
Section “4. 123 of the Act is an exception to the normal rule of the burden being upon the prosecution to establish the guilt of the accused. Ordinarily every element that constitutes the offence has to be proved by the prosecution and this burden never shifts. But the burden shifts on the accused when Section 123 of the Act is invoked. After the initial burden of acquiring reasonable belief is discharged by the Customs, it is the offender who has to establish the lawful importation and acquisition of the gold. The appellants in this case have not questioned the existence of reasonable belief. They, however, consistently claimed that the gold was legally acquired.
Gold 5. occupies a special position in the Indian psyche. Gold is the most liquid investment capable of being encashed at any time in any society or locality. Gold is routinely presented to temples and to relatives on ceremonial occasions. It is customary, even mandatory that a bride is given away with gold ornaments. The demand for gold in India is perennial. There was only one gold mine operating at Kolar near Mysore which would produce about 2 tons of gold every year. That has also stopped functioning. The gap between rising demand and scant supply was invariably filled by smuggling. Estimates vary but it is expected that during the 80s on an average 250 Tons of gold was smuggled into India every year. Any smuggling is bad for the economic health of the country as it would defeat the very purpose behind imposition of restriction on import. The case of gold is more acute. Unchecked smuggling of gold would threaten the very stability of the country’s currency. There was a time when the paper currency in the country was backed fully by the gold held by the Govt. Over the last century the basis and the support for the currency has shifted from Gold reserves to the country’s assets. But every Central Bank still keeps a gold reserve called Monetary Reserve. Thus, gold in the hands of the Central Govt. would make the currency strong and conversely the gold in the hands of the public would weaken the currency. To wean away the Indian public from the craze of the gold and also to ensure stability of the currency the Gold (Control) Act, 1968 was enacted. In fact, the provisions had existed earlier in the Defence of India Rules also. Notifications were issued prohibiting entirely import of gold except by the Govt. Provisions such as Section 120 were incorporated in the Customs Act which continued the liability to confiscation of any gold illegally imported notwithstanding any change in its composition and identity. Provisions of Gold (Control) Act restricted the activity of refining of gold limiting it to the Govt. of India Mint. Making of gold of purity higher than 995 was also prohibited since the imported gold generally is of the purity of 999. This prohibition would make it easy to establish the imported character of the gold. The combined effect of all the acts and prohibitions was to prevent smuggling, to make disposal of the smuggled gold difficult and to make it difficult for smugglers to defend themselves. In those days seizure of gold with foreign marking and of purity of 999 would generally suffice to establish the smuggled nature of the gold. Certain exceptions were made in the early 80s to these rigours. Licences were given to the manufacturers of gold jewellery for import of gold for manufacture into jewellery for export. At a later date, the rigidity of administration of these exemptions was reduced substantially. The banks were permitted to import and sell gold. At a later date passengers of Indian origin arriving into India after a prescribed period of stay abroad were permitted to import 5 kgs. of gold. Gold can also be imported on Special Import Licences. No restrictions were placed upon the disposal of gold so imported on payment of duty. According to official statistics the legal import of gold through these Schemes was of the following magnitude :
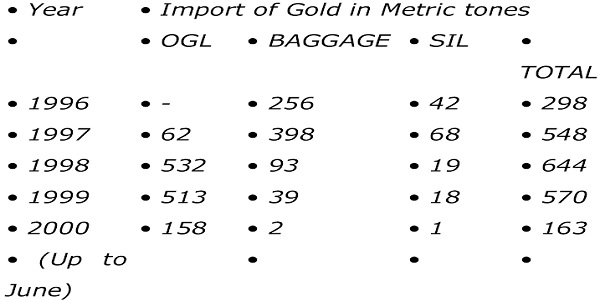
6. As a result of such liberalisation there was ample availability of foreign marked gold in the market. In the absence of any serial numbers on the gold bars it became impossible to distinguish the gold imported legally and that imported illegally.
7. Thus, today there exists a very peculiar situation. On the one hand the Customs Act considers it necessary to ask a person to establish the legality of the origin of the gold seized from him while on the other hand in pursuance of the relaxations made in the Import Policy and the Baggage Rules framed under that very Act, there is a flood of foreign marked gold in the town. Such gold changes hands several times on importation. Since the repeal of the Gold (Control) Act in 1968, there is no legal requirement for the buyers and sellers of gold to maintain any registers nor is there any requirement to issue invoices under any Central Act.”
6.5. CESTAT, Kolkata in the case of Giridhari Dubey v. C.C. (P), Kolkata [2001 (11) LCX 0215) = 2002 (149) E.L.T. 427 (Tri. – Mumbai)] also made following observations in para 3(c) of this order :
In “(c) view of our findings we would set aside the order of confiscation of 32 pcs. of gold also relying at the findings of this Tribunal in the case of S.K. Chains reported in 2001 (127) E.L.T. 415 wherein in Para 10 of the reported decision the Tribunal has considered the effects of the liberalized policy as regards import and dealing in gold and thereafter concluded that that onus as placed under Section 123 was discharged in the facts of that case. We would also considering the onus under Section 123 has been discharged in the facts of this case by the appellants. If the Revenue wants that the gold dealers indulging in sale and purchase of foreign marked gold in India, should indicate the brand names and that discharge under Section 123 shall be only with respect to each brand then foreign marked gold should have been declared as one of the items under Chapter IVA of the Customs Act. We find that no such notification of placing foreign marked gold exists. Therefore the confiscation of the foreign marked gold for non satisfactory brand wise accounting as arrived at in the facts of this case was not called for.”
6.6. In view of the above observations and the settled proposition of law claimant appellant has discharged the onus of licit acquisition of foreign marked gold biscuits by producing a bill. It is also observed from the first statement dated 5-9-2000 of Smt. Chhabi Biswas and Shri Joy Gopal Biswas that it was only their belief that said gold biscuits were from Bangladesh. It is also not coming out of the investigation as to how both of them believed that gold in their possession was of Bangladesh origin. As already observed trace leading to Joynal, mentioned by Shri Joy Gopal Biswas in his very first statement dated 5-9-2000, was not followed by investigation to establish that seized foreign marked gold biscuits were in fact smuggled into India. Reasonable doubt of smuggled nature of foreign marked gold may be sufficient for the purpose of seizure of gold, by virtue of Section 123 of the Customs Act, 1962, but the same is not sufficient for confiscation under Section 125 of the Customs Act, 1962 when appellant has produced legal document of their licit acquisition. Accordingly, it is held that department is not able to establish the smuggled nature of seized foreign marked gold whereas claimant appellant has been able to discharge his burden by providing licit document of the purchase of 60 foreign marked gold biscuits. In the light of liberalized policy of the Central Government it cannot be held that all the foreign marked gold being bought and sold in India is of smuggled nature. Retraction of the earlier statement of Shri Joy Gopal Biswas by a second statement, recorded by investigation in judicial custody, has to be seen in the light of Supreme Court case law of Vinod Solanki v. U.O.I. [2009 (233) E.L.T. 157 (S.C.)]. Hon’ble Apex Court made following observations on the issue where retraction can be accepted.
A “34. person accused of commission of an offence is not expected to prove to the hilt that confession had been obtained from him by any inducement, threat or promise by a person in authority. The burden is on the prosecution to show that the confession is voluntary in nature and not obtained as an outcome of threat, etc. if the same is to be relied upon solely for the purpose of securing a conviction. With a view to arrive at a finding as regards the voluntary nature of statement or otherwise of a confession which has since been retracted, the Court must bear in mind the attending circumstances which would include the time of retraction, the nature thereof, the manner in which such retraction has been made and other relevant factors. Law does not say that the accused has to prove that retraction of confession
made by him was because of threat, coercion, etc. but the requirement is that it may appear to the court as such.”
In the present case the statements of both Smt. Chhabi Biswas and Shri Joy Gopal Biswas were written by one of the panch witnesses Shri Chandan Dey. Even their first statements dated 5-9-2000 only convey that they believed that foreign marked gold came from Bangladesh. The trail of Joynal was not pursued by investigation. It was not existing in the statements of Smt. Chhabi Biswas & Shri Joy Gopal Biswas as to how the seized gold was brought into India and by whom. In the above factual matrix, subsequent statement of Shri Joy Gopal Biswas dated 22-92000 recorded in Judicial Custody was more detailed, authentic and the trail given by Shri Joy Gopal Biswas and Shri Nitya Gopal Biswas was followed by investigation. Shri Laljibhai K. Soni confirmed to have sold the said 60 gold biscuits to the claimant appellant. In view of the above observations made, the findings arrived at by the Adjudicating authority, can only raise strong suspicion about the smuggled nature of seized gold but suspicion howsoever grave cannot take the place of evidence when appellant has discharged his onus. It is accordingly held that statements recorded on 5-9-2000 were not reflecting the correct facts of the case. Accordingly, issue framed at para 5(i) above is decided in favour of the claimant appellant and against the Revenue.”
6.1 Further, in the case of Ratan Kumar Saha (supra), this Tribunal again held that there was a transaction between buyer and seller of the gold, which was claimed and accepted. Therefore, the burden under Section 123 of the Customs Act, 1962, have been discharged.
6.2 Further, in the case of Imtiaz Iqbal Pothiawala (supra), the Hon’ble Bombay High Court has observed as under :
“(ix) The impugned order dated 3rd June, 2005 has held that the respondent No. 1 has discharged the burden of proof under Section 123 of the Act. This as the respondent No. 1 had explained the source of his purchase namely from [M/s. Paras Bullion and M/s. Pavan Jewellers]. In fact, the person running two firms viz; – Mr. Bhupendra Thakkar has himself admitted in his statements to the Office of DRI that the seized gold has been sold by him to respondent No. 1. In fact, on 9th March, 2000, employee of Mr. Bhupendra Thakkar i.e. Mr. Devang Patel, in his statements had shown copies of the invoices to the Officers of DRI, evidencing sale of gold by [M/s. Paras Bullion and M/s. Pavan Jewellers] to respondent No. 1. Besides, the bills showing the acquisition of gold from [M/s. Paras Bullion and M/s. Pavan Jewellers] were also produced with the bail application on 10th March, 2000 filed by respondent No. 1;”
Thereafter, the Hon’ble High Court has held that the burden under Section 123 of the Customs Act, 1962, has been discharged.
6.3 Further in the case of Gopal Prasad, the Tribunal has found that the documents produced for procurement of impugned gold were not found to be false and seller of the gold confirmed the sale, the burden under Section 123 of the Customs Act, 1962, has been discharged.
6.4 In the case of Nand Kishore Sumani (supra), the Tribunal held that when the purchase bills were furnished and the same was confirmed by the seller, the burden under Section 123 of the Customs Act, 1962, has been discharged.
6.5 Further we find that this Tribunal in the case of Hari Manthan Jewellery House Private Limited (supra), has held that when the purchase bills were produced, which were confirmed by the seller of the gold, the burden under Section 123 of the Customs Act, 1962, has been discharged and the gold is not liable to be confiscated.
7. We further take note of the fact that the ld.A.R. for the Revenue has relied upon the decision in the case of Md. Akhtar (supra), the facts of the said case are distinguishable. In the said case, the seller of the gold was found to be bogus on enquiry. Therefore, it was held that the onus was not discharged in terms of Section 123 of the Customs Act, 1962, which is not in the case in hand.
8. Further, in the case of R.K. Angangbi Singh (supra), it was the investigation report that the purchase invoices and transit challans submitted at the time of seizure, are not conformity. It was also found that no sale was actually effected by the dealer whose invoices were produced, but concerned persons of the dealer has given duplicate invoices. In that circumstances, it was held by the Tribunal that the burden is not discharged, which is not the case in hand.
9. We also take note of the fact that in the case of Om Prakash Khatri (supra), the issue before the Hon’ble High Court of Kerala, was that whether the onus of legitimate possession of gold lies on the Revenue under Section 123 of the Customs Act, 1962, wherein the Hon’ble High Court has held that the onus is on the person whose possession of the gold has been recovered, but in this case, the person from whom, the gold has been recovered and claimed to be owner of the seized gold and has produced the purchase invoice, which has been confirmed by the seller of the said gold. Therefore, the onus under Section 123 of the Customs Act, 1962, has been discharged.
10. In view of the above discussions and findings, we hold that the Appellant No.(5) has discharged the onus under Section 123 of the Customs Act, 1962. Therefore, the seized gold is not liable for confiscation. Consequently, no penalties are imposable on all the appellants.
11. In view of the above observation, we set aside the impugned order and allow the appeals with consequential relief, if any.
(Pronounced in the open court on…29.08.2023….)
PER: RAJEEV TANDON
12. The primary question in the present appeals at its very root concerns the evaluation of evidence tendered by the appellants towards discharge of their obligation and onus cast upon them under Section 123 of the Customs Act1, 1962, in respect of the seized/confiscated foreign marked gold; ownership of which has been rather at a much belated stage, claimed by the appellant No. 5- Rinku Verma, of Allababad.
13. The Hon’ble brother Member (Judicial) in view of the invoices tendered by appellant No. 5 (Rinku Verma) towards his claim of the said seized/confiscated gold showing its purchase from appellant No. 6 –Pradeep Kumar Bothra, who also has at a rather quite belated stage joined the investigations and submitted to the authorities the purported records of sale/purchase/payments etc. towards the seized gold for perusal and necessary action by the authorities and based on the decisions in the following cases :-
1. Nitya Gopal Biswas vs. Commissioner of Customs (Prev.) Kolkata2
2. Ratan Kumar Saha vs. Commissioner of Customs, Patna3
3. Union of India vs. Imtiaz Iqbal Pothiawala4
4. Gopal Prasad vs. C.C.E., Customs & S.T., Patna5
5. Nand Kishore Sumani vs. Commr. Of Cus., C.Ex& S.T., Siliguri6
has held satisfactory discharge of the onus in law cast upon the appellants.
14. The Hon’ble Member (Judicial) has therefore arrived at a finding that the said seized and confiscated gold is not liable to confiscation. As a consequence he has set aside the impugned order and allowed the appeals with consequential relief.
15. With reference to the aforesaid order of the learned Hon’ble Member (Judicial) in paragraph 11 above, and in respectful disagreement therewith, I am of the view that before arriving at the said conclusion, a far deeper quest, analysis and examination of the various documents tendered by the appellants towards discharge of the onus cast upon them has to be gone into and therefore record my separate order. Further, the timing of surfacing of the said documents, their production and submission to the authorities and all attendant circumstances vis-à-vis the initial statements tendered by the various noticees before the authorities under Section 108 of the Customs Act and their subsequent change of stance (after Customs Appeal No. 79461 of 2018 an inordinately large interval of time) in certain cases, the timing of joining of investigations by key accused-claimant of the foreign marked gold and the purported seller all need to be considered closely in a holistic and comprehensive manner, interlinking these stray bits of evidence in the spatiotemporal context and the timelines of the case.
FACTUAL RECAP
16. For a quick factual recap, suffice to state that on 19.05.2015, the four appellants 1-4, namely Rajendra Kumar Dhuria, Saurabh, Golu Verma and Shubham Verma were nabbed by the authorities at Howrah railway station with 6 pieces of 1 kg. gold bar each. The said gold was foreign marked of Swiss origin and 995.0 purity. The inscription on the gold bars being ”PMAPSUISSE PMAP ESSAYEUR FONDEUR” While Rajendra Kumar Dhuria and Shubham Verma were found to be in possession of two such gold bars of foreign origin of 1 kg. each, one piece of such foreign marked 1 kg. gold bar was recovered from the possession of each of Golu Verma and Saurabh. The total seized gold was thus 6 kgs. Their interdiction, with the foreign marked gold in their possession, by the authorities is stated to be in pursuance of a specific information available with the authorities, with the accused being pointed out to the authorities by the informant, leading to the recovery of the said 6 kg. of foreign marked gold. The accused, in their initial statement recorded at the time of seizure of gold on 19.05.2015 (all 4 of them) have tendered an almost identical version about the said possession and recovery of foreign marked gold. Thus in the initial statements only, all four of the accused appellants 1-4, namely Golu Verma, Saurabh, Shubham Verma, Rajendra Kumar Dhuriya, have divulged the name of one Rinku Verma of Allahabad for whom they acted as carriers, with all of them admitting to have worked for Rinku Verma multiple times in the past. Of these Rajendra Kumar having acted as a carrier for Rinku Verma for the maximum length of time i.e. upto 20-25 times in the past, from Kolkata. The four accused intimated that they had collected the said gold bars from one Shashi Kant Patil @ Banti at Dhanlakshmi Bullion Pvt. Ltd., Sonapati, Kolkata on 18.05.2015 and were returning to Allahabad to hand over the said gold to Rinku Verma. All of them though have intimated to have worked as carriers in the past as well for Rinku Verma, ranging from 6 months to about 4 years. There is thus complete unanimity in material particulars as well as in substance in the information furnished in the initial statement of all the four accused as recorded before the authorities as regards the source of procurement of gold, the person for whom they acted as carriers, the amount paid to each of them per trip per kg. of gold and this material piece of evidence is of immense significant importance having a direct bearing to the facto legal matrix of the case. As, these aspects having a direct bearing in the matter, they cannot be overlooked and would be required to be considered and examined appropriately.
TIME CHART
17. Before proceeding further with the analysis of evidence it would be appropriate and important to draw out the time lines concerned in the case. These are: