
Shri Shantilal B. Parekh Vs ITO (ITAT Mumbai)
BOGUS PURCHASES –
On the basis of information, huge racket of hawala dealers involved in issuing bogus invoices to allow the traders to claim tax credit was discovered. Assessee was alleged to be one of the beneficiary to who dealt with certain parties engaged in hawala racket. As per AO, assessee was engaged in bogus purchase of INR 2,00,678, wherein, only the bill was received by assessee without receipt of material. The concluded proceeding were re-opened by issuing notice dated 10.05.2013 u/s. 148 and were asked to prove the genuineness of the purchase.
Assessee submitted that all the purchases are genuine and payments has been made through cheque. The purchases was duly accounted for in the books of accounts and reconciliation of purchase and sales were duly submitted.
DISALLOWANCE OF EXPENDITURE –
Cash expenditure of INR 1,11,420 (donation, rent, and miscellaneous expenditure of printing and stationery, tea and refreshment, travelling etc.) was disallowed on account of absence of supporting documents.
HELD –
BOGUS PURCHASES –
Since the assessee couldn’t produce the parties before lower authorities and the fact that the parties have admitted to be indulging in bogus accommodation entries and even assessee couldn’t produce confirmation from the parties, it was held that the profit embedded in the purchases which is required to be brought to tax wherein the assessee had obtained bogus bills from these parties to avoid paying tax and to inflate costs. Thus, 12.5% of the alleged bogus purchase are bought to tax as an income embedded in these purchase.
DISALLOWANCE OF EXPENDITURE –
Donation couldn’t be allowed in absence of supporting bill/ details.
Rent expense of INR 54,000 was claimed as business expense, however, no details as to premises and its use for business, payer/landlord and rent deed etc. were not furnished by the assessee. Assessee only submitted self-supporting vouchers with respect to rent payment in cash without any evidence filed towards rent expense paid and therefore addition of rent expense was confirmed.
Cash expenses relating to printing & stationery, tea and refreshment, mobile charges, labour charges, travelling charges and sundry expenses are supported by self-made vouchers and it was held that it represents only 0.23% of total expense and keeping in view the preponderance of probability as also keeping in view nature of expense and also noting that the expense represents miniscule amount vis-à-vis total expense the said expenditure was allowed.
FULL TEXT OF THE ITAT JUDGEMENT
These are two appeals, filed by assessee, being ITA No. 4261 & 4262/Mum/2017 for AY 2009-10 and 2010-11 respectively , are directed against common appellate order dated 29.03.2017 passed by learned Commissioner of Income Tax (Appeals)-1, Thane (hereinafter called “the CIT(A)”) in Appeal No. 222 & 223/15-16, for assessment year’s 2009-10 & 2010-11 respectively, the appellate proceedings had arisen before learned CIT(A) from separate assessment order(s) both dated 19.01.2015 passed by learned Assessing Officer (hereinafter called “the AO”) u/s 144 r.w.s. 147 of the Income-tax Act, 1961 (hereinafter called “the Act”) for AY 2009-10 & 2010-11 respectively. Since both these appeals raises similar issues and common grounds, both these appeals were heard together and disposed of by this common order.
2. First we shall take-up appeal in ITA no. 4261/Mum/2017 for AY 2009-10 filed by the assessee . The grounds of appeal raised by the assessee in ITA no. 4261 /Mum/2017 for AY 2009-10 in memo of appeal filed with the Income-Tax Appellate Tribunal, Mumbai (hereinafter called “the tribunal”) reads as under:-
“1) In the facts and circumstances of case and in law, the learned CIT(A)-1, Thane erred in confirming the disallowance of purchases of Rs. 2,00,678/- as hawala purchase
a) without providing any opportunity of cross examination of the witnesses or documents relied upon by the Assessing Officer and thus violating the law laid down by Honorable Supreme Court in the case of Kishanchand Chellaram v, CIT (1980) 125 ITR 713 and Andaman Timber Industries v. Commissioner of Central Excise (Civil Appeal No. 4228 of 2006.)
b) on surmises and allegation that the suppliers have refunded cash to the appellant without any piece of evidence and enquiry in this regard,
c) by rejecting the books of account duly maintained by the appellant and audited u/s. 44AB merely on surmises and conjectures without pointing out any defect in the books of accounts
d) ignoring the quantitative reconciliation of purchases with corresponding sales, and
e) ignoring the Gross Profit and Net Profit margins trend of preceding years.
2) In the facts and circumstances of case and in law, the learned CIT(A)-1, Thane erred in sustaining disallowance of expenses of Rs. 1,33,253/- as unverifiable expenses merely on surmises and conjectures,
3) Without prejudice to ground no. 2 above, in the facts and circumstances of case and in law, the learned CIT(A)- 1, Thane erred in sustaining addition of disallowance of expenses of Rs. 1,33,253/- as against 20% of such expenses as accepted by the AO in his remand report.”
3. The assessee is reseller of Engineering Goods. The information was received by AO from DGIT (Inv.) , Pune that the Sales Tax Department, Mumbai has unearthed a racket involving more than 1935 Hawala Dealers involved in issuing bogus invoices to allow traders to claim tax credits and there are more than 37000 beneficiaries who claimed such bogus purchases and bogus tax credits. The Sales Tax Department recorded statements of these Hawala Dealers and these dealers have also filed an affidavits before Sales Tax Authorities wherein they admitted that they have not done any genuine business and stated to have been engaged in issuing bogus sales bills to various parties without supplying any material . The assessee was stated to be one of the beneficiary who had dealt with certain parties who were listed by the Sales Tax Department as hawala dealers .The information received by the AO stipulated that the assessee made following bogus purchases to the tune of Rs. 2,00,678/- which were stated to be from these alleged Hawala Dealers being bogus accommodation entry provider wherein the assessee merely obtained bogus bills without supply of any material , as detailed here under:
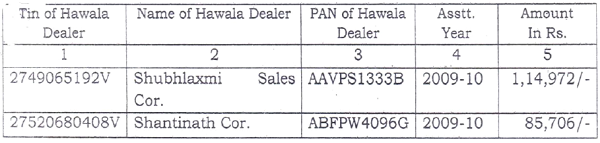
This information so received by the AO led to re-opening of the concluded assessment wherein notice dated 10.05.2013 was issued by the AO to the assessee u/s. 148 of the Act . The assessee was asked to produce various details in order to prove the genuineness of these purchases. The assessee denied before the AO to have taken any accommodation entries of bogus purchases. The assessee submitted that all the purchases are genuine and payments were made by cheque. It was submitted that all purchases were accounted for and genuine . It was submitted that stock of goods received vide these purchases were sold to customers and duly accounted for in books of accounts and credited to Profit and Loss Account. The assessee submitted that if purchases are disallowed then the whole corresponding sales against these purchases will become taxable which is not in accordance with law as the sale cannot happen without corresponding purchases. The assessee was asked by the AO to submit Invoices of Purchases, Bank Book, Cash Book, Ledger, Sales Register, Purchase Register , Financial Statements, Stock Register , Complete name and addresses of the parties from whom purchases were made and to whom corresponding sales were made. The AO also asked the assessee to furnish confirmation, delivery challans, lorry receipts and to produce the parties from whom purchases were made. The assessee failed to produce the aforesaid details before the AO during assessment proceedings which led the AO to make the additions to the tune of Rs. 2,00,678/- to the income of the assessee towards bogus purchases made by the assessee from these hawala dealers by invoking provisions of Section 69 of the 1961 Act. Further , additions of Rs. 65,18,663/- was made by the AO to the income of the assessee being 20% of the expenses incurred by the assessee because as per AO the assessee failed to prove the genuineness of these expenses and hence keeping in view that these expenses were not supported by documentary evidences and remained unverifiable, the AO rejected books of accounts of the assessee by invoking provisions of Section 145(3) of the 1961 Act and made addition of the income of Rs. 65,18,663/- in the hands of the assessee by invoking provisions of Section 37(1) of the Act, vide assessment order dated 19.01.2015 passed ex-parte u/s 144 read with Section 147 of the 1961 Act.
4. The assessee filed first appeal before Ld. CIT(A) and made detailed submissions as also filed additional evidences before learned CIT(A). The remand report was called by Ld. CIT(A) from AO. The AO submitted in its remand report that the assessee has now submitted ledger extracts, invoices, delivery challans and proof of making payments by cheque. The assessee furnished bank account statement and sated that all payments to these Hawala Dealers were made by cheque. However, the assessee failed to produce these parties before the authorities below for verification. The assessee also could not file confirmation letter from these parties regarding purchases made which led AO to conclude in its remand report that it is not possible to verify whether goods alleged to be purchased from these parties were infact received by the assessee. Thus, the AO rejected in its remand report, the additional evidences filed by the assessee and concluded that it is not possible to verify these purchases and to conclude that these purchases were genuine as only accommodation bills were obtained by the assessee from Hawala Dealers. The assessee in rejoinder reiterated its stand before the learned CIT(A) and prayed that these purchases are genuine by relying on various decisions of the Courts/Tribunal as cited in learned CIT(A) order, but Ld. CIT(A) did not agree with the contention of the assessee and entire additions of Rs. 2,00,678/- was confirmed by Ld. CIT(A) so far as alleged purchases made by the assessee from Hawala Dealers is concerned , vide appellate order dated 29.03.20 17 passed by learned CIT(A).Similar additions on account of alleged bogus purchases from hawala dealers were confirmed by Ld. CIT(A) for AY 2010-11 , vide common appellate order dated 29.03.20 17 , by holding as under:-
“8. The appellant in response to this addition has made very detailed submissions placed in the paper book filed with the submissions. The appellant also filed the following chart to show the gross profit and net profit rate for the year under consideration and the preceding and succeeding years –



