
Mystic Electronics Ltd. Vs DCIT (ITAT Mumbai)
ITAT Mumbai held that in case of company is involved in providing illicit LTCG/ short term capital loss (accommodation entries), a substantial addition has to be made in the hands of beneficiaries and only a protective assessment can be made in the hands of company providing such accommodation entries.
Facts- The assessee company filed its return of income declaring total income of Rs. 31,51,330/-. Assessee filed a revised return declaring the income at Rs. 35, 48,140/-. Consequently, the case of the assessee was selected for scrutiny and a notice u/s. 143(2) of the Act.
A search and seizure u/s. 132 of the Act was carried out in the case of Raj Kumar Kedia Group. The main allegation was that it is engaged in providing various types of accommodation entries to large number of beneficiaries all over the country.
Shri R.K. Kedia in his statement admitted that the assessee company is under the control and management of Shri Krishan Kumar Khadaria of Mumbai, who is a close friend of him and is in the same business of providing accommodation entries. That booking for bogus prearranged LTCG was done through the scrip of Assessee Company.
AO concluded that assessee is a listed company and involved in generating illicit LTCG /short term capital loss. AO added back an amount of Rs. 23,07,50,000/- u/s. 68 received by the company under the head share capital during the year under assessment on the premise that preferential share allotment /warrants is merely a paper transaction and capital is being subscribed by dubious persons. AO further rejected the books of accounts of the assessee u/s. 145 and estimated the income at the rate of 1% i.e. Rs. 23, 44,406/- of total turnover i.e. Rs. 23, 44, 40,568/-. In addition to this, AO further added the income shown under schedule 13 as other income amounting to Rs. 45,44,563/-.
CIT(A) partly allowed the appeal. Being aggrieved, the present appeal is filed.
Conclusion- Held that it is a settled position of law that in such type of transactions unexplained income has to be taxed in the hands of beneficiaries consisting of amount of capital gains and if require the amount of investment made in the shares of assessee company. A substantial addition has to be made in the hands of beneficiaries and only a protective assessment can be made in the hands of company like assessee. In this process, by any reason if the department is not able to tax beneficiary then only a substantial addition can be made in the hands of assessee company. In this case, the only addition which is warranted in the hands of Assessee Company is amount of commission earned on arranging long term capital gains /short term capital losses. If investor in such type of company is able to prove its source of investment, then no addition can be made in the hands of assessee company being genuine transaction as identity, genuineness and creditworthiness is automatically established and in vice-versa position also amount of investment is taxable in the hands of investor, then also not taxable in the hands of assessee company, being double taxation. In view of this, the addition made u/s. 68 amounting to Rs. 23, 07, 50,000/- is unwarranted.
FULL TEXT OF THE ORDER OF ITAT MUMBAI
1. These appeals by assessee and cross appeals by revenue are directed against the order of Ld. CIT (A) – 52. Mumbai dated 27.01.2017 and 27.12.2017 u/s. 250 of the Income Tax Act, 1961 (in short ‘the Act’) for A.Y. 2014-15 and 2015-16 respectively.
2. The assessee has raised the following grounds of appeal in ITA No. 5867/Mum/2019 for AY 2014-15:-
1. The Ld. CIT (A) erred in upholding the validity of assessment made u/s. 143(3) of the Act.
1. i. In doing so, the ld. CIT(A) did not appreciate that
a. the proceedings u/s 143(2) of the Act which were abated pursuant to proceedings initiated u/s 153C of the Act could have revived only if the proceedings initiated u/s. 153C of the Act have been annulled in appeal or any other legal proceedings and will stand revived with effect from the date of receipt of such annulment by the Pr. CIT or CIT which facts are totally missing in the appellant’s case.
b. the appellant did not challenge the power of the AO to drop the proceedings initiated u/s 153C of the Act but what was challenged was his jurisdiction to revive the abated proceedings initiated u/s 143(2) of the Act, and
c. the assessment year under appeal was an abated assessment and not a non-abated assessment as stated by him.
2. The Ld. CIT(A) erred in holding that the assessment made was in accordance with law even if no opportunity was given to the appellant to cross examine the persons whose statements were relied upon in drawing the adverse inference.
3. The ld. CIT (A) erred in confirming the action of the AO in rejecting the books of account and estimating profit for the year at Rs.23, 44, 406/- being 1% of turnover on the ground that the appellant was a penny stock / paper company and it was not engaged in any real business activity ignoring the past history of the case.
3. i. In doing so, the ld. CIT (A) did not appreciate that
a. the AO rejected the books of account and estimated the profit on a ground other than the ground on which show cause was given, which has rendered action of the AO as bad in law,
b. even if the scrip of the appellant company is used by the operators for providing bogus LTCG as alleged, the same cannot be a ground to consider its business transactions as sham,
c. the AO, in rejecting the book results, has neither made any enquiry worth the name with regard to purchases and sales disclosed in the Statement of Profit & Loss nor has established the transactions to be sham or not bonafide.
d. the AO could not have rejected the books of account without establishing the defects, incompleteness and inaccuracies in the accounts of the appellant as required u/s 145(3) of the Act, and
e. the facts in the decisions relied upon by him were totally distinguishable in as much as the courts have upheld the rejection of books of account on the ground of absence of proper documentation and/or non-maintenance of stock register which are not the facts of the appellant and on the contrary the decisions relied upon by the appellant are directly on the point.
3.ii. In any event, the ld. CIT(A) did not appreciate that the AO in rejecting the book results and estimating profit for the year at Rs. 23,44,406/- being 1% of the turnover could not have separately assessed the other operating income of Rs. 45,44,563/-credited to the Statement of Profit & Loss.
4. The ld. CIT (A) erred in confirming the addition u/s 68 of the Act to the extent of Rs. 4,96,87,500/- subject to verification by the AO.
4.i. In doing so, the ld. CIT (A) erred in
a. not appreciating that no formal show cause was given by the AO prior to making the said addition,
b. not appreciating that the addition has been made by the AO solely on the basis of statement of Shri R. K. Kedia and the conclusion of the search action without any independent enquiry being made by him either in the course of assessment proceedings and / or in the course of remand proceedings as was directed to him,
c. ignoring the decisions of the Guwahati High Court & the MP High Court relied upon by the appellant in support of the proposition that the income returned & capital of the share applicants are not the only criteria to judge creditworthiness,
d. laying down a basis/formula for the above addition which is not supported by any express provision of law,
e. following the principles laid down by the Apex Court in the case of NRA Iron & Steel Pvt. Ltd. [412 ITR 161 (SC)] and by the Delhi High Court in the case of D. K. Garg [84 taxmann.com 257] without appreciating that the facts of the said cases are totally distinguishable with the facts of the appellant and in any event while summarizing the principles that emerged from the decision of the Delhi High Court in the case of D. K. Garg (supra) did not appreciate that as per the said decision, the onus cast u/s. 68 of the Act has to be discharged by the dummy concern only in respect of those credits where identity of the depositors is not available while in the case of the appellant, the identity of each of the shareholders is fully established,
f. not appreciating that identity, genuineness & creditworthiness of the persons from whom the share capital of Rs. 4,96,87,500/- was received stood fully established in as much as notice u / s 133(6) of the Act issued in the course of remand proceedings were served on them and they have not only confirmed the transactions but have also furnished their relevant bank statements, balance sheet and acknowledgement for having filed return of income, not appreciating that the appellant being a widely held public limited company its onus under the provisions of section 68 of the Act was fully discharged having regard to the principles laid down by the Apex Court in the case of Lovely Exports Pvt. Ltd. [216 CTR 195(SC)] and Stellar Investment Ltd. [(2011) 115 Taxman 99 (SC)], and
h. not appreciating that neither any incriminating material was found in the course of search action nor any adverse inferences could be drawn merely on the basis of statements of the persons referred to and relied upon by him without bringing any corroborative material in support of the same.
3. Brief facts of the case are that assessee company filed its return of income on 31.11.2014 declaring total income of Rs. 31,51,330/-. Assessee filed a revised return on 31.03.2015 declaring the income at Rs. 35, 48,140/-; however there was no reason on record for revising the return of income. Consequently, case of the assessee was selected for scrutiny and a notice u/s. 143(2) was issued on 19.09.2015.
4. In addition to the facts above, it is pertinent to mention that a search and seizure u/s. 132 of the Act was carried out in the case of Raj Kumar Kedia Group on 13.06.2014 by the DDIT (lnv.), Unit-3(3), Delhi. The main allegation against the group was that it is engaged in providing various types of accommodation entries to large number of beneficiaries all over the country. One of various types of accommodation entries provided by R.K. Kedia group is that of bogus LTCG by pre-arranged trading in shares of various non-descript listed companies, which are under the control and management of the syndicate of entry operators.
5. In the light of above, the case of assessee was centralized to the charge of DCIT, Central Circle – 4(3) The case of the assessee was assigned to this Circle as per order u/s 127(2) passed by the PCIT-10, Mumbai vide order PCIT-10/u/s.127/53/2/2016-17-/1430 dated 16.09.2016.
6. Shri R.K. Kedia in his statement admitted that the assessee company is under the control and management of Shri Krishan Kumar Khadaria of Mumbai, who is a close friend of him and is in the same business of providing accommodation entries. That booking for bogus prearranged LTCG was done through the scrip of Assessee Company. Shri Manish Arora, who is the main employee of Shri Raj Kumar Kedia who keeps records of unaccounted transactions of Shri Raj Kumar Kedia has also admitted that the shares of assessee company were jacked up and Shri Kedia manages & arranges sale & purchase of shares in the scrip of assessee company. Further, Shri Natwar Lal Daga, who is also an entry operator based in Mumbai and is, helping Shri Raj Kumar Kedia admitted while replying the Q.21 during the course of his statement recorded on oath u/s. 132 of the IT Act, on 13.06.2014 that he had arranged investors for preferential issue in the assessee company on the instructions of Shri Krishan Kumar Khadaria.
7. Relevant findings pertaining to the matter as observed by the AO vide page 14 to 16 of assessment order is reproduced herein below:-
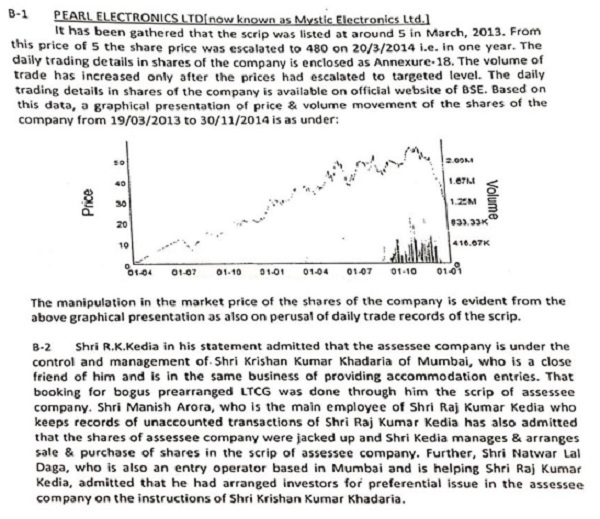
B-3 During the course of search, statement of Sh. Krishan Kumar Khadaria has been recorded. However, it is seen from his statement that he could not give any logical explanation as to why the companies in which he is promoter and director, experienced such a huge rise in price of their shares. No attempt of justification in the form of financial strength and/or any sort of potential future prospects/publicity of the companies was made by Sh Krishan Khadaria. When confronted, Sh Khadaria simply explained away such observations by merely submitting that there was no single share transaction belonging directly or indirectly to him in these scrips. In view of this, as discussed earlier, there is no rationale behind such abnormal price rise in the shares of these companies, except a controlled arrangement of manipulated price rise in order to provide profitable exit to the beneficiaries/preferential allottees by providing them accommodation entries of bogus LTCG.
8.4 During the course of post-search enquiries, vide his statement dated 07.08.2014, Sh Rajesh Om Prakash Aggarwal, employee of Shri Krishan Kumar Khadaria, revealed that certain transaction in the scrip of assessee company were carried out on the instructions of Sh Krishan Khadaria, who had strong linkages with Sh R K Kedia. Further, it was also revealed that this share transaction was not for any preferential allotment, but for sale in secondary market, substantiating thereby the allegation that such share transaction was manipulative in order to realize desired result(s) there from. From the above, it gets substantiated that manipulative trading in the shares of M/s. Pearl Electronics Limited has been done by Sh. Krishan Kumar Khadaria in order to provide various accommodation entries such as those of LTCG, LTCL, STCG, STCL etc to different beneficiaries.
B-5 During the course of search, the investigation wing detected that the activities of the assessee company was not real. Moreover, the parties transacting with Pearl Electronics and Pearl Agriculture are found to have no creditworthiness or are under the control of same group. Such arrangement is done in order to show some genuine business activity in these companies, which is not actually the case. No prudent investor would invest in the shares of such a company unless some prearranged desired capital or loss is ensured to such investor. It is found that there are no substantial business transactions taken place in M/s. Pearl Electronics Ltd. and that trading in its shares has been manipulated for providing profitable exit to various beneficiaries by availing them bogus LTCG. The relevant year wise data is placed as under:







Comments are closed.