Learning Curve Edutech Solutions Pvt. Ltd. Vs PCIT (ITAT Mumbai)
ITAT held that PCIT cannot revise an assessment order under sections 263 of Income Tax Act, 1961 in respect of issues already covered during assessment.
The law is very well settled that revision jurisdiction under section 263 of the Act could be done only in the case of ‘lack of enquiry’ by the learned Assessing Officer. In this case facts clearly prove that there has not been any ‘lack of enquiry’ by the learned Assessing Hence, learned PCIT categorically erred in invoking revision jurisdiction under section 263 of the Act in the instant case on the issue of examination of share premium in the context of section 56(2)(vii)(b) of the Act.
FULL TEXT OF THE ORDER OF ITAT MUMBAI
This appeal is directed against the order passed by learned Principal Commissioner of Income Tax (PCIT)-7, Mumbai under section 263 of the I.T. Act vide order dated 02.12.2019.
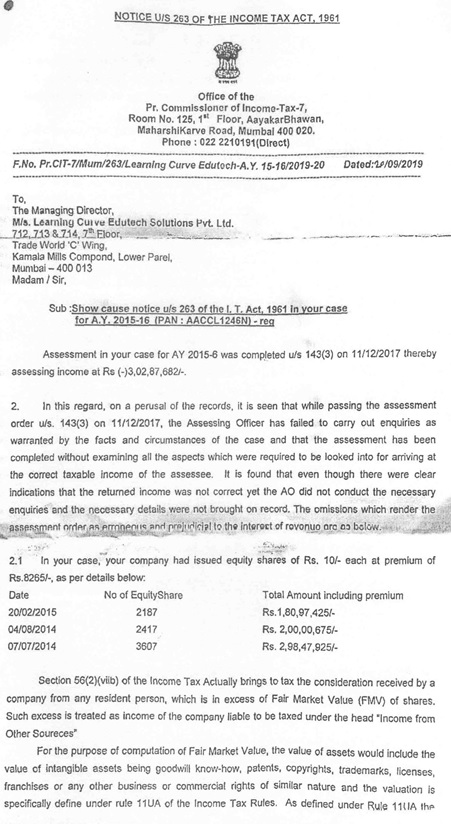
2. We have heard the rival submissions and perused the material available on record. We find that the assessee in its grounds had challenged both assumption of jurisdiction under section 263 of the Act by learned PCIT as well as directions issued by learned PCIT to the Assessing Officer on merits. The assessee is engaged in the business of running day-care centres and nursery. The return of income for assessment year 2015-16 was filed by the assessee company on 30.7.2015 declaring total income of Rs Nil after claiming carry forward of current year loss of Rs. 3,02,87,682/-. The assessment was completed under section 143(3) of the Act by the learned Assessing Officer on 11.12.2017 accepting returned loss of the assessee both under normal provisions of the Act as well as in the computation of the book profit under section 115JB of the Act. In this assessment order, the Assessing Officer in paragraph 2 had stated that the authorized representative of the assessee company had attended hearings conducted from time to time and filed various details which were placed on record and all those details were duly verified by him during the course of assessment proceedings. This assessment order was sought to be revised by learned PCIT under section 263 of the Act on the ground that the order passed by the Assessing Officer is erroneous in as much as it is prejudicial to the interest of revenue on certain aspects which were discussed elsewhere in this order.
3. We find that during the year under consideration the assessee had issued shares to the following persons as under :
Promoters category
Mr. Emron Samuel – 1202 shares
Mr. Suhas Bedekar – 1202 shares
Miss Swati Bhatt – 1203 shares
Investors category (other than promoters)
Mr. Sunil Dalal & Mrs. Nina Dalal belonging to Dalal group – 7021 shares
The aforesaid shares having face value of Rs 10 per share were issued at premium of Rs. 8265 per share. We find that the assessee had justified issue price of Rs. 8275 per share based on valuation report dated 30.6.2014 obtained from independent firm of Chartered Accountants. From the perusal of the valuation report, we find that the valuer adopted Discounted Cash-Flow (DCF) method for valuing shares of the assessee company. It is not in dispute that DCF method is one of the approved method of valuation of shares under Rule 11U & 11UA of the I.T. Rules. During the course of assessment proceedings, we find that the Assessing Officer had indeed called for the details of valuation of shares apart from proving the identity and creditworthiness of the share subscribers together with genuineness of share premium transactions. The assessee had duly furnished all relevant details in this regard before the learned Assessing Officer. In fact we find that the assessee in its audited financial statement had clearly specified fresh issue of shares mentioning number of shares issued and name of the share holders to whom it has been issued. We find that during the course of assessment proceedings learned Assessing Officer had raised specific query vide notice under section 142(1) of the Act dated 9.11.2017 seeking justification of share premium/share application money received against un-allotted shares with valuation report. The Assessing Officer had also further asked the assessee to establish with cogent documentary evidences proving identity and creditworthiness of the share applicants as well as genuineness of the transaction. We find that the assessee had duly responded to the said query vide its letter dated 4.12.2017 filed before the learned Assessing Officer furnishing copy of confirmatory letters alongwith computation of income and copy of ITR acknowledgment in case of the promoters of the company and copy of confirmatory letters in the case of other persons from whom share capital, share premium and share application money was raised during the year. Further the assessee had also enclosed valuation report issued by independent firm of Chartered Accountants for justification of share premium received by the assessee. In the said reply the assessee had also categorically stated that valuer had adopted DCF method for valuing shares. We find from the perusal of the valuation report issued by the independent valuer dated 30.6.2014, which is enclosed in page No. 29 to 41 of the factual paper book filed before us, wherein value had arrived at issue price of Rs. 8275/- per share to be the fair value based on elaborate reasoning and financial working thereon using DCF method. Learned Assessing Officer had taken these documents on record and accepted this stand of the assessee during the course of assessment proceedings. While this is so, we are unable to comprehend ourselves regarding the observations made by learned PCIT that the Assessing Officer had not made necessary enquiries into share premium receipt during the course of assessment proceedings. In fact learned PCIT looks into very same valuation report dated 30.6.2014 which is already on record and arrived at a conclusion that the issue price appears to be inflated and valuation carried out by independent valuer cannot be treated as fair market value. The main observation of learned PCIT is that independent valuer had worked out the issue price on the basis of period from 1st June to 31st May and not from 1st April to 31st March. For the sake of ready reference, show-cause notice issued by learned PCIT under section 263 is reproduced hereunder :