
Director-General of Anti-Profiteering Vs Lite Bite Travel Foods Pvt. Ltd (National Anti-Profiteering Authority)
The application had been filed under Rule 128 of the CGST Rules 2017, alleging profiteering in respect of restaurant service supplied by the Respondent (Franchisee of M/s. Subway Systems India Pvt Ltd.). In the application. it was alleged that despite the reduction in the rate of CST from 18% to 5% w.e.f, 15.11.2017, the Respondent had not passed on commensurate benefit since he had increased the base prices of his products.
The Respondent has claimed that he was operating both of his Subway outlets under investigation under the franchisee model, wherein Mis Subway Systems India Pvt. Ltd. was the ultimate authority which controlled the prices, POS and any revision in the prices and the Respondent has no real control over the prices of the products being sold. Therefore, profiteering, if any, should be demanded from the franchisor i.e. M/s Subway India. Upon perusal of the agreement between the Respondent and M/s Subway Systems India Pvt. Ltd_ i e, the franchisor, it is revealed that there isn’t any clause related to the control of the prices or MRP of the products supplied by the Respondent. The Respondent was free to fix the prices of his products. Further, the provisions of Section 171 of the CGST Act, 2017 required a registered person under GST to pass on the benefit of additional ITC or reduction in the rate of tax by way of commensurate reduction in the prices of the goods or services supplied by him Hence, it is the responsibility of the Respondent to comply with the provisions of Section 171 of the CGST Act: 2017. Therefore, the contention made by the Respondent is not correct.
The Respondent has further contended that the right to reasonable profit was a part of the right of trade and any methodology prescribed under Section 171 of the Act, ibid, could not be de-hors a reasonable profit. In this regard, it is pertinent to mention that this Authority doesn’t have the mandate to regulate the same. The Respondent is free to exercise his right to practice any profession or to carry on any occupation, trade or business, as per the provisions of Article 19 (1) (g) of the Constitution. He can also fix his prices and profit margins in respect of the supplies made by him. Under Section 171 this Authority has only been mandated to ensure that both the benefits of tax reduction and ITC which are the sacrifices of precious tax revenue made from the kitty of the Central and the State Governments are passed on to the end consumers who bear the burden of the tax. This Authority is charged with the responsibility of ensuring that both the above benefits are passed on to the general public as per the provisions of Section 171 read with Rule 127 and 133 of the CGST Rules, 2017. This Authority has nowhere interfered with the business decisions of the Respondent and therefore, there is no violation of Article 19 (1) (g) of the Constitution.
Based on the above facts the profiteered amount is determined as Rs. 61.67,097/- as has been computed in Annexure-15 of the DCAP’s Report dated 25.10.201g. Accordingly, the Respondent is directed to reduce his prices commensurately in terms of Rule 133 (3) (a) of the above Rules, Further, since the recipients of the benefit, as determined, are not identifiable, the Respondent is directed to deposit an amount of Rs. 51,67.0971- in two equal parts of Rs. 30,83,548.501- each in the Central Consumer Welfare Fund and the Maharashtra State Consumer Welfare Fund as per the provisions of Rule 133 (3) (c) of the CGST Rules 2017, along with interest payable 18% to be calculated starting from the dates on which the above amount was realized by the Respondent from his recipients till the date of its deposit. The aggregate amount of Rs 61,67,097/- shall be deposited, as specified above, within a period of 3 months from the date of passing of this order failing which it shall be recovered by the concerned SGST Commissioner.
FULL TEXT OF ORDER OF NATIONAL ANTI-PROFITEERING APPELLATE AUTHORITY
1. The present Report dated 25.102019, received on 30.102019 by this Authority, has been furnished by the Applicant i.e. the Director General of Anti-Profiteering (DGAP), under Rule 129(6) of the Central Goods & Services Tax (CGST) Rules, 2017. The brief facts of the case are that a reference was received by the DGAP from the Standing Committee on Anti-Profiteering on 02.05.2019 recommending a detailed investigation in respect Of a report dated 24.02.2019 submitted by the Joint Commissioner (AE), CGST & CX, Mumbai East and originally examined by the Maharashtra State Screening Committee on Anti-profiteering. The application had been filed under Rule 128 of the CGST Rules 2017, alleging profiteering in respect of restaurant service supplied by the Respondent (Franchisee of M/s. Subway Systems India Pvt Ltd.). In the application. it was alleged that despite the reduction in the rate of CST from 18% to 5% w.e.f, 15.11.2017, the Respondent had not passed on commensurate benefit since he had increased the base prices of his products.
2. The DGAP his report has stated that on receipt of the said reference from the Standing Committee on Anti-profiteering, a notice under Rule 129 (3) of the CGST Rules, 2017 was issued on 14.05.2019. calling upon the Respondent to reply as to whether he admitted that the benefit of reduction in CST rate w.e,f. 15M 1.2017, had not been passed on to his recipients by way of commensurate reduction in prices and if so, to suo-moto determine the quantum thereof and indicate the same in his reply ta the notice as well as furnish all supporting documents, The Respondent Was also allowed to inspect the relied upon non-confidential evidence/information or any data Which formed the basis of the said notice between 21,05.2019 and 2305.2019, Which was however not availed of by the Respondent.
3. The DGAP has reported that the period covered by the current investigation was from 15.112017 to 3004.201 g.
4. The DGAP has also reported that in response to the notice dated 14.05 2019 and subsequent reminders, the Respondent has submitted his replies Vide his letters/e-mails dated 2307.2019, 01.102019, 0210.2019, 07.10.2019, 10, 102019,11,10.2019,16-02019, 18. 10.2019, 21-10.2019 and 22.10.2019. Vide the aforementioned e-mails/letters, the Respondent submitted the following documents/information:-
(a) Copies of GSTR-I Returns for the period July 2017 tn April 2019.
(b) copies of GSTR-3B Returns for the period July 2017 to April 2019
(c) Copies Of Electronic Credit Ledger for the period July 2017 to April 2019
(d) Price lists Of the products.
(e) Invoice-wise outward supply details or the period July 2017 to April 2019 for the Subway Outlets (Franchise code “613B? and “613830,
(f) Details of input tax credit availed by the Respondent for the Subway Outlets (Franchise Code “61382” and the period July 2017 to 14.11.2017,
(g) Sample invoices based on which ITC has been claimed.
5. The DGAP in his report has further reported that in addition to the above documents, the Respondent, interalia, made the following submissions;-
a. That he had 35 operational outlets at Terminal 2 of the Mumbai international Airport, out of which 16 outlets were awarded to him in Package 1; that out of his 35 outlets, two outlets were franchisees of Subway; that cut of the 18 outlets that were allocated to him in package 1, 9 outlets were at Level 3 and 9 outlets were at Level 4 of the Food court: that the Food court at Level 4 was also divided into 2 parts; that in the first part of that Food court he had 5 outlets and in the second part there were 4 outlets; that one of his Subway outlets was located in the Food Court at Level 4 where he was operating 4 restaurants; that he was receiving joint invoices for the LPG/Electricity/Miater expenses in respect of these 4 cutlets and for apportionment of the Input Tax Credit (ITC) amongst these 4 outlets including his Subway outlet, he was equally distributing ITC between these 4 outlets; that a joint invoice pertaining to rent of all his 18 outlets (including franchisees of Burger king/Pizza Hut/Punjab Grill operated by him) was being received and ITC of GST paid on rent for the Subway outlet was being apportioned by him on the basis of the ratio of its area to the total area of his 18 outlets.
b. His other Subway outlet was operating on a revenue-snaring basis with Mis Mumbai International Airport Limited (hereinafter referred to as the MALI where 28% of the revenue earned was being shared by him with Mis MIAL.
6. The DGAP has also reported that in terms of Rule 130 of the CGST Rules 2017, Respondent had also been informed by the DGAP vide notice dated 14,05.2019 that if any information/documents provided by him were confidential, a non‑ confidential summary of such information/documents could be furnished by him. However, the Respondent did not classify any of the inforrnation/documents provided by him as confidential in terms of Rule 130 of the Rules, ibid.
7. DGAP has also reported that based on a careful examination of the case records, including the reference from the Standing Committee on Anti-Profiteering, various replies of the Respondent and documents/evidence placed on record, it emerged that the Respondent had around 35 restaurant outlets on the same GST registration out of which two were Subway outlets and the inquiry conducted by the Joint Commissioner (AE). CGST & CX, Mumbai East was limited to the Subway outlets of the Respondent. The DGAP has further reported that he had not examined outward supplies made from the other outlets by the Respondent.
8. The DGAP has reported that the main issues for determination were whether the rate of GST on the service supplied by the Respondent was reduced from 18% to 5% w.e.f. 15.11.2017 and if so, whether the benefit of such reduction in the rate of GST had been commensurately passed on by the Respondent to his recipients, in terms of Section 171 of the CGST Act, 2017.
9.The DGAP has further reported that the GSA` rate on the restaurant service had indeed been reduced from 18% to 5% vii.el 1511.2017 along with the condition that no ITC on the goods and services used in supplying the service would be available to the Respondent vide Notification No. 46/2017- Central Tax (Rate) dated 14.11.2017. Since the present case was a case of reduction in the rate of tax, it was important to examine the provisions of Section 171 of the CGST Act, 2017 to ascertain whether the present case was a case of profiteering or not. Section 171(1) reads as follows:-
“Any rethiction in rate of tax on any supply of goods or „services or the benefit of ITC .9itraiir be passed on to The recipient by way of commensurate reduction in prices.” Thus, the legal requirement of the above provision was abundantly clear that in the event of a benefit of ITC or reduction in the rate of tax: there must follow a commensurate reduction in the prices of the goods or services being supplied by a registered person and that the final price charged on each supply had to be reduced commensurately with the extent of benefit and that there was no other legally to mode of passing on such benefit of ITC to the
recipients/consurners.
10. The IDGAP has reported that the Respondent was sealing with a total of 136 items while supplying restaurant services through his Subway outlets before and after 15.11,2017; that the details relating to 32 of the 136 products supplied by him in the pre–rate
reduction period, i.e, before 15,11.2017, were not provided by the Respondent; that as per the details submitted by the Respondent, DGAP has compared the average selling prices for the period from 01.10.2017 to 14.11.2017 with the prices post rate reduction i.e. w.e.f. 15.11.2017 and it was observed that the Respondent had maintained pre rate reduction base prices of 9 items, 1 item which was sold pre rate reduction was not sold post rate reduction whereas the base prices of 21 items were either
increased or GST @18% was charged for some time even after rate reduction leading to a net higher cum-tax price incidence on the consumers_ As per the data submitted by the Respondent, it was revealed that the Respondent has charged a lower GST rate of 5% on the increased base prices on some of the other items, where earlier the tax amount was computed @18% before 15.11.2017 and @5% w,e.f. 15,11.2017 Hence, because of the increase in base prices, the cum-tax paid by the customers was not reduced commensurately for 94 items despite rate reduction. Therefore, the only remaining point for determination was whether the increase in base price was solely on account of denial of ITC.
11. Further, the DIP has intimated that the assessment of the impact of denial of ITC, which was an uncontested fact, required determination of the ITC in respect of “restaurant service”, as a percentage of the taxable turnover from the outward supply of “products”, during the pre-rate reduction period. For instance, if the ITC in respect of restaurant service was 10% c’ me taxable turnover of a registrant till 14.11.2017 (which became unavailable to him w,e.f. 15.11.2017) and if the increase in the base prices w.e,f, 15.11.2017 was less than 10%, then this would not be a case of profiteering. However, if in the same example, the increase in the base prices w.e.f. 15.11.2017, was by a margin of 14%, the extent of profiteering would he 14% – 10% 4%. of the turnover. In the instant case, profiteering was computed in the same manner as per the above example by taking into consideration the period from 01.07,2017 to 31.10.2017 and not up to 1411.2017 due to the following reasons:‑
a) There was no reversal of ITC on the closing stock of input and capital goods as on 14.11.2017 by the Respondent, which was required as per the provisions of Section 17 of the CGST Act 2017 read with Rule 42 and 43 of the Rules.
b) The invoices, on which ITC was availed during the month of November 2017 were related to the charges of Rent , for the whole month whereas ITC was not available to the Respondent after 1411.2017.
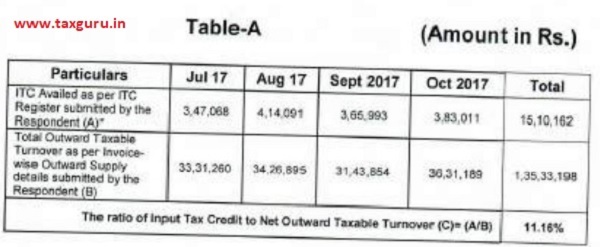
12 The DGAP in his report has further intimated that the ratio of ITC to the Net Taxable Turnover has been taken as the basis for determining the impact of denial of ITC that was available till 14.11.2017. On verification of the records of the Respondent, it was revealed that rrc. amounting to Rs. 15,10..1621- was available during the period from July 2017 to October 2017 which worked out to be 11.16% of his Net Taxable Turnover from the restaurant service supplies amounting to Rs. 1,35.3311981- during the same period, Further, with effect from 15.11.2017, the rate of tax on restaurant service was reduced from 18% to 5% and no ITC was available to the Respondent. A summary of the computation of the ratio of ITC to the taxable turnover as furnished by the DGAP is at Table-A below:-
13. The DGAP has also submitted that the analysis of the details of item-wise outward taxable supplies made during the post-rate reduction period (from 15.11.2017 to 31.04.2019) revealed that the base prices of the different items supplied by the Respondent had been increased by the Respondent, presumably, to offset denial of ITC, The pre and post rate reduction prices of the items sold by the Respondent during the period from 01.07.2017 to 14,11.2017 (Pre-GST rate reduction: 1 and from 11.2017 to 31.03.2019 (Post-GST rate reduction) were compared and it was found that the Respondent had increased the base prices of the products supplied by him by more than what was required to offset the impact of denial of ITC In respect of items sold during the same period and hence the commensurate benefit of reduction in the rate of tax from 18% to 5% had not been passed on.
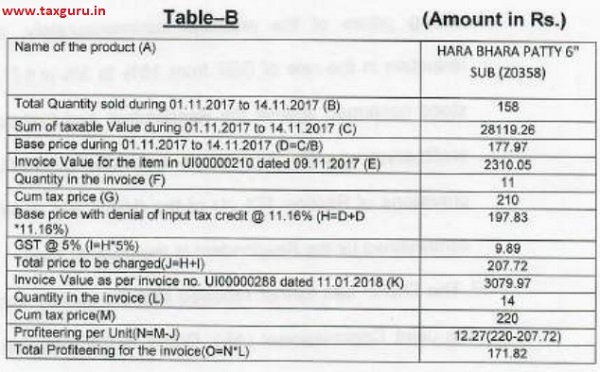
14. The DGAP has further stated that the next step was to compute the amount of profiteering in this It was pertinent that as a principle, only those items, where the increase in base prices was more than what was required to offset the impact of denial of ITC, were considered and the calculation was carried out following the above principle, The extent of profiteering was worked out as per the procedure mentioned in Table-B below:-
15. The DGAP has also claimed that based on the aforesaid pre and post rate reduction prices of the products; the impact of denial of ITC; and the details of outward supplies (other than zero-rated, nil rated and exempted supplies) during the period 15.11.2017 to 31.03.2019 (as per the product-wise sales registers reconciled with the GSTR-1 and GSTR-3B Returns) the amount of net higher sale realization due to increase in the base prices of the service supplied after netting off the impact of denial of ITC or in other words, the profiteered amount worked out Rs. 61,67,097/- (including GST on the base profiteered amount) for the period of investigation, which is detailed in Annexure-15 of the DGAP’s report. It was also stated that the service had been supplied by the Respondent in the State of Maharashtra only.
16. The DGAP has concluded that the allegation of profiteering by way of either increasing the base prices of the products while maintaining the same selling prices or by way of not reducing the selling prices of the products commensurately, despite the reduction in the rate of GST from 18% to 5% w.e.f, 151 1.2017 stood confirmed against the Respondent and that the extent of profiteering was Rs. 61,67,097f- (inclusive of GST). Thus the provisions of Section 171 (1) of the CGST Act, 2017 had been contravened by the Respondent in the present case.
17, The DGAP has further reported that the inquiry conducted by the Joint Commissioner (AE), CGST & CX, Mumbai East was limited only to the Subway franchise of the Respondent (Franchisee Code “61382” and “61383”) and the outward supplies made by him out of his other outlets had not been examined.
18. The above Report of the DGAP was considered by this Authority and it was decided to hear the Respondent on 2011.2019. A notice dated 01,11.2019 was also issued to the Respondent asking him to reply why the Report dated 25.10.2019 furnished by the DGAP should not be accepted and his liability for profiteering under Section 171 of the CGST Act 2017 should not be fixed However. the Respondent did not appear for the hearing and sought adjournment vide his submissions dated 18.11.2019. Sh. Shashi Mathews, Advocate, and Sh. Abbisheic Boob, Advocate represented the Respondent
19. The Respondent vide his written submissions dated 24.12/019 stated.:-
a. That the said 2 outlets of the Respondent were operated under a franchise agreement with Ws Subway Systems India Ltd_ (Subway India) and each aspect of the operation of the said outlets was regulated by M/s Subway India The revision in prices of the products and Point of Sale was also regulated by M/s Subway India and the Respondent did not have any control over the revision of the prices. Any revisions In the prices of the products sold at the Subway outlets operated by the Respondent were duly reflected in the Point of Sale. A copy of the Agreement between the Respondent and M/s Subway India along with e-mail communications regarding the price revisions were attached as Annoxure-4 & 5 respectively.
b. That the 2 outlets of Subway operated by the Respondent had two categories of One, individual customers, who bought products as per the price stated in the Menu. Other, where various airlines operating from the rViurnbai International Airport, which had entered into written agreements with the Respondent for serving the customers of their airlines in cases where there was a flight delay. Similarly, the Respondent had entered into an agreement with M/s Mumbai International Airport Pvt. Ltd. (GVK) to cater to the employees of G. The prices for such combo were discounted prices and the prices charmed therein were the base pnces after reduction by appropriate discounts on the base prices.
c. That the CGST Act or the CGST Rules did not prescribe any methodology to compute profiteering The only requirement under Section 171 (1) of the CGST .Act was that the benefit of any tax rate reduction or benefit of ITC should be passed on to the recipient by way of a ‘commensurate !eduction la prices”. However, the statute did not prescribe any method of computation by which amount of profiteering could be computed. Further, in terms of Section 171 (3) of the CGST Act, it was provided that the Authority mshail exercise such powers and discharge such functions as may be prescribed. Section 2(87) of the CGIST defined the word ‘prescribed’ to mean as prescribed by the CGST Rules on recommendations of the GST Council. Therefore, the Authority could discharge only such functions and exercise such powers as were specifically mentioned in the CGST Rules.
d. That Rule 126 of the CGST Rules empowered this Authority to determine the methodology and procedure for determining whether any reduction in the rate of tax on supply of goods or services or benefit of ITC had been passed on by a registered person by way of commensurate reduction in prices. Flowerer, to date, neither the CGST Act nor the CGST Rules nor any other form of delegated legislation had prescribed any method of computation by which an amount of ‘profiteering’ could be computed_ Even this Authority under the Goods and Services Tax’ Methodology rid Procedure, 2018 which had been notified in terms of Rule 126 of the CGST Rules did not prescribe any specific ‘methodology to be adopted in the computation of profiteering.
e. That no guidelines whatsoever had been framed leaving the issue to the complete discretion of the lavestigating authority (i.e. the DGAP) who for the first time in his Report was devising a particular method by which it was seeking to determine an amount which was alleoedly profiteered. Given the absence of knowledge of the basis on which the IDGAP had to act, the Respondent was compelled to accept any procedure adopted by DGAP and the opportunity of full defence to the Respondent was also curtailed.
f. That the method adopted by the DGAP had no statutory sanction and could not be regarded as a mandatory prescription at all and in the absence of guidelines prescribed under Rule 126, the Respondent could not be held as being non-compliant with the requirements of Section 171 of the CAST Act. The Respondent has relied upon the judgments of the Hon’ble Supreme Court in the cases of CET v. B. C. Srinivasa Setty, 0981) 2 SCC 460, and CCE v. Larsen & Toubro Ltd., (2016) 1 SCC 170 in his support.
g. That the DGAP has been given absolute unfettered powers to derive any method or computation to arrive at the conclusion that an assessee has profiteered. The absence of a prescription which has statutory approval has led to the entire exercise and the present proceedings being discriminatory,
h, That the requirement of having a mechanism to compute ‘profiteering’ with proper checks and balances was also raised by the Advisor to the Chief Minister, Punjab as well as the Chief Economic Advisor in the 174h GST Council Meeting held on 18.06.2017.
i. The Respondent has also referred to the similar anti-profiteering provisions which existed in Australia and Malaysia. Australian Competition and Consumer Commission, which was the authority to regulate unreasonably high profits being earned by the assessees pursuant to the implementation of the GST laws in those countries has laid down guidelines to provide for the net dollar margin method and the price margin method The said methods provided for the fundamental principles for the determination of price variances and changes, Under the erstwhile Malaysian GST laws, mechanisms with formulas were provided under the Price Control and Anti-profiteering (Mechanism to Determine Unreasonably High Profits) Regulations, 2018. Under the said Regulation, any profit earned over and above the determined ‘Net Profit Margin’ was considered as an unreasonably high profit and the assessee therein was liable for penal action under the law.
j. That the prescription of methodology computation provisions by way of the CGST Rules was a necessary imperative as any business which was required to comply with the law ought to be aware of how the law was to be complied with. This was more so when the non-compliance of such a law led to severe adverse civil consequences and even penal proceedings were sought to be initiated based on such alleged non-compliance of the law_ In the absence of a prescribed methodology, there was an arbitrary exercise of the power by the DGAP without any jurisdiction.
k. That pricing of the products was a complex exercise and the products were usually not priced individually and in isolation at a unit level, In a free market, sever considerations such as those of demand and supp’y, fixed and variable costs, prices of raw materials, logistics. product range, product mix, suppliers position in the market, entity-level operational costs, market situation, inflation, consumer segment: etc. costs and benefits at an entity level, division level, and product category level were all influencers of any pricing decision. Typically, the cost of taxes was only one of the elements which determined the final price.
l. That the Respondent sold his products to various categories of customers viz. Individual Customers and Institutional Customers and while making such sales, the prices of the products depended on the category of each customer. Moreover, prices to an Individual Customer were always different than the prices to an institutional Customer (who was sold on negotiated prices, by giving appropriate discounts on the sale price). The same product might have different prices when sold to different categories of customers even though the base price was the same for each product at the outlet. While examining the matter for any alleged profiteering, the said factor should have been taken into account by the DAP and, therefore, the basis of the Report itself was flawed. The Respondent has relied upon the judgment of the Honble Supreme Court in the case of Basant Industries v. Asst. Collector of Customs. 1996 (81) ELT 195 (SC) wherein it was categorically noted that If is a matter of common knowledge that a price which is offered by a supplier to an old customer may be different from a price which the same supplier offers to a totally new customer.
m. That a unitary approach looking at tax rate alone was not possible and would invariably skew the analysis, if The fixation of prices being a commercial exercise. a business-minded approach was necessary to interpret the provisions of law, especially when the Legislature had not given any defined guidelines on how to compute profiteering. In this regard, the principle of `commercial expediency’ was well recognized by the Honble Supreme Court of India under which it had been hold that it was the businessman who had to decide how to conduct its business and it was not the domain of the tax authorities to sit in judgment on how the business was to be conducted. Reliance in this regard was placed on the decisions of the Flon1ble Supreme Court given in the cases of S.A. Builders Ltd. v. Cll. (Appeals) (2007) 1 SCC 781 and Hero Cycles (Pvt.) Ltd. v. CIT (2015) 16 SCC 359 where the principle of Commercial expediency’ had been reiterated.
n. That the approach to fix the ‘selling price’ commonly for each category of sales was not proper as it would skew the, analysis. This was more so as the discounts offered to Institutional Customers had not been considered while undertaking the computation of the alleged profiteering amount. The said factor had been completely ignored in the DGAP’s Report and hence, the present proceedings ought to be dropped on this around alone a That the Respondent was never allowed to present his own metlhodology as per which pricing’ of his products was arrived at and to explain the transactions entered into between him and his customers. The above manner of adjudication has deprived the Respondent with an opportunity to explain his case or give alternative data before issuance of the Report by the DGAP and the same was therefore violative of the principles of natural justice.
p. That it was a well-settled principle in law that granting an opportunity of hearing was an integral part of the principles of natural justice. he has relied upon the judgment of the Honible Supreme Colin passed in the case of Uharam pal Satyzi pal Ltd.. v. Eby. Corrimissioner of C. Ex. 2015 (320) ELT 3 (SC) wherein the i-lonible Supreme Court has observed that even in administrative actions, where the decision of the authority may result in civil consequences, a hearing before taking a decision was necessary_ Further, in the case of Escorts Farms Ltd. v. Commissioner (2004) 4 SCC 281, the Hon’ble Supreme Court has also held that ‘Right of howling to a necessary party is a vaivable right. Denial of such right is serious breach of statutory procedure and violation of rules of natural justice”. He has also relied upon the judgment of the Flonlble Delhi High Court in the case of CCE v. SG Engineers 2015 (22) ELT 204 (Del.) wherein it was held that where the order did riot notice the relevant facts, it was a cryptic order without any reasons and such an order was not sustainable for violation of principles of natural justice, The DGAP’s Report has been prepared without considering the relevant facts and without allowing the Respondent to present his methodology for passing on the benefit of rate reduction to its recipients. Accordingly, the entire proceedings were in contravention of the settled principle of audi alteram pa/turn and violation of principles of natural justice. Therefore, the Report of the D3AP was liable to be set aside on this ground itself.
q. That the bare extract of Section 171(11 of the CGST Act did not provide any guidance for initiation of anti-profiteering provisions on that account, Accordingly, It was necessary to refer to the definition of the term ‘profiteering’ as defined under various dictionaries, As per Black’s Law Dictionary, the term profiteering meant ‘taking advantage of unusual or exceptional circumstances to make excessive profits’. As per the Oxford Dictionary, the term profiteering meant ‘make or seek to make an excessive profit’. As per Advanced Law Lexicon, the term profiteering meant ‘to seek or obtain excessive profits’ or ‘the one who is given to making excessive profits. The act of profiteering occurred only in cases where an assessee had indulged in acts leading to ‘excessive profits’. However. in the facts of the present case, the Respondent had not earned any excessive profits and the Respondent had been suffering losses over the last 2 years. Further, in respect of the 2 outlets under investigation, on account of royalty payments, rent to GVK, payroll costs, raw material costs, and other overhead expenses, etc„ there has been no profit earned by the Respondent_ Thus. the anti-profiteering provisions did riot get triggered, and the DGAP’s report should be set aside on this ground alone.
r. The DGAP has taken the period from 01.07. 2017 to 31.10.2017 (i.e. 123 days) for computation of ITC ratio which has been denied consequent to the amendments made vide the Rate Amendment Notification. Further, the base prices considered for computation of alleged profiteering were computed for the period from 01.11 2017 to 14.11.2017 for for the month of October 2017 for products not sold in the above period). Based on the ITC ratio and the base prices, the alleged profiteering amount has been computed for the period from 15.11,2017 to 30.04,2019 (i.e. 532 days). The basis of said computation of alleged profiteering was completely arbitrary as the Respondent could riot be expected to retain the same selling prices over a period of over more than 17 months. Several factors affected the selling prices, including the inflation, increase in the cost of raw materials, rent revisions, cost of manpower, response to the pricing strategy adopted by the competitors, etc.
s. That this Authority in the case of Kumar Gandharv v. KRBL Ltd. (Case No. 03/2018), has itself accepted the fact that an increase in production costs was a valid consideration while determining the quantum of profiteering.
t. That the provisions of Section 171 of the CGST Act coupled with the Report of the DGAP having an investigation period of almost 1 and half year, sought to restrict the right of the Respondent to decide the prices of his products for a prolonged periled even in the normal course of his business, thereby acting as a price controlling authority, which -was completely in violation of the fundamental rights of the Respondent under Article 19(1)(g). of the Constitution of India. That the Respondent was in the business of providing food items which mostly comprised of vegetables and other products. The raw materials used by the Respondent for preparing the food items which were sold fresh in the outlets operated by it were mainly agricultural products such as onions, tomatoes, lettuce. etc These items were heavily linked to seasonal variations in terms of availability and price Accordingly, the Respondent in his usual course of business was entitled to increase the prices of his pro-ducts and has also, in fact, increased his prices.
u. That the investigation period adopted by the DGAP in the case of M/s NP Foods (Case No. 9/2018), M’s Hardcastle Restaurants Pvt. Ltd. (Case N’o. 1412018), Mls Jubilant Food Works Ltd. (Case No. 04/2019) were based on the same Rate Amendment Notification and pertained to restaurant service The manner of selection of different investigation periods by the DAP clearly showed a patently disconnected approach adopted by the DGAP in different investigations under the same Rate Amendment Notification and in respect of restaurant service itself. That the actions of the DGAP were wholly arbitrary in nature and thereby violating Article 14 of the Constitution of India and the concept of equality before the law.
v. That the alleged profiteering amount as computed by the DGAP majorly pertained to the year 2018 and 2019 which has been described in the table below:-






