
Reckitt Benckiser India Private Limited Vs Union of India & Ors (Delhi High Court)
The Delhi High Court has upheld the validity of the anti-profiteering provisions under the Goods and Services Tax (GST) law, marking a significant development in India’s taxation landscape.
The anti-profiteering provisions under the GST law were introduced to ensure that businesses pass on the benefits of tax rate reduction or input tax credit to the consumers. This is done by reducing prices proportionately. The aim is to prevent unjust enrichment at the expense of the consumer.
A petition was filed challenging the constitutional validity of these provisions. The petitioner argued that the provisions were vague and lacked clear guidelines, leading to arbitrary and discriminatory application.
The Delhi High Court dismissed the petition, upholding the validity of the anti-profiteering provisions. The court observed that the provisions were not vague and had sufficient guidelines for implementation. It further noted that the provisions were in line with the constitutional goal of ensuring social and economic justice.
The court also emphasized the role of the National Anti-Profiteering Authority (NAA) in ensuring compliance with these provisions. The NAA has been entrusted with the responsibility of ensuring that the benefits of tax reduction or input tax credit are passed on to the consumers.
This verdict has significant implications for businesses operating under the GST regime. It reinforces the obligation of businesses to pass on the benefits of tax reduction or input tax credit to the consumers. Businesses failing to comply with these provisions may face penalties.
The verdict also provides legal backing to the actions of the NAA. This is expected to strengthen the authority’s role in curbing profiteering practices.
The Delhi High Court’s decision to uphold the validity of the anti-profiteering provisions under the GST law is a welcome move. It reaffirms the government’s commitment to protect consumers’ interests and ensure fair pricing practices. Businesses must take note of this verdict and ensure compliance with the GST law.
FULL TEXT OF THE JUDGMENT/ORDER OF DELHI HIGH COURT
1. Present writ petitions have been filed challenging the constitutional validity of Section 171 of the Central Good and Services Tax Act, 2017 (for short ‘Act, 2017’) and Rules 122, 124, 126, 127, 129, 133 and 134 of the Central Good and Services Tax Rules, 2017 (for short ‘Rules, 2017’) as well as legality of the notices proposing imposition or orders imposing penalty issued by the National Anti-Profiteering Authority (‘NAA’) under Section 122 of the Act, 2017 read with Rule 133(3)(d) of the Rules, 2017 and the final orders passed by NAA, whereby the petitioners, who are companies running diverse businesses ranging from hospitality, Fast-Moving Consumer Goods (‘FMCG’) to real estate, have been directed in accordance with Section 171 of Act, 2017, to pass on the commensurate benefit of reduction in the rate of tax or the Input Tax Credit to its consumers / recipients along with interest.
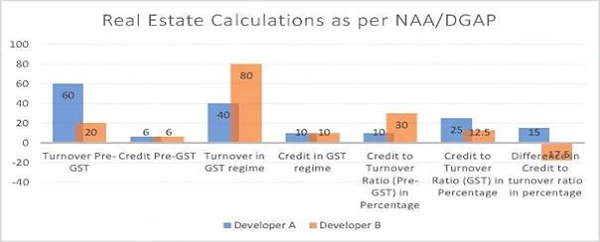
2. Learned counsel for the parties prayed that this Court may first decide the plea of constitutional validity of Section 171 of Act, 2017 as well as Rules 122, 124, 126, 127, 129, 133 and 134 of the Rules, 2017. They stated that only in the event this Court were to uphold the constitutional validity of the aforesaid Section and Rules, would the need to examine the matters on merits arise.
3. Accepting the suggestion of the learned counsel for the parties, this Court proceeded to hear the issue of constitutional validity of Section 171 of Act, 2017 as well as Rules 122, 124, 126, 127, 129, 133 and 134 of the Rules, 2017. The said provisions are reproduced hereinbelow:-
Section 171
“171. Anti-profiteering measure
(1) Any reduction in rate of tax on any supply of goods or services or the benefit of input tax credit shall be passed on to the recipient by way of commensurate reduction in prices.
(2) The Central Government may, on recommendations of the Council, by notification, constitute an Authority, or empower an existing Authority constituted under any law for the time being in force, to examine whether input tax credits availed by any registered person or the reduction in the tax rate have actually resulted in a commensurate reduction in the price of the goods or services or both supplied by him.
(3) The Authority referred to in sub-section (2) shall exercise such powers and discharge such functions as may be Authority.
[(3A) Where the Authority referred to in sub-section (2), after holding examination as required under the said sub-section comes to the conclusion that any registered person has profiteered under sub-section (1), such person shall be liable to pay penalty equivalent to ten per cent. of the amount so profiteered:
Provided that no penalty shall be leviable if the profiteered amount is deposited within thirty days of the date of passing of the order by the Authority.
Explanation. — For the purposes of this section, the expression “profiteered” shall mean the amount determined on account of not passing the benefit of reduction in rate of tax on supply of goods or services or both or the benefit of input tax credit to the recipient by way of commensurate reduction in the price of the goods or services or both.]
Rule 122
122.Constitution of the Authority.- The Authority shall consist of,-
(a) a Chairman who holds or has held a post equivalent in rank to a Secretary to the Government of India; and (b) four Technical Members who are or have been Commissioners of State tax or central tax [for at least one year] or have held an equivalent post under the existing law, to be nominated by the Council.
Rule 124
124. Appointment, salary, allowances and other terms and conditions of service of the Chairman and Members of the Authority:-
(1) The Chairman and Members of the Authority shall be appointed by the Central Government on the recommendations of a Selection Committee to be constituted for the purpose by the Council.
(2) The Chairman shall be paid a monthly salary of Rs. 2,25,000 (fixed) and other allowances and benefits as are admissible to a Central Government officer holding posts carrying the same pay: Provided that where a retired officer is selected as a Chairman, he shall be paid a monthly salary of Rs. 2,25,000 reduced by the amount of pension.
[(3) The Technical Member shall be paid a monthly salary and other allowances and benefits as are admissible to him when holding an equivalent Group ‘A’ post in the Government of India: Provided that where a retired officer is selected as a Technical Member, he shall be paid a monthly salary equal to his last drawn salary reduced by the amount of pension in accordance with the recommendations of the Seventh Pay Commission, as accepted by the Central Government.]
(4) The Chairman shall hold office for a term of two years from the date on which he enters upon his office, or until he attains the age of sixty- five years, whichever is earlier and shall be eligible for reappointment:
Provided that [a] person shall not be selected as the Chairman, if he has attained the age of sixty-two years. [Provided further that the Central Government with the approval of the Chairperson of the Council may terminate the appointment of the Chairman at any time.]
(5) The Technical Member of the Authority shall hold office for a term of two years from the date on which he enters upon his office, or until he attains the age of sixty-five years, whichever is earlier and shall be eligible for reappointment:
Provided that [a] person shall not be selected as a Technical Member if he has attained the age of sixty-two years. [Provided further that the Central Government with the approval of the Chairperson of the Council may terminate the appointment of the Technical Member at any time.]
Rule 126
126. Power to determine the methodology and procedure
The Authority may determine the methodology and procedure for determination as to whether the reduction in the rate of tax on the supply of goods or services or the benefit of input tax credit has been passed on by the registered person to the recipient by way of commensurate reduction in prices.
Rule 127
127. Duties of the Authority.
It shall be the duty of the Authority,-
(i) to determine whether any reduction in the rate of tax on any supply of goods or services or the benefit of input tax credit has been passed on to the recipient by way of commensurate reduction in prices;
(ii) to identify the registered person who has not passed on the benefit of reduction in the rate of tax on supply of goods or services or the benefit of input tax credit to the recipient by way of commensurate reduction in prices;
(iii) to order,–
(a) reduction in prices;
(b) return to the recipient, an amount equivalent to the amount not passed on by way of commensurate reduction in prices along with interest at the rate of eighteen percent. from the date of collection of the higher amount till the date of the return of such amount orrecovery of the amount not returned, as the case may be, in case the eligible person does not claim return of the amount or is not identifiable, and depositing the same in the Fund referred to in section 57;
(c) imposition of penalty as specified in the Act; and
(d) cancellation of registration under the Act.
[(iv) to furnish a performance report to the Council by the tenth [day] of the close of each quarter.]
Rule 129
129. Initiation and conduct of proceedings.-(1)Where the Standing Committee is satisfied that there is a prima-facie evidence to show that the supplier has not passed on the benefit of reduction in the rate of tax on the supply of goods or services or the benefit of input tax credit to the recipient by way of commensurate reduction in prices, it shall refer the matter to the Director General of [Anti-profiteering] for a detailed investigation.
(2) The Director General of [Anti-profiteering] shall conduct investigation and collect evidence necessary to determine whether the benefit of reduction in the rate of tax on any supply of goods or services or the benefit of input tax credit has been passed on to the recipient by way of commensurate reduction in
(3) The Director General of [Anti-profiteering] shall, before initiation of the investigation, issue a notice to the interested parties containing, inter alia, information on the following, namely:-
(a) the description of the goods or services in respect of which the proceedings have been initiated;
(b) summary of the statement of facts on which the allegations are based; and
(c) the time limit allowed to the interested parties and other persons who may have information related to the proceedings for furnishing their reply.
(4) The Director General of [Anti-profiteering] may also issue notices to such other persons as deemed fit for a fair enquiry into the matter.
(5) The Director General of [Anti-profiteering] shall make available the evidence presented to it by one interested party to the other interested parties, participating in the proceedings.
(6) The Director General of [Anti-profiteering] shall complete the investigation within a period of [six] months of the receipt of the reference from the Standing Committee or within such extended period not exceeding a further period of three months for reasons to be recorded in writing [as may be allowed by the Authority] and, upon completion of the investigation, furnish to the Authority, a report of its findings along with the relevant records.
Rule 133
133. Order of the Authority.
(1) The Authority shall, within a period of [six] months from the date of the receipt of the report from the Director General of [Anti-profiteering] determine whether a registered person has passed on the benefit of the reduction in the rate of tax on the supply of goods or services or the benefit of input tax credit to the recipient by way of commensurate reduction in prices.
(2) An opportunity of hearing shall be granted to the interested parties by the Authority where any request is received in writing from such interested parties.
[(2A) The Authority may seek the clarification, if any, from the Director General of Anti Profiteering on the report submitted under sub-rule (6) of rule 129 during the process of determination under sub-rule (1).]
[(3) Where the Authority determines that a registered person has not passed on the benefit of the reduction in the rate of tax on the supply of goods or services or the benefit of input tax credit to the recipient by way of commensurate reduction in prices, the Authority may order –
(a) reduction in prices;
(b) return to the recipient, an amount equivalent to the amount not passed on by way of commensurate reduction in prices along with interest at the rate of eighteen per cent. from the date of collection of the higher amount till the date of the return of such amount or recovery of the amount including interest not returned, as the case may be;
(c) the deposit of an amount equivalent to fifty per cent. of the amount determined under the above clause[along with interest at the rate of eighteen per cent. from the date of collection of the higher amount till the date of deposit of such amount] in the Fund constituted under section 57 and the remaining fifty per cent. of the amount in the Fund constituted under section 57 of the Goods and Services Tax Act, 2017 of the concerned State, where the eligible person does not claim return of the amount or is not identifiable;
(d) imposition of penalty as specified under the Act; and
(e) cancellation of registration under the Act.
Explanation: For the purpose of this sub-rule, the expression, “concerned State” means the State [or Union Territory] in respect of which the Authority passes an order.]
[(4) If the report of the Director General of [Anti-profiteering] referred to in sub-rule (6) of rule 129 recommends that there is contravention or even non-contravention of the provisions of section 171 or these rules, but the Authority is of the opinion that further investigation or inquiry is called for in the matter, it may, for reasons to be recorded in writing, refer the matter to the Director General of [Anti-profiteering] to cause further investigation or inquiry in accordance with the provisions of the Act and these rules.]
[(5) (a) Notwithstanding anything contained in sub-rule (4), where upon receipt of the report of the Director General of Anti-profiteering referred to in sub-rule (6) of rule 129, the Authority has reasons to believe that there has been contravention of the provisions of section 171 in respect of goods or services or both other than those covered in the said report, it may, for reasons to be recorded in writing, within the time limit specified in sub-rule (1), direct the Director General of Anti-profiteering to cause investigation or inquiry with regard to such other goods or services or both, in accordance with the provisions of the Act and these rules.
(b) The investigation or enquiry under clause (a) shall be deemed to be a new investigation or enquiry and all the provisions of rule 129 shall mutatis mutandis apply to such investigation or enquiry.]”
Rule 134
134. Decision to be taken by the majority.- (1) A minimum of three members of the Authority shall constitute quorum at its meetings.
(2) If the Members of the Authority differ in their opinion on any point, the point shall be decided according to the opinion of the majority of the members present and voting, and in the event of equality of votes, the Chairman shall have the second or casting vote.”
ARGUMENTS ON BEHALF OF THE PETITIONERS
4. Mr. P. Chidambaram, Mr. S. Ganesh, Mr. Tarun Gulati, Mr. Chinmoy Pradip Sharma and Mr.Pritesh Kapoor, learned Senior counsel as well as Mr. V. Lakshmikumaran, Mr. Monish Panda, Mr. Rohan Shah, Mr. Abhishek A. Rastogi, Mr. Tushar Jarwal, Mr. Sparsh Bhargava, Mr. Puneet Aggarwal, Mr. Sujit Ghosh, Mr. K. S. Suresh, Mr. Nikhil Gupta, Mr. Shashank Shekhar and Mr. Priyadarshi Manish, learned counsel addressed arguments on behalf of the petitioners.
5. Learned counsel for the petitioners submitted that Section 171(1) of the Act, 2017 and the Rules 126, 127 and 133 of the Rules, 2017 framed thereunder are unconstitutional as they are beyond the legislative competence of Parliament. They submitted that the impugned provisions do not fall within the law-making power of Parliament under Article 246A of the Constitution of India.
6. Some of the learned counsel for the petitioners submitted that the anti- profiteering provision, as provided under Section 171 of the Act, 2017, is in the nature of a tax or financial exaction. They submitted that a tax can be levied from a subject only if there is a specific and unequivocal provision in the parent statute authorising such an exaction. According to them, such a financial exaction cannot be made lawfully by a subordinate legislation, when there is no empowering provision in the parent statute. In support of their submissions, they relied on the decisions of the Supreme Court in Ahmedabad Urban Development Authority v. Sharakumar Jayantikumar Pasawala, (1992) 3 SCC 285 and V.S. Sugars v. Govt. of A.P., (1999) 4 SCC 192.
7. Learned counsel for the petitioners further submitted that the impugned Section and Rules suffer from vice of excessive delegation as they delegate essential legislative functions to the Additionally, they submitted that the impugned provisions are ambiguous, arbitrary, violative of Article 14 and confer excessive powers on NAA to determine profiteering as no guidelines and/or legislative policy for the exercise of such powers by the authority so constituted have been laid down in the statute. They submitted that the failure to provide clear statutory guidance for exercise of powers by NAA in the formulation of such methodology amounts to “delegation of essential legislative function” as these formulations were essential and therefore, the same should have been stipulated by the Legislature. They submitted that it is settled law that the legislative authority cannot be delegated under a statute without appropriate guidelines or safeguards. In support of their submissions, they relied on the judgment of the Supreme Court in Ramesh Birch vs. Union of India, 1989 Supp SCC 430.
8. They submitted that it is settled law that delegatus non potest delegare which essentially means that a delegatee cannot further delegate unless expressly or impliedly authorized. They contended that the Legislature vide Section 171 of the Act, 2017 delegated the authority to determine/prescribe powers and functions of NAA to the Executive i.e. the Government of India. They submitted that the Government of India by way of Rule 126 of the Rules, 2017, contrary to the legislative mandate contained in Section 171 of the Act, 2017, further delegated the power to NAA to determine the methodology and procedure for determining whether the reduction in taxes or the benefit of Input Tax Credit had been passed on to the recipients. They stated that even NAA did not issue any guidelines as to how to determine profiteering. In support of their submission, they relied on the judgment of the Supreme Court in Barium Chemicals Ltd. & Ors. v Company Law Board & [AIR 1967 SC 295].
9. They submitted that the term ‘commensurate’ is not defined in the Act, 2017 and the expression ‘profiteering’ in Section 171 is dependent upon the scope and meaning of the phrase ‘commensurate reduction in the price’. According to them, as a result of this circular reasoning, NAA had complete and unfettered discretion to determine the extent of profiteering. They pointed out that the definition of profiteering inserted by way of amendment (that came into force only on 01st January, 2020) is vague and uncertain as to how the amount of profiteering or commensurate reduction in price has to be determined and therefore, the same is ex facie arbitrary and violative of Articles 14 and 19(1)(g) of the Constitution of India. They pointed out that even NAA, in the orders passed by it, had not been consistent in its interpretation of the term “commensurate reduction”.
10. They stated that without stipulating the specifics of the methodology to be adopted to determine profiteering, the petitioners could not have been asked to reduce prices. They contrasted the lack of guidelines in Section 171 of the Act, 2017 with Section 9A of the Customs Tariff Act, 1975 which lays down the broad guidelines on the basis of which the extent of dumping and anti-dumping duty is to be quantified and Section 19(3) of the Competition Act, 2002, which lays down the factors to be taken into consideration while determining whether an agreement has an appreciable adverse effect. They stated that in the absence of any guidelines, NAA had acted arbitrarily as is evident from the varied approaches taken by it while adjudicating cases of entities belonging to the same industry and dealing with similar products.
11. Learned counsel for the petitioners emphasised that the formula used by the respondents, for instance, for real estate companies during the course of investigation/adjudication, had not been They stated that the methodology adopted by NAA and the Director General of Anti-Profiteering (‘DGAP’) to arrive at the profiteering amount of the real estate industry was generally based on the difference between the ratio of Input Tax Credit to turnover under the pre-Goods and Services Tax and post-Goods and Services Tax period. To drive home the point that the methodology adopted by the respondents was flawed, the learned counsel for the petitioners gave an illustration of the contrasting results one would get after calculating the amount profiteered/required to be passed on in case of two identical real estate projects being developed by Developers A & B with the only difference being the advance payment received by them prior to the Goods and Services Tax Regime. They stated that assuming that two Developers (A & B) commenced construction of the two identical projects (having hundred flats of rupees one crore each) in 2017 and the projects were executed at an identical pace with identical inputs and with Developer A receiving sixty per cent of the amount (total sale price of the project) as advance during the pre-Goods and Services Tax period, Developer B receiving only twenty per cent as advance during that period, with all other factors being identical (like the credit availed/available during the pre-Goods and Services Tax period), the credit to turnover ratio for the two projects would vary drastically depending on the time when the payments from the customers were received. According to the petitioners, if the methodology adopted by NAA /DGAP is to be accepted, Developer A would be required to pass on 15% benefit to the flat- buyers and Developer B who received 80% of the payment/amount post-Goods and Services Tax receive would be required to pass no benefit to the flat-buyers. A graphical representation of the same, as furnished by the petitioners, is as follows:
12. They stated that it is for this reason, the percentage of credit to turnover ratio (in Goods and Services Tax regime) had varied from 2% (in Vatika Limited, Case No. 64/2019) to 20.98% (in Emaar MGF Land Ltd, Case No. 26/2020) in the orders passed by NAA.
13. Learned counsel for the petitioners in Writ Petition 13657/2022 pointed out that DLF calculated the total savings on account of introduction of Goods and Services Tax for each project. He stated that the total savings/benefits were then divided by total area to arrive at the per square feet benefit to be passed on to each flat buyer. He stated that as a result the flat-buyers with equal area received equal benefit. In contrast to this, he pointed out that the NAA/DGAP calculated the benefit by comparison of ratios as explained above and then computed the profiteered amount as a percentage of consideration received from each flat-buyer in the Goods and Services Tax regime. Therefore, as per NAA/DGAP, similarly placed flat-buyers received inconsistent benefits. For the project Camellias, the benefits computed by both NAA/DGAP & DLF are tabulated below:






