
The assessing officer while embarking upon calculating expenditure on the exempt income in terms of the provision of section 14A have only mentioned his satisfaction, in literally manner , however has not given the detailed reasons and has merely mentioned that he is not satisfied with the explanation offered by the assessee. In our view, it is the duty of the assessing officer to record the satisfaction for not satisfied with the explanation given by the assessee with respect to not incurring any expenditure by the assessee in respect of the extent income. In the present case, the assessing officer has merely mentioned that he is not satisfied with the explanation, therefore, in our view, the assessing officer has recorded the satisfaction for the ‘compilation of Rule 8D. No specific format is provided under the act for recording the satisfaction. Assessee has failed to discharge his primary onus of proving nexus of interest free funds available at the time of making the investment that has yielded the interest free income, in our view, in the absence of discharge of initial onus the burden is not shifted to assessing officer to establish nexus between the interest bearing funds and the investment made by the assessee. As the assessing officer has recorded his dissatisfaction regarding the correctness of the claim of the assessee in respect of expenditure (Nil) which the assessee claimed to have been incurred in relation to the income which does not form part of the total income. After recording dissatisfaction, the assessing officer is left with no other option but to adopt the methodology provided in Rule 8D row with section 14A(2) of the Act. In the present case, the assessing officer has only applied 0.5% of the total income as expenditure. In our view, the assessing officer has rightly applied the Rule 8D and no error has been pointed out by the learned Authorized Representative on working out of the expenditure by applying the Rule 8D. In our view, the assessing officer has worked out the expenses after due application of the methodology, therefore, the ground raised by the assessee is required to be rejected.
Full Text of the ITAT Order is as follows:-
ORDER
Laliet Kumar, JM
These appeals by the assessee are directed against the order passed by the Commissioner (Appeals)-IV, Bangalore dated 2-4-2013 for the assessment year 2008-09.
2. The GE India Exports Private Limited (“GEIE” or “Appellant” or “Assessee” or “Company”), formerly known as GE Power Controls (India) Private Limited, is a subsidiary of GE Mauritius Infrastructure Holdings Ltd and is engaged in the business of provision of development and engineering design services (“software development”), engineering consultancy services and customer support services (in the nature of IT Enabled Services (“ITES”J). The company is eligible for deduction under Section 10A of the Income Tax Act, 1961 (“the Act”) in respect of its income from various units registered with the Software Technology Parks of India (“STPI”).
3. GEIE provides ITES in accordance with specific directions, guidelines and criteria established by the Associated Enterprise (“AE”). The customer support services include handling the queries of credit card customers of AE through the call center located at Hyderabad and providing other back end support to credit cardholders. The pricing for such services is done on the basis of actual cost plus mark-up. GEIE, through its 100% export oriented units, also provides software development services in accordance with the directions, guidelines and specifications provided by the AEs. Under this segment, GEIE also provides IT project management, IT infrastructure management, application management and other forms of support for IT operations to the AEs. The pricing for all the services is done on the basis of actual cost plus mark-up. Further, GEIE is characterized as captive service provider in respect of provision of ITES and software development services.
First we shall take up the appeal in IT(TP)A No.840/Bang/2013 for the assessment year 2008-09.
IT(TP)A No. 840/Bang/2013
4. The grounds raised by the assessee are as under:
The grounds mentioned herein below are without prejudice to each other.
1. That the order passed by the Commissioner (Appeals) – I, Bangalore [hereinafter referred to as ‘Commissioner (Appeals)’] under section 250 of the Income Tax Act, 1961 (‘the Act’) to the extent prejudicial to the Appellant, is perverse, erroneous on facts and bad in law.
2. That on the facts and circumstances of the case and in law, the learned Commissioner (Appeals) erred in upholding the order of the assessing officer (Ld. AO’) in disallowing an amount of Rs. 19,40,000 under section 14A of the Act, while computing the income of the Appellant.
2.1 Without prejudice to the above, even assuming but not admitting that the above amount of Rs. 19,40,000 is dis allowable under section 14A of the Act, the learned Commissioner (Appeals) erred in upholding the order of the learned assessing officer in not granting the relief under section 10A of the Act on the enhanced income.
That the Appellant craves leave to add to and / or to alter, amend, rescind, modify-, the grounds herein above or produce further documents before or at the time of hearing of this Appeal.
5. The only issue raised in this appeal is regarding dis allowance of Rs. 19,40,000 under section 14A of the Act not granting relief under section 10A of the Act on the enhanced income.
6. During the year under consideration, the assessee earned dividend income of Rs. 2,56,08,000. The said dividend income was earned on the investment of Rs. 3,88,000,000 made by the assessee alleged out of its own fund in the cumulative average investment of GE Industrial Pvt. Ltd. It was the case of the assessee that the assessee had not incurred any expenditure in earning such dividend income. The assessing officer had disallowed an amount of Rs. 19,40,000 considering the same as expenditure incurred in relation to exempt income and by applying the provision of section 14A row with Rule 8D of the Income Tax Rules. The assessing officer in the assessment order referred as under:–
Expenditure on exempt income under section 14A:
Further on verification of the details filed , it was observed that the assessee has received exempt income by way of dividend of Rs. 2,56,08,000 and has not debited any expenditure to earn the exempt income as required as per the provisions of the section 14A row with Rule 8D of the Income Tax Rules. During the course of assessment proceedings the assessee’s Authorized Representative was asked to furnish the details of expenditure attributable to earn exempt income. In response assessee’s Authorized Representative filed a letter date 24-10-2011 contending that section 14A is not applicable in the present case relying on various case laws. As I am not satisfied with the explanation offered by the assessee’s authorized representative, I proceed to bring to tax the expenditure on exempt income as follows:
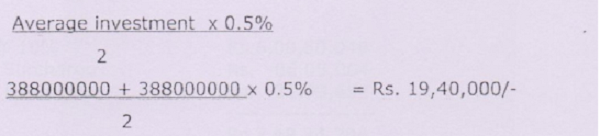
The expenditure on exempt income works out to Rs. 19,40,000 and the same is brought to tax.
The draft asst. order dated 8-12-2011 was forwarded to the assessee vide letter dated 8-12-2011. The assessee filed a letter dated 10-1-2012 stating that based on the clarification issued by the CBDT dated 20-1-2010 the assessee company does not intend to file objection against the draft assessment order before the Dispute Resolution Panel and requested this office to pass final assessment order.
7. Feeling aggrieved by the order, the assessee preferred an appeal before the Commissioner (Appeals). The learned Commissioner (Appeals) in paragraph 177 to 179 held as under.–
“177. 1 have carefully considered the appellant’s submissions. The AU has disallowed an amount of Rs. 19,40,000 as expenses attributable to the exempt income of R.S 29,40,000. The appellant contends that it had not incurred any expenditure in earning the exempt income and hence no dis allowance was warranted. Section 14A(3) provides that the AU shall determine the amount of expenditure incurred in relation to income which does not form part of the total income in accordance with the prescribed method, also in relation to a case where an assessee claims that no expenditure has been incurred by him in relation to income which does not form part of the total income. The formula prescribed in Rule 8D(2)(ii) shows that a dis allowance under section 14A can be made even where no expenditure is found to have been incurred for earning the exempt income.
178. 1do not subscribe to the view that since section 14A(3) was inserted with effect from 1-4-2007, it cannot be applied in relation to assessment year 2005-06. Since the assessment in this case was completed only on 30-1-2012, i.e., well after the amendment to section 14A came into operation, the AU was bound to follow the law as it existed at the time the assessment order was passed. Proviso to section 14A that the assessing officer is not empowered to reassess any income under section 147 or pass a rectification order under section 154 for any assessment year beginning on or before 1-4-2001. In the present case, the assessment was neither sought to be reopened under section 147, nor rectified under section 154, nor did the assessment relate to any assessment year prior to 1-4-2001.
179. The decision of the Honorable High Court of Karnataka in the case of Ltd. v. KIT (supra) was in relation to a dealer in shares and securities who had sold part of the shares it had purchased by availing an interest-free loan. The Honorable High Court was pleased to hold that when the assessee had not retained shares with the intention of earning dividend income and dividend income was incidental to his business of sale of shares which remained unsold by assessee, it could not be said that expenditure incurred in acquiring shares had to be apportioned to extent of dividend income and that should be disallowed under section 14A. It is clear that the facts and circumstances of CCI Ltd. were completely different from those of the present case where the appellant is neither a dealer in shares and securities, nor has it sold any shares. Thus, the ratio of the case cited by the appellant does not apply to the facts of its own case. “
8. Before us, the learned Authorized Representative has submitted that no expenses in relation with the earning of dividend income were incurred.
9. The learned Authorized Representative has submitted that the assessee has not incurred any expenditure, therefore, the provision of section 14A is not applicable. It is submitted that there should be proximate cause for dis allowance which is in relation to the tax exempt income. In the absence of proximate cause, the dis allowance under section 14A of the Act cannot be invoked. The learned Authorized Representative relied upon the judgment of CIT v. Karnataka State Industrial & Infrastructure Development Corpn., Ltd. (2016) 65 taxmann.com 295 to say that the recording of the satisfaction by the assessing officer is necessary before calculating the amount under Rule 8D. It is submitted that if the assessee is having interest free fund available then it is presumed that the assessee had made the investment from interest free eve if there is some borrowing of loan by the assessee.
10. We have heard rival contentions of the parties and perused the records. The assessing officer while embarking upon calculating expenditure on the exempt income in terms of the provision of section 14A have only mentioned his satisfaction, in literally manner , however has not given the detailed reasons and has merely mentioned that he is not satisfied with the explanation offered by the assessee. In our view, it is the duty of the assessing officer to record the satisfaction for not satisfied with the explanation given by the assessee with respect to not incurring any expenditure by the assessee in respect of the extent income. In the present case, the assessing officer has merely mentioned that he is not satisfied with the explanation, therefore, in our view, the assessing officer has recorded the satisfaction for the ‘compilation of Rule 8D. No specific format is provided under the act for recording the satisfaction. Assessee has failed to discharge his primary onus of proving nexus of interest free funds available at the time of making the investment that has yielded the interest free income, in our view, in the absence of discharge of initial onus the burden is not shifted to assessing officer to establish nexus between the interest bearing funds and the investment made by the assessee. As the assessing officer has recorded his dissatisfaction regarding the correctness of the claim of the assessee in respect of expenditure (Nil) which the assessee claimed to have been incurred in relation to the income which does not form part of the total income. After recording dissatisfaction, the assessing officer is left with no other option but to adopt the methodology provided in Rule 8D row with section 14A(2) of the Act. In the present case, the assessing officer has only applied 0.5% of the total income as expenditure. In our view, the assessing officer has rightly applied the Rule 8D and no error has been pointed out by the learned Authorized Representative on working out of the expenditure by applying the Rule 8D. In our view, the assessing officer has worked out the expenses after due application of the methodology, therefore, the ground raised by the assessee is required to be rejected.
Therefore, in the light of the above, this ground of the is dismissed.
11. The ground appeal of the assessee at 2.1 is as under:
“Without prejudice to the above, even assuming but not admitting that the above amount of Rs. 19,40,000 is dis allowance under section 14A a/the Act, the learned Commissioner (Appeals) erred in upholding the order a/the learned AD in not granting the relief under section 10A of the Act on the enhanced income.”
In this regard, the learned Authorized Representative has submitted that in case this Tribunal disallows the ground 2.1 and held that the section 14A is applicable for instant case then in such eventuality, the expenditure should be added back to the income of the undertaking and deduction under section 10A should be allowed on such enhanced income.
The Commissioner (Appeals) in paragraph 173 of the order records the submission of the assessee in the following manner:–
“Deduction under section 10A was allowed on profits earned by the appellant form of the business of its undertaking. Any adjustment made during the computation of income under the head profits and gains of business or profession increased the profit of the business of the undertaking which was then eligible for tax holiday benefits. The provisions of section 10A did not provide for any limitation the grant of tax holiday on any additions made. It was only the provisions of section 92C which provided for a limitation on grant of tax holiday under section 10A on adjustments made to ALP determined by assesses, implying that all the other adjustments made were eligible for tax holiday deductions. “
The learned Authorized Representative for the assessee further relied upon the judgment of Pune Bench of the Tribunal in the case of ITO v. Kalbhor Gawade Builders in ITA No.386/PN/2011, the decision of Hon’ble Bombay High Court held in the case of CIT v. Gem Plus Jewellery India Ltd., 330 ITR 175 and judgments of Hyderabad Bench in the case of Bartronics India Ltd. v. ACIT in ITA No. 2188 & 2189/Hyd/2011.
On the other hand, the learned Departmental Representative has submitted that the judgment relied upon by the learned Authorized Representative are not applicable to the facts and circumstances of the case. Further, it was contended that for the purposes of section 10A, the income which is derived by an undertaking from the export of article etc. allowable as deduction from the total income of the assessee. The judgment referred by the learned Authorized Representative viz., iNautix Technologies India (P) Ltd., was on different facts and in fact. The coordinate bench in the matter of iNautix Technologies India (P) Ltd., has relied upon the judgment of Bombay High Court in Gem Plus Jewellery India Ltd., (Supra) wherein it was held that the assessee was entitled to exemption under section 10A with reference to addition or dis allowance of various payments as the plain consequence of dis allowance and add back made by the assessing officer is increased in the business profit of the assessee.
12. We have considered the rival submissions and we find force in the submissions of the learned Authorized Representative of the assessee on this issue because if part of expenses claimed by the assessee against business income is considered as expenses incurred for earning tax free income and is disallowed under section 14A, the business income stands increased by that amount and only such increased business income should be considered for computing the amount of deduction under section 10A. Assessing officer is directed accordingly.
13. In the light of the above, the appeal of the assessee is partly allowed for statistical purposes.
IT(TP)A No. 1042/Bang/2013 (Revenue’s appeal)
14. The grounds raised by the Revenue are as under:
1. The order of the learned Commissioner (Appeals), in so far as it is prejudicial to the interest of revenue, is opposed lo law and the (acts and circumstances of the case.
2. The learned Commissioner (Appeals) has failed to appreciate that the different year ending filter applied by the IPO is necessary to exclude companies which do not have the same or comparable financial cycle as the tested party.
3. The learned Commissioner (Appeals) erred in excluding the comparable companies like Aditya Birl Mianacs. Coral Hubs Eclerx, Jindal Intellicom, Mold-Tex and Allse Technologies Ltd. on the basis of Abnormal Profit without defining what constitutes abnormal profit filter and how the same is determined.
4. The learned Commissioner (Appeals) erred in holding that M/s (ienesvs International Corporation Ltd. being functionally different, cannot be taken as comparable without appreciating the fact that he himself has held that services the being in the nature of ITFS services, it is not necessary for the IPO to go into the horizontal and vertical segments of the same sub segment.
5. The learned Commissioner (Appeals) erred in rejecting Genesys International Corporation Ltd as a comparable without identifying any extraordinary variable which would distinguish this company from the taxpayer in terms of functions performed assets used and risk undertaken i.e. quantitative and qualitative analysis.
6. The Commissioner (Appeals) erred in directing the assessing officer to recompute the deduction allowable us 10A of the Income Tax Act after reducing the communication expenses amounting to Rs. 22,95,328 from the total turnover also.
7. The learned Commissioner (Appeals) erred in not appreciating the fact that there is no provision in section 10A which requires the concerned expenses: which are required lo be reduced from the export turnover as per clause (iv) of the [Explanation to section 10A to be reduced from the total turnover also.
8. The learned Commissioner (Appeals) ought to have considered the fact that the jurisdictional High Court decision relied upon by him has not been accepted by the department and an SLP has been filed before Hon’ble Supreme Court
9. For these and such other grounds that may be urged al the time of hearing, it is humbly prayed that the order of the Commissioner (Appeals)be reversed and that of the assessing officer be restored.
10. The appellant craves leave to add to alter, to amend or delete any of the grounds that may be urged at the time of hearing of the appeal.
15. With the respect of ground No. 2, the learned Departmental Representative for the Revenue has submitted that the Commissioner (Appeals) has failed to appreciate that the different year ending filter applied by the TPO is necessary to exclude companies which do not have the same or comparable financial cycle as the tested party. The TPO has rightly excluded the companies which do not have the same or comparable financial cycle as that of the tested parties. On the other hand Authorized Representative for the Assessee submitted that companies even though having different financial year ending, were operating during the same period of time similar to the Assessee and were also facing similar business cycles, market and economic conditions. Therefore, in the absence of any evidence available to the contrary that there has been a significant impact on the margins due to change in different reporting/ accounting period, it would be incorrect to consider the different year filter for disregarding comparable companies.
16. This Tribunal has taken consistent View In number of judgments stating that comparable company which could not be rejected on the ground of functionality cannot be rejected on the ground that it is following the financial year from January to December (i.e., calendar year). Though a comparable company following a different financial year may not be generally taken for comparability analysis, however, if financial data is available for all the quarters including January to March and it is otherwise possible to determine the value of the transaction as well as the profitability during the corresponding period, then it suffices the comparability criteria. Because, ultimately the core point in comparability analysis is to benchmark the margin of a given period of a comparable uncontrolled transaction with controlled transaction. If the financials of the corresponding period is available then it cannot be rejected simply on the ground that it has a different financial year. Assuming that instead of financial year i.e. 1st April to 31st March, the comparable companies adopted the financial year from 1st January to 31st December and 3 months financials of the comparables are otherwise available in the public domain then in our view it can be considered as comparable as different reporting/ accounting period would be not effect FAR analysis by TPO or by assessee, as financial for the year under consideration are derivable by reconstructing it on the basis of information available in public domain however this is subject to reporting of extraordinary event In the said three months which has an effect on profitability, expenses and sale of the comparable, thus making the comparable unfit. Hence, this ground is decided against the Revenue.
17. Ground No. 3 is with respect to exclusion of following six companies on the basis of abnormal profit.






