
Ramesh Chandra Dethaliya Vs ITO (ITAT Chandigarh)
The ITAT, Indore Bench upheld penalty u/s 271A of ₹25,000 for non-maintenance of books of account, holding that opting for Vivad Se Vishwas Scheme, 2024 does not wipe out independent penalties not linked to quantum additions.
In this case, the assessee—a wholesale vegetable trader—had gross receipts of about ₹63.87 lakh, exceeding the threshold u/s 44AA/44AB, yet failed to maintain books. The AO levied penalty u/s 271A, which was affirmed by CIT(A). The assessee argued that since tax arrears were settled under VSV 2024, the penalty should abate.
The Tribunal rejected this plea, noting CBDT Circular No. 19/2024 clarifies that penalties not related to quantum (including 271A) are outside the scope of VSV and must be contested independently. Further, the assessee failed to show any reasonable cause for not maintaining books despite turnover crossing the statutory limit.
Accordingly, penalty u/s 271A was confirmed, and the appeal was dismissed
FULL TEXT OF THE ORDER OF ITAT CHANDIGARH
Feeling aggrieved by order of first appeal dated 30.06.2025 passed by learned Commissioner of Income-tax-NFAC, Delhi [“CIT(A)”] which in turn arises out of penalty-order dated 30.05.2018 passed by learned ITO, Shajapur [“AO”] u/s 271A of Income-tax Act, 1961 [“the Act”] for assessment-year [“AY”] 2010-11, the assessee has filed this appeal on following grounds:
“1. The Ld. CIT(A) NFAC has erred in imposing penalty u/s 271A of Rs. 25,000/- due to non maintenance of Books of Accounts.
2. The penalty levied of Rs. 25,000/- may please be deleted.
3. The assessee craves to amend, alter or delete any of the ground of appeal.
2. The assessee in present case is aggrieved by the penalty of Rs. 25,000/- u/s 271A imposed by AO and upheld by CIT(A) for non-maintenance of books of account.
3. We have heard the learned Representatives of both sides and perused the case record including the orders of lower authorities.
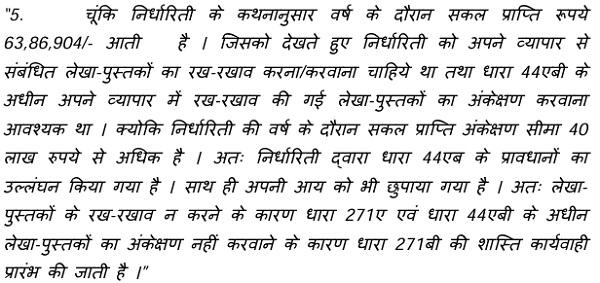
4. In Para 4 of assessment-order, the Ld. AO has noted as under:
Want to Read the Complete Judgment?
You have read the free case summary. Unlock the full judgment, the detailed judicial reasoning and the downloadable PDF, along with every other premium judgment on TaxGuru.
Already subscribed? Log in
One subscription covers the entire premium judgment library, not just this case.






