
Ramesh Chandra Dethaliya Vs ITO (ITAT Chandigarh)
The ITAT, Indore Bench upheld penalty u/s 271A of ₹25,000 for non-maintenance of books of account, holding that opting for Vivad Se Vishwas Scheme, 2024 does not wipe out independent penalties not linked to quantum additions.
In this case, the assessee—a wholesale vegetable trader—had gross receipts of about ₹63.87 lakh, exceeding the threshold u/s 44AA/44AB, yet failed to maintain books. The AO levied penalty u/s 271A, which was affirmed by CIT(A). The assessee argued that since tax arrears were settled under VSV 2024, the penalty should abate.
The Tribunal rejected this plea, noting CBDT Circular No. 19/2024 clarifies that penalties not related to quantum (including 271A) are outside the scope of VSV and must be contested independently. Further, the assessee failed to show any reasonable cause for not maintaining books despite turnover crossing the statutory limit.
Accordingly, penalty u/s 271A was confirmed, and the appeal was dismissed
FULL TEXT OF THE ORDER OF ITAT CHANDIGARH
Feeling aggrieved by order of first appeal dated 30.06.2025 passed by learned Commissioner of Income-tax-NFAC, Delhi [“CIT(A)”] which in turn arises out of penalty-order dated 30.05.2018 passed by learned ITO, Shajapur [“AO”] u/s 271A of Income-tax Act, 1961 [“the Act”] for assessment-year [“AY”] 2010-11, the assessee has filed this appeal on following grounds:
“1. The Ld. CIT(A) NFAC has erred in imposing penalty u/s 271A of Rs. 25,000/- due to non maintenance of Books of Accounts.
2. The penalty levied of Rs. 25,000/- may please be deleted.
3. The assessee craves to amend, alter or delete any of the ground of appeal.
2. The assessee in present case is aggrieved by the penalty of Rs. 25,000/- u/s 271A imposed by AO and upheld by CIT(A) for non-maintenance of books of account.
3. We have heard the learned Representatives of both sides and perused the case record including the orders of lower authorities.
4. In Para 4 of assessment-order, the Ld. AO has noted as under:
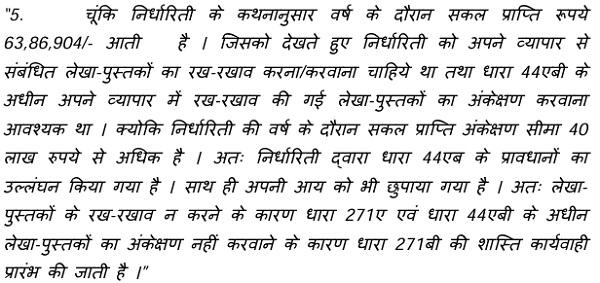
5. Thereafter, the AO has imposed a penalty of Rs. 25,000/- vide penalty-order dated 30.05.2018. During first appeal, the CIT(A) has passed following order upholding the action of AO:
“4. Decision:
4.1 I have considered the facts and circumstance of the case. It is found that the assessee vide its submission dated 20.01.2025 submitted Form No. 4 (under rule 7) which is an order for full and final settlement of tax areas under subsection (2) of section 92 read with section 93 of Finance Act (No. 2) of 2024 under the Direct Tax Vivad Se Vishwas Scheme, 2024. It is certified by the competent authority that surn of being Rs. 60,192/-has been paid by the declarant towards full and final settlement of tax areas determined in order No. 751672651131224 dated 13.12.2024 with respect to the appal ref. No. 1715090240 for disputed assessmnet order dated 30.05.2018 for AY 2010-11 as under:
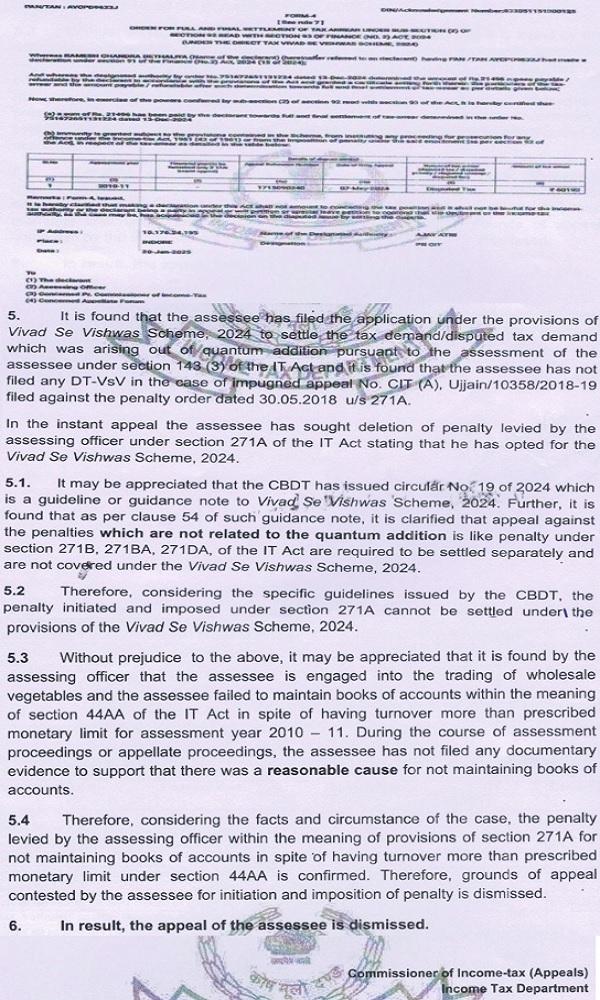
6. Before us, the Ld. AR for the assessee reiterated the submissions as were made by assessee before Ld. CIT(A). Upon careful consideration of the rival submissions and on perusal of the material available on record, we find that the Ld. CIT(A) has duly examined and adjudicated the issues raised before him by passing a reasoned and speaking order. The Ld. AR could not point out any factual or legal infirmity, perversity or error in the findings/conclusions recorded by the Ld. CIT(A). In absence of any contrary material brought on record, we see no justification to interfere with the impugned order. Accordingly, the order passed by the Ld. CIT(A) is upheld and the appeal filed by the assessee is dismissed.
7. Resultantly, this appeal is dismissed.
Order pronounced in open court on 03/02/2026








