Havells India Limited Vs PCIT (ITAT Delhi)
The Income Tax Appellate Tribunal (ITAT), Delhi, recently issued a landmark ruling in the case of Havells India Limited Vs Principal Commissioner of Income Tax (PCIT). The Tribunal set aside and quashed a revisional order from the PCIT, citing a failure to fulfill the twin conditions necessary for invoking revisional powers under Section 263 of the Income Tax Act, 1961.
In this case, Havells India Limited argued that the dual prerequisites for applying Section 263 were not satisfied. Section 263 empowers the Principal Commissioner to revise an order passed by an Assessing Officer if it is considered both erroneous and prejudicial to the interest of the revenue. A proposed disallowance of Rs. 1,15,00,000, despite altering the taxable income under normal circumstances, led to no change in the book profit under Section 115JB of the Act. Consequently, Havells India Limited contended no prejudice had been caused to the Revenue. The Revenue, however, found this explanation unverifiable and insisted on maintaining the revisional order. Considering the arguments, ITAT Delhi sided with Havells, finding no revenue benefit gained from the alleged error, and thus no prejudice caused to the Revenue. The ITAT set aside and quashed the revisional order from the PCIT, citing a failure to fulfill the twin conditions necessary for invoking revisional powers under Section 263.
This ruling has significant implications, shedding light on the critical need to fulfill the necessary conditions for invoking revisional powers under Section 263 of the Income Tax Act. It emphasizes the necessity for verifiable evidence in tax assessments and underlines the responsibility of the Revenue Department when applying their revisional powers.
FULL TEXT OF THE ORDER OF ITAT DELHI
The captioned appeal has been filed at the instance of the assessee against the revisional order of the ld. Principal Commissioner of Income Tax (Central), Delhi-2 (‘Pr.CIT’ in short) dated 30.03.2022 wherein order passed by the Assessing Officer (AO) under Section 143(3) of the Income Tax Act, 1961 (the Act) dated 31.12.2019 concerning AY 2018-19 was held to be erroneous in so far as prejudicial to the interest of the revenue within the meaning of Section 263 of the Act.
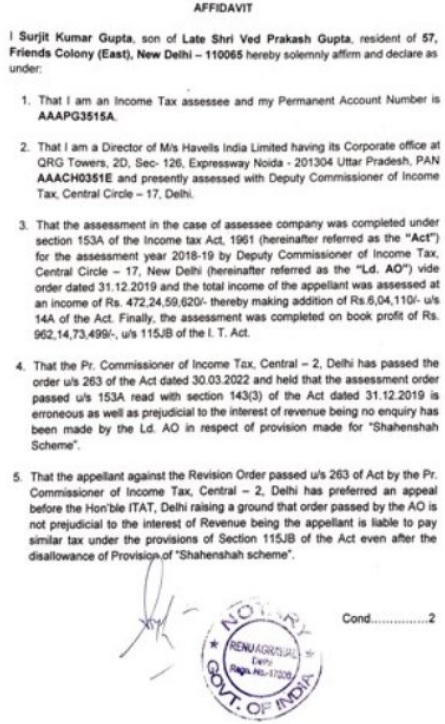
2. When the matter was called for hearing, the ld. counsel submitted that the twin condition for applicability of Section 263 is not fulfilled in the present case. Elaborating the stance, the assessee submitted that a disallowance of Rs.1,15,00,000/- was proposed to be made under Section 263 on account Shahenshah Scheme which has the result of modifying the taxable income under the normal provisions of the Income Tax Act. However, eventually there is no change in the book profit computed under Section 115JB of the Act by such disallowance. The assessee has been charged to taxation under the alternative Scheme under Section 115JB of the Act as per the Scheme of the Act. The ld. counsel contends that ultimate result of such adjustment will be lesser credit under MAT to this extent of Rs.39,79,920/- which the assessee is entitled to carry forward in the subsequent year for availing credit in accordance with law. However, in the instant case, the assessee has switched to Section 115BAA of the Act w.e.f. AY 2020-21 and as a result of exercising the option under Section 115BAA of the Act, the assessee is no longer entitled to avail the carry forward credit of MAT in the subsequent year. Consequently, in totality, no prejudice has resulted to the Revenue when the assessment upto AY 2020-21 is taken into account in so far as this issue is concerned. On being suggestd by the Bench, the ld. counsel has filed an affidavit dated 11.05.2023 of the assessee-company to the effect that it has not availed any tax benefit flowing under Section 115JB applied in the instant assessment year and thus no prejudice whatsoever has caused to the Revenue.
3. The ld. DR for the Revenue, on the other hand, states that the explanation offered on behalf of the assessee though plausible but is not verifiable at present. The ld. CIT-DR refers to paragraph 5.3 of the revisional order and claims that it is not correct to say that no prejudice has been caused to the Revenue by claiming an unsustainable provision. The ld. CIT-DR accordingly submitted that no interference with the revisional order is called for.
4. The contents of affidavit filed by the assessee-company is reproduced here under: