
Afzal Pasha Vs DCIT (ITAT Bangalore)
ITAT condoned delay of 130 days considering medical condition & held that genuine health issues constitute sufficient cause; appeal admitted on merits.
AO treated unsecured loans of ₹2.28 Cr as unexplained u/s 68 merely because lenders were from unorganised sector & did not file ITR/GST; CIT(A) confirmed addition without deeper verification. Assessee had furnished PAN & Aadhaar of lenders & loans were recorded in audited books — Tribunal held identity stands established & once primary evidence is given, initial onus stands discharged & burden shifts to AO. ITAT strongly observed AO cannot reject loans on assumptions about low income or lack of formal records; instead AO must use powers u/s 133(6) to verify lenders directly & allow cross-examination opportunity.Addition not finally deleted but matter remanded to AO for fresh verification in interest of justice; assessee directed to produce confirmations & cooperate in proceedings.
FULL TEXT OF THE ORDER OF ITAT BANGALORE
This Appeal at the instance of the assessee is directed against the order of ld. CIT(A)/NFAC dated 19/07/2024 vide Din and Order No: ITBA/NFAC/S/250/2024-25 passed u/s. 250 of the income Tax Act, 1961 (in short “the act”) for the AY 2018-19.
2. The assessee has raised the following Grounds of appeal:-
A. GENERAL GROUNDS:
1. The order dated 19 July 2024 passed by the learned Commissioner of Income-tax (Appeals), National Faceless Appeal Centre, Delhi [“CIT(A)”] under section 250 of the Income-tax Act, 1961 (“Act”) dismissing the appeal of the Appellant and upholding the addition made by the Ld. Assessing Officer under section 68 of the Act, is contrary to law and facts of the case and is passed in contravention of principles of natural justice.
2. The CIT(A) and Ld AO ought to have not acted mechanically and have not objectively evaluated the merits of the case.
B. GROUNDS ON MERITS:
3. The CIT(A) and Ld. AO erred in making addition of Rs.2,28,90,059/-treating the unsecured loans received by the Appellant as unexplained cash credits under section 68 of the Act.
4. The CIT(A) and Ld. AO erred in not appreciating that the Appellant had provided sufficient documentation and evidence to substantiate the identity, creditworthiness, and genuineness of the transactions and the money lender.
5. The CIT(A) and Ld. AO erred in not appreciating that the.Appellant was not legally required to prove the “source of the source” in respect of the unsecured loans.
6. The CIT(A) and Ld. AO erred in not exercising powers under section 122c61, of the Act to call for details from the money lenders to verify the genuineness of the transaction and the credit worthiness of the lenders when the Appellant had submitted details pertaining to the identity of the lenders including the PAN number, Aadhar number, GSTN number, addresses, mobile number and email address.
7. The CIT(A) and Ld. AO have erred in not providing the benefit of peak credit to the Appellant.
C. CONSEQUENTIAL GROUNDS:
8. The CIT(A) and Ld. AO erred in computing tax at higher rates under section 115BBE of the Act.
9. The CIT(A) and Ld. AO have erred in levying interest under sections 234A, 234B, and 234C of the Act.
Each of the above grounds are independent and without prejudice to the other ground of appeal preferred by the Appellant.
The Appellant reserves the right to further add, alter or amend each one of the above grounds of appeal
3. As noted by the Registry, there is a delay of 130 days in filing the appeal before this Tribunal. Before us, the ld. A.R. of the assessee drew our attention to an affidavit dated 6.2.2025 stating therein the cause for delay, which are reproduced below for ease of reference and convenience:
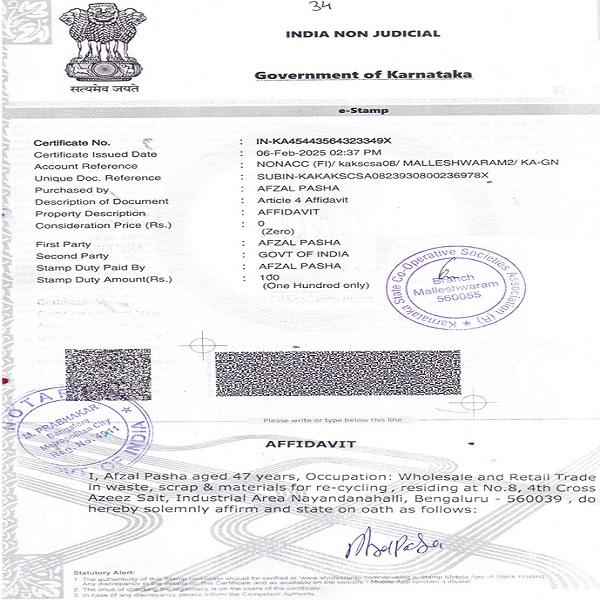
1. I am the Appellant in the present matter and I am fully acquainted with the facts of the case. I am competent to swear to this affidavit.
2. I respectfully submit that the present appeal is being filed before this Hon’ble Tribunal against the order 19.07.2024 passed by the CorNmissioner of Income-tax (Appeals) [“CIT(A)”], NFAC under section 250 of the Income-tax Act, 1961 (“Act”).
3. It is submitted that the appeal before this Hon’ble Tribunal ought to have been filed within 60 days from the date of the CIT(A) order i.e., on or before 17.09.2024. There is however delay in filing the present appeal for the reasons stated below follows:
a. I was suffering from severe back pain and consulted my doctor in the month of June 2024. Upon visiting the doctor, I was informed that I had a disc dislocation, which required me to take bed rest for 6 to 8 months. Additionally, I was suffering from gallbladder stones, for which I was receiving treatment. Due to these medical conditions, I was confined to home and could not ascertain the status of the appeal filed before the CIT(A). A copy of the medical certificate is attached as Annexure:- A
b. The order of the CIT(A) was passed on 19.07.2024 and was uploaded on the efiling portal on the same day however, I was not aware of the same and came to know of the dismissal of the appeal only when I made enquiry with my tax consultant in the last week of December 2024;
c. I thereafter met my tax consultant in the first week of January 2025 and was given to understand that an appeal ought to have been filed before this Hon’ble Tribunal within 60 days from the date of the CIT(A) order and since I had approached the tax consultant belatedly, I was informed that the time limit for filing the appeal had lapsed;
d. I was thereafter referred to the office of Mr. B.S. Balachandran, Advocate whom I met on 22.01.2025 and entrusted the case to him for drafting the appeal to be filed before Your Honours.
e. Thiappeal is filed today with a delay of 11-13
4. I respectfully submit that the delay in filing the, appeal was entirely due td the fact that I was not aware of the disposal of the appeal, and not due to any negligence or wilful disregard of the prescribed timeline. As soon as I was became aware of the dismissal of the appeal, I have taken all necessary steps to file the appeal at the earliest possible opportunity.
5. I kindly request that this Hon’ble Tribunal may be pleased to condone the delay of 143 days in filing the appeal, as the delay was neither intentional or deliberate, and I have made every effort to ensure that the appeal is filed as soon as possible.
6. I humbly pray that this Hon’ble Tribunal may kindly condone the delay of 1113,. days and permit the appeal to be heard on its merits in the interest of equity and justice, and for this I will remain forever grateful to Your Honours.
VERIFICATION
I, Afzal Pasha S/o, Kaleemulla do hereby state that the contents of para 1 to 6 of this affidavit and I confirm that what is stated above is true and correct to the best of my knowledge, information and belief.
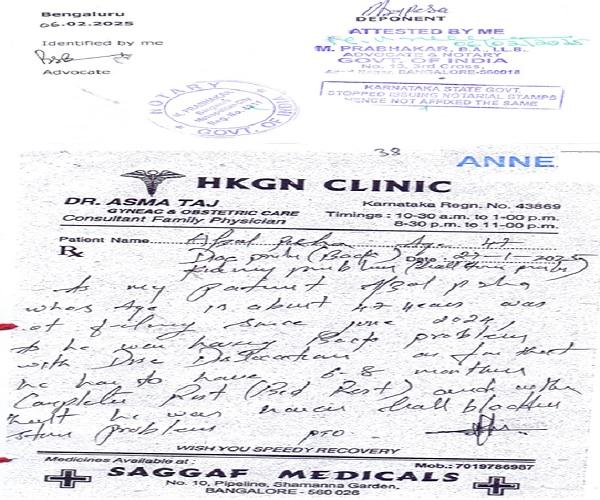
3.1 On going through the above affidavit, we take note of the fact that due to the health issues, the assessee could not file the appeal within the prescribed period. The assessee has also produced the medical certificate dated 27.1.2025 in support of his claim.
3.2 Perused the record and having heard ld. Counsel for the assessee as well as the ld. D.R., it is perceived that the explanation offered in the affidavit dated02/02/2025 is plausible and sufficient cause being shown by the assessee, which prevented him from filing the appeal within the prescribed period and accordingly, we inclined to condone the delay and admit the appeal for adjudication on merits.
4. Now the brief facts of the case are that the assessee is into the business of wholesale and retain trade in waste, scrap and materials for recycling. The assessee filed his return of income for the assessment year 2018-19 on 31.10.2018 by declaring total income of Rs.62,39,520/-. Subsequently, the case of the assessee was selected for limited scrutiny assessment under CASS on the issue of “unsecured loans”. Accordingly, notices u/s 143(2) & 142(1) of the Act were issued from time to time. During the course of assessment proceedings, the AO as per the unsecured loan details submitted in serial no.31(a) of Form 3CD i.e. Tax Audit Report noticed that the assessee had taken substantial unsecured loans from different persons who have not filed their returns of income. During the year under consideration, the assessee has taken total unsecured loans of Rs.2,41,50,000/-. Out of this, an amount of Rs.39,99,941/- was taken from Mr. Ajaz Baig and an amount of Rs.27,40,000/- has been shown as paid back and is shown as closing balance of Rs.12,59,941/-. The assessee had submitted the details in respect of all unsecured loans taken by him during the year along with copies of PAN & Aadhar cards of the lenders. However, the assessee could not submit the ITR copies of the lenders to prove the creditworthiness of the lender parties. Further, the AO also noticed from the audit report that these unsecured loans have been accepted other than mode of DD/Cheques or ECS. Mr. Ajaz Baig, however, submitted the documentary evidences to prove the identity, creditworthiness of the lender and genuineness of the transactions. However, in respect of balance amount of Rs.2,28,90,059/- of unsecured loans, the assessee merely submitted the PAN & Aadhar copy of the lenders only and submitted that other parties are small managing their business from meagre capital. The AO also noticed that all other parties hail from unorganized sector and they do not have also GST registration and income tax return and thus, the AO held that as the assessee could not discharge his onus to prove that the unsecured loans are genuine transactions and therefore, the amount of Rs.2,28,90,059/-was treated as unexplained cash credit u/s 68 of the Act r.w.s. 1115BEE of the Act. The AO completed the assessment proceedings u/s 143(3) r.w.s. 144B of the Act on a total assessed income of Rs.2,90,69,580/-
5. Aggrieved by the order of AO passed u/s 143(3) of the Act dated 4.5.2021, the assessee preferred an appeal before the ld. CIT(A)/NFAC.
6. The ld. CIT(A)/NFAC dismissed the appeal of the assessee by holding that assessee has failed to satisfactorily explain the nature and source of impugned credits and the same constitute undisclosed and unexplained income of the assessee from undisclosed sources and accordingly addition of Rs.2,28,90,059/- as made by the AO was confirmed.
7. Again, aggrieved by the order of ld. CIT(A)/NFAC, the assessee has filed the present appeal before this Tribunal.
8. Before us, the ld. A.R. of the assessee vehemently submitted that the assessee had produced PAN card as well as Aadhar card of the lenders land thus proved the identity of the loan creditors was established beyond doubt. Further, the ld. A.R. of the assessee submitted that the loan was taken for the purpose of the business and also the books of accounts were audited by the Chartered Accountant. Further, with regard to Mr. Ajaz Baig, the assessee had established the identity, creditworthiness as well as genuineness of the transactions as observed by the AO. However, in case of the balance loan creditors, the AO should have given opportunity to cross-examining the loan creditors and should have given opportunity to produce the documents to substantiate the claim of the assessee. The ld. A.R. of the assessee prayed that one more opportunity may be granted before the AO to substantiate his claim of loan creditors.
9. The ld. D.R. on the other hand supported the orders of the authorities below and vehemently submitted that in respect of balance amount of Rs.2,28,90,059/- of unsecured loans, the assessee could not prove the creditworthiness of the lenders by producing the I. Tax returns & GST returns along with the financials and genuineness of the transactions and accordingly, both the authorities below have rightly added the same u/s 68 of the Act as unexplained cash credits.
10. We have heard the rival submissions and perused the materials available on record. It is an undisputed fact that the case was selected for limited scrutiny under CASS to examine “unsecured loans”. It is also an undisputed fact that during the course of assessment proceedings, the assessee had submitted the details in respect of all unsecured loans taken by him during the year along with copies of PAN & Aadhar cards. Therefore, the identity of the loan creditors were established by the assessee. We also take note of the fact that all these unsecured loans were duly recorded in the books of accounts of the assessee and duly audited by the CA who had also reported the same in his Audit Report. The AO had also not rejected the books of accounts, however in the absence of creditworthiness of the lenders, added the same as unexplained cash credit u/s 68 of the Act. We are of the considered opinion that the prima facie the AO instead of imagining that the loan creditors having below taxable income could hardly save and lend out, should have given opportunity to the assessee to cross examine the loan creditors. Once the primary details in respect of loan creditors were submitted by the assessee, the onus shift upon the AO to disprove that the claim of the assessee is not correct. Undisputedly, the AO in his assessment order satisfied with the identity, creditworthiness as well as genuineness of the transactions in respect of loan creditors Mr. Ajaz Baig. In respect of balance creditors, the assessee had submitted the PAN & Aadhar card copies of the lenders and submitted that all other parties are small and managing their business from meagre capital. The AO instead of straightway disbelieving the contention of the assessee should have called for information & evidences from the lenders directly by issuing notice u/s 133(6) of the Act to them. The AO has enough power to call for those loan creditors along with documents and satisfy himself about the creditworthiness and genuineness of the transactions instead of outrightly rejecting the claim of the assessee that too without any adverse material on record. This being so, in the interest of justice and fair play and as requested by the ld. A.R. of the assessee, we deem it fit and proper to remit this limited issue to the file of AO for fresh examination in accordance with law. Needless to say, a reasonable opportunity of being heard must be granted to the assessee. The assessee is also directed to cooperate with the proceedings and produce all the relevant documents/records/confirmation of the loan creditors as claimed to have produced before the ld. CIT(A)/NFAC. It is ordered accordingly.
11. In the result, appeal filed by the assessee is partly allowed for statistical purposes.
Order pronounced in the open court on 9th Feb, 2026







