
Ajay Kumar Vs Pivotal Infrastructure Pvt Ltd. (NAA)
Facts of the Case:
The brief facts of the case are that vide their applications dated 09.10.2018 and 16.12.2019 filed before the Standing Committee on Anti-profiteering under Rule 128 (1) of the CGST Rules, 2017, the Applicant No. 1 and 2 had alleged profiteering by the Respondent in respect of purchase of Flats in his “Paradise” project located in Sector-62, Gurgaon. The above Applicants had also alleged that the Respondent had not passed on the benefit of Input Tax Credit (ITC) availed by him by way of commensurate reduction in considered by the Standing Committee on Anti-profiteering, in its meeting held on 13th December, 2018, wherein it was decided to forward the same to the DGAP to conduct detailed investigation in to the complaint according to Rule 129 (1) of the CGST Rules, 2017. The second application was considered by the Standing Committee on Anti-profiteering, in its meeting held on 11th March, 2018, wherein it was also decided to forward the same to the DGAP to conduct detailed investigation.
Held by NAA:
NAA observe that the Respondent, vide his submissions dated 06.09.2019, has contended that he has already passed on benefit of Rs. 2,18,87,807/- ( Rs. 81,82,783/- in March, 2019 and Rs. 1,37,05,024/- in August, 2019) to his home buyers during the period from 01.07.2017 to 31.08.2019. As evidence, he has submitted List of all his home buyers mentioning the amount of ITC benefit passed on to each of them, Customer-wise ledgers in respect of the home buyers which mention entry/entries indicating “GST benefit pass on to Home buyers” and has also submitted sample acknowledgement letters from his home buyers in support of his having passed on the benefit of ITC to them in terms of Section 171 of CGST Act. We also find that perusal of Table-D of the DGAP Report dated 19.06.2019 suggests an amount of Rs. 81,82,783/- has been claimed to have been passed on by the Respondent to his home buyers on account of ITC benefit. However, it is also clear from Table-D of the DGAP Report and claim of the Respondent of having passed on the benefit of Rs. 81,82,783/-, has not been verified at any stage by the DGAP. Further, the claim made by the Respondent during the hearings held before this Authority of having passed on another tranche of benefit of ITC to his home buyers, taking the total ITC benefit passed on to Rs. 2,18,87,807/-, also needs to be verified by the DGAP. Accordingly the DGAP is directed to further verify the total amount of ITC benefit claimed to have been passed on to his home buyers by the Respondent till date, as per the provisions of Rule 133 (4) of the above Rules and submit’ his Report clearly mentioning the verified amount of benefit passed on by the Respondent to his home buyers and the balance amount still to be passed on to each of the home buyers within a period of two months of this Order.
FULL TEXT OF ORDER OF NATIONAL ANTI-PROFITEERING AUTHORITY
1. The present Report dated 19.06.2019 has been received from the Applicant No. 3 i.e. the Director General of Anti-Profiteering (DGAP) after detailed investigation under Rule 129 (6) of the Central Goods & Service Tax (CGST) Rules, 2017. The brief facts of the case are that vide their applications dated 09.10.2018 and 16.12.2019 filed before the Standing Committee on Anti-profiteering under Rule 128 (1) of the CGST Rules, 2017, the Applicant No. 1 and 2 had alleged profiteering by the Respondent in respect of purchase of Flats in his “Paradise” project located in Sector-62, Gurgaon. The above Applicants had also alleged that the Respondent had not passed on the benefit of Input Tax Credit (ITC) availed by him by way of commensurate reduction in considered by the Standing Committee on Anti-profiteering, in its meeting held on 13th December, 2018, wherein it was decided to forward the same to the DGAP to conduct detailed investigation in to the complaint according to Rule 129 (1) of the CGST Rules, 2017. The second application was considered by the Standing Committee on Anti-profiteering, in its meeting held on 11th March, 2018, wherein it was also decided to forward the same to the DGAP to conduct detailed investigation.
2. On receipt of the recommendation from the Standing Committee on Anti-profiteering, the DGAP had issued Notice dated 15.01.2019 under Rule 129 (3) of the above Rules, asking the Respondent to intimate as to whether he admitted that the benefit of ITC had not been passed on to the above Applicant by way of commensurate reduction in the price of the flat and in case it was so, to suo-moto compute the quantum of the same and mention it in his reply to the Notice along with the supporting documents. The Respondent was given opportunity to inspect the non-confidential evidence/information furnished by the Applicant No. 1 during the period between 21.01.2019 to 23.01.2019 in accordance with Rule 129 (5) of the above Rules but the Respondent did not avail of the said opportunity. Vide e-mail dated 10.06.2019, the above Applicants were also given opportunity to inspect the non-confidential documents/reply submitted by the Respondent on 13.06.2019 or 14.06.2019. However, the Applicants did not avail of the said opportunity.
3. The DGAP has covered the period from 01.07.2017 to 31.12.2018 during the current investigation. The time limit to complete the investigation was extended by this Authority, vide its order dated 19.03.2019 in terms of Rule 129 (6) of the above Rules.
4. The DGAP has further stated that the Respondent had submitted replies vide his letters/emails dated 29.01.2019, 08.02.2019, 20.02.2019, 05.03.2019, 21.05.2019, 06.06.2019, 11.06.2019 and 17.06.2019. The submissions of the Respondent were summed up by the DGAP as is mentioned in the subsequent Para.
5. The Respondent had stated before the DGAP that he had informed the Applicants over telephone and through e-mails regarding passing on the benefit of GST input tax credit. Further, a number of changes were taking place in the GST regime, such as, changes in the GST rate and applicability of GST on Affordable Housing Project. The Respondent had ensured that the benefit of actual input tax credit should be passed on to all his home buyers. The Respondent, vide e-mail dated 07.06.2019, had submitted sample copies of letters issued to the individual home buyers, informing them about the benefit of input tax credit as per his calculation and credit of the same to them. The Respondent had submitted that he had passed on the benefit of Rs. 81,82,783/- to the home buyers.
6. The Respondent had also submitted the following documents/information to the DGAP vide his above mentioned letters/e-mails during the course of the investigation:-
(a) Copies of GSTR-1 Returns for the period July, 2017 to December, 2018.
(b) Copies of GSTR-3B Returns for the period July, 2017 to December, 2018.
(c) Copies of VAT Returns (including all annexures) & ST-3 Returns for the period April, 2016 to June, 2017.
(d) Copies of all demand letters issued and sale agreement made with the Applicant.
(e) Copies of Balance Sheet for FY 2016-17& 2017-18.
(f) Copy of Electronic Credit Ledger for the period 01.07.2017 to 31.12.2018.
(g) CENVAT/Input Tax Credit register for the FY 2016-17 and 2017-18 and April, 2018 to December, 2018.
(h) Details of VAT, Service Tax, ITC of VAT, CENVAT Credit for the period April, 2016 to June, 2017, for the project “Paradise”.
(i) List of home buyers in the project “Paradise” alongwith details of benefit passed on.
(j) Copy of RERA Registration Certificate of the Project “Paradise”.
(k) Copy of Tran-1.
7. The DGAP has also stated that all the documents placed on record were carefully examined by him and he had found that the main issues for determination were whether there was reduction in the rate of tax or benefit of ITC on the supply of construction service by the Respondent after implementation of the GST w.e.f. 01.07.2017 and in case it was so, whether the Respondent had passed on the above benefits to the home buyers as per the provisions of Section 171 of the CGST Act, 2017 or not.
8. The DGAP has further stated that the Respondent, vide his letter dated 29.01.2019 had submitted that he had informed the above Applicants from time to time through telephonic discussion about the benefit of GST input tax credit and assured the Applicant that he would pass on such benefit to all his home buyers as early as possible. Further, vide letter dated 08.02.2019, the Respondent had informed that he was in the process of computation of additional profit under the GST regime and that he would pass on the GST benefit to all his recipients. The Respondent, vide e-mail dated 07.06.2019 had submitted sample copies of letters issued to the individual flat buyers, informing them about the benefit of input tax credit as per his calculations and credit of the same to his home buyers’ accounts.
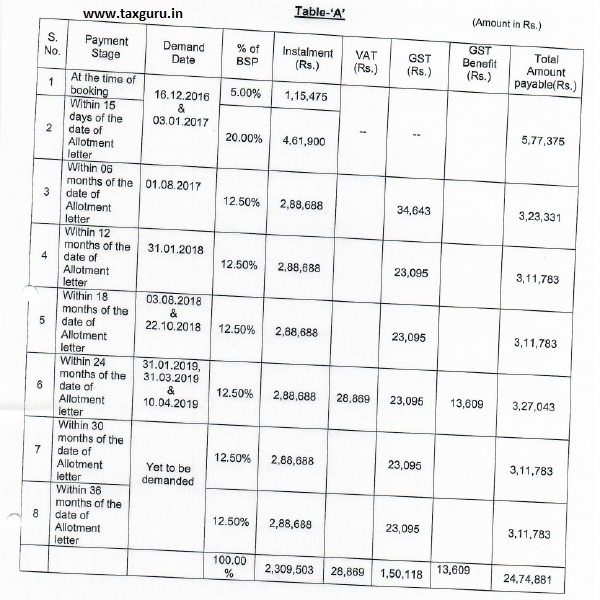
9. The Respondent had submitted a copy of RERA Registration Certificate of his Project “Paradise” and the payment schedule for the purchase of flats at the basic sale price of Rs. 4,000/- per square feet for carpet area and Rs. 500/- per square feet for Balcony area. The Respondent, vide letter dated 08.02.2019 and subsequent e-mails, had submitted copies of demand letters issued to the Applicant No.1. The details of amounts and taxes paid by the Applicant to the Respondent were furnished by the DGAP as given in Table-A below:-
10. The DGAP has further stated that para 5 of Schedule-III of the Central Goods and Services Tax Act, 2017, defining activities or transactions which shall be treated neither as a supply of goods nor a supply of services, reads as “Sale of land and, subject to clause (b) of paragraph 5 of Schedule II, sale of building”. Further, Clause (b) of para 5 of Schedule II of the Central Goods and Services Tax Act, 2017 reads
“(b) construction of a complex, building, civil structure or a part thereof, including a complex or building intended for sale to a buyer, wholly or partly, except where the entire consideration has been received after issuance of completion certificate, where required, by the competent authority or after its first occupation, whichever is earlier”. In the light of these provisions, the DGAP has contended that the ITC pertaining to the units which were under construction but not sold was provisional ITC that may be required to be reversed by the Respondent, if such units would remain unsold at the time of issue of CC, in terms of Section 17 (2) & Section 17 (3) of the Central Goods and Services Tax Act, 2017 which read as under:-
17 (2) Where the goods or services or both are used by the registered person partly for effecting taxable supplies including zero-rated supplies under this Act or under the Integrated Goods and Services Tax Act and partly for effecting exempt supplies under the said Acts, the amount of credit shall be restricted to so much of the input tax as is attributable to the said taxable supplies including zero-rated supplies.
17 (3) The value of exempt supply under sub-section (2) shall be such as may be prescribed, and shall include supplies on which the recipient is liable to pay tax on reverse charge basis, X transactions in securities, sale of land and, subject to clause (b) of paragraph 5 of Schedule II, sale of building.
Therefore, the DGAP has claimed that the ITC pertaining to the unsold units was outside the scope of this investigation and the Respondent was required to recalibrate the selling price of such units to be sold to the prospective buyers by considering the net benefit of additional ITC available to him post-GST.
11. The DGAP has also observed that prior to 01.07.2017, i.e., before the GST was introduced, as the service of construction of affordable housing provided by the Respondent, was exempt from Service Tax vide Notification No. 25/2012-ST dated 20.06.2012 (as amended by Notification No. 9/2016-ST dated 01.03.2016) and thus the Respondent was not eligible to avail CENVAT credit of Central Excise duty paid on the inputs or Service Tax paid on the input services, as per the CENVAT Credit Rules, 2004, which were in force at the material time. However, the Respondent was eligible to avail credit of Service Tax paid on the input services (CENVAT credit of Central Excise duty was not available) in respect of the commercial shops sold by him. The Respondent was also eligible to avail input tax credit of VAT paid on the inputs. Further, post-GST, the Respondent could avail input tax credit of GST paid on all the inputs and input services. From the data submitted by the Respondent covering the period April, 2016 to December, 2018 the details of the input tax credit availed by him, his turnover from the project “Paradise” and the ratio of input tax credit to turnover, during the pre-GST (April, 2016 to June, 2017) and post-GST (July, 2017 to December, 2018) periods was furnished by the DGAP as per the Table-B given below:-
Table-s’
(Amount in Rs.)






