
Ashoke Sen Vs ITO (ITAT Kolkata)
Assessment Quashed – Invalid Notice u/s 143(2) Not in CBDT Prescribed Format – Violation of Instruction Dated 23.06.2017 – ITAT Kolkata
ITAT Kolkata quashed scrutiny assessment holding that notice issued u/s 143(2) dated 24.09.2018 was not in prescribed format mandated by CBDT Instruction F.No.225/157/2017/ITA-II dated 23.06.2017. Tribunal observed from extracted notice (pages 2–3) that statutory format for CASS scrutiny was not followed and CBDT circulars issued u/s 119 are binding on tax authorities. Relying on UCO Bank (SC), Amal Kumar Ghosh (Cal HC) and coordinate bench rulings, ITAT held that defective notice strikes at root of jurisdiction and entire assessment framed u/s 143(3) becomes void ab initio. Accordingly, assessment was annulled without examining merits and appeal of assessee allowed.
FULL TEXT OF THE ORDER OF ITAT KOLKATA
This is an appeal preferred by the assessee against the order of the National Faceless Appeal Centre, Delhi (hereinafter referred to as the “Ld. CIT(A)”] dated 10.09.2024 for the AY 2017-18.
2. At the outset, I note that the appeal of the assessee is barred by limitation by 09 days. At the time of hearing the counsel of the assessee explained the reasons for delay in filing the appeal. The Ld. D.R did not raise any objection in condoning the delay. After hearing the rival contentions and perusing the materials available on record, I find that the delay is for bonafide and genuine reasons and , hence, I condone the delay and adjudicate the appeal as under.
3. The only issue raised by the assessee is against the issue of notice u/s 143(2) in violation of CBDT Circular No. F.NO.225/157/2017/ITA-11 on 23.06.2017.
4. The facts in brief are that the assessee filed the return of income u/s on 07.11.2017, declaring total income of ₹4,38,840/-, which was selected for scrutiny under Computer Assisted Scrutiny Selection (CASS). Thereafter the notice u/s 143(2) were issued on 24.09.2018 & Notice u/s 142(1) of the Act on 24.04.2019, 16.07.2019 and 17.08.2019, were issued along with the questionnaire which were duly served upon the assessee. The AO framed u/s 143(3) read with of the Act vide order dated 14.12.2019, by determining the total income at ₹38,36,690/-.
5. In the appellate proceedings also the ld. CIT (A) confirmed the order of the ld. AO by dismissing the appeal of the assessee.
6. After hearing the rival contentions and perusing the materials available on record, I find that particularly the notice was issued u/s 143(2) of the Act on 24.09.2018, a copy of which is available at Annexure-A of the assessee. I note that the said notice has not been issued in consonance with the CBDT Instruction F No. 225/157/2017/ITA-II Dated 23.06.2017. The said notice is extracted below for the sake of ready reference:-
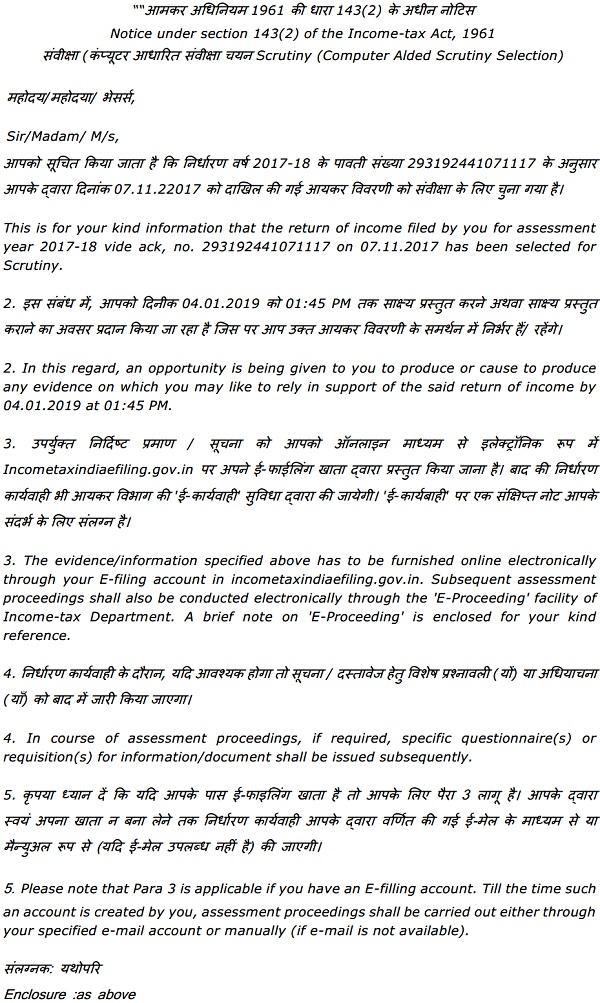
7. In our opinion, the notice issued u/s 143(2) of the Act which is not in the prescribed format as provided under the Act is an invalid notice and accordingly, all the subsequent proceedings thereto would be invalid and void ab initio. The case of the assessee find support from the decision of Shib Nath Ghosh Vs. ITO in ITA No. 1812/KOL/2024 for A.Y. 2018-19 vide order dated 29.11.2024, wherein the co-ordinate Bench has held as under:-
“10. After hearing both the sides and the materials available on record, we find that the notice issued u/s 143(2) dated 9th August, 2017 was not in any of the formats as provided in the CBDT instruction F.No.225/157/2017/ITA-II dated 23.06.2017. We have examined the notice, copy of which is available at page no.1 of the Paper Book and find that the same is not as per the format of CBDT Instruction F.No. 225/157/2017/ITA-II dated 23.06.2017 as stated above. In our opinion, the instruction issued by the CBDT are mandatory and binding on the Income tax authorities failing which the proceedings would be rendered as invalid. Hon’ble Apex Court in case of UCO Bank (supra) held that the circular issued by CBDT in exercise of its statutory powers u/s 119 of the Act, are binding on the authorities. The Hon’ble Apex court held as under:-:-
“The Central Board of Direct Taxes under section 119 of the Income-tax Act, 1961, has power, inter alia, to tone down the rigour of the law and ensure a fair enforcement of its provisions, by issuing circulars in exercise of its statutory powers under section 119 of the Act which are binding on the authorities in the administration of the Act. Under section 119(2)(a), however, the circulars as contemplated therein cannot be adverse to the assessee. The power is given for the purpose of just, proper and efficient management of the work of assessment and in public interest. It is a beneficial power given to the Board for proper administration of fiscal law so that undue hardship may not be caused to the assessee and the fiscal laws may be correctly applied. Hard cases Which can be properly categorized as belonging to a class, can thus be given the benefit of relaxation of law by Issuing circulars binding on the taxing authorities.
In order to aid proper determination of the income of money lenders and banks, the Central Board of Direct Taxes issued a circular dated October 6, 1952, providing that where interest accruing on doubtful debts is credited to a suspense account, It need not be included in the assessee’s taxable income, provided the Income-tax Officer is satisfied that recovery is practically improbable. Twenty-six years later, on June 20, 1978, in view of the judgment of the Kerala High Court In STATE BANK OF TRAVANCORE v. CIT [1977] 110 ITR 336, the Board by another circular, withdrew with immediate effect the earlier circular. However, by circular dated October 9, 1984, the Board decided that Interest in respect of doubtful debts credited to suspense account by banking companies would be subjected to tax but Interest charged in an account where there has been no recovery for three consecutive accounting years would not be subjected to tax in the fourth year and onwards. The circular also stated that if there is any recovery in the fourth year or later, the actual amount recovered only would be subjected to tax in the respective years. This procedure would apply to assessment year 1979-80 and onwards.
11. Similarly, Hon’ble Calcutta High Court in case of Amal Kumar Ghosh (supra), held as under:-
“Held, allowing the appeal, (1) that even assuming that the intention of the Central Board of Direct Taxes was to restrict the time for selection of the cases for scrutiny to a period of three months, It could not be said that the selection in the case of the assessee was made within the period. The return was filed on October 29, 2004, and the case was selected for scrutiny on July 6, 2005. By any process of reasoning, it was not open to the Tribunal to come to a finding that the Department acted within the four corners of Circulars Nos. 9 and 10 Issued by the Central Board of Direct Taxes The circulars were evidently violated. The circulars were binding upon the Department under section 119.”
12. Therefore case of the assessee is therefore squarely covered by the ratio laid down in the above decisions and respectfully following the same , we are inclined to hold the assessment as invalid being based on the invalid issue of notice u/s 143(2) of the Act. The first additional ground raised by the assessee is allowed.”
8. Similarly, decision of the co-ordinate bench in case of Kamlesh Singh Vs. ITO in ITA No. 2459/KOL/2025 vide order dated 12.01.2026, wherein it has held as under:-
“6. I have considered the rival submissions. As it is noticed that the Assessing Officer who has passed the assessment has not issued notice u/s.143(2) of the Act. Such notice has been issued by an authority who has no jurisdiction over the assessee on this ground notice u/s.143(2) of the Act is quashed and I do so.
7. It is also noticed that the notice issued u/s.143(2) of the Act is not in line with the Circular issued by the CBDT in respect of e-notice. This being so, respectfully following the decision of the coordinate bench of the Tribunal in the case of M/s Durga Automotives Pvt. Ltd., referred to supra, the notice is found to be invalid and consequently the same stands quashed. Since there is no valid notice issued u/s.143(2) of the Act to the assessee before completion of the assessment u/s.143(3) of the Act, the consequential assessment order passed by the Assessing Officer also stands quashed.”
9. Similarly, decision of the co-ordinate bench in case of Basudeb Das Vs. ITO in ITA No. 1308/KOL/2024 for A.Y. 2017-18 vide order dated 24.04.2025, wherein it has held as under:-
“5. We note that the additional ground raised by the assessee is with regard to issuance of notice u/s.143(2) of the Act on 24.09.2018 in violation to CBDT Instruction f.No.225/157/2017/ITA-II dated 23.06.2017. The ld. AR also placed before us the above instruction issued by the Government of India, Ministry of Finance, Department of Revenue, wherein it has been provided that w.e.f. 23.06.2017, the notice u/s.143(2) of the Act to be issued in any of the three following forms :-
-
- Limited Scrutiny (Computer Aided Scrutiny Selection
- Complete Scrutiny (Computer Aided Scrutiny Selection)
- Compulsory Manual Scrutiny
6. The ld. AR submitted that the notice is not bearing to any of the above forms prescribed by the CBDT in the above instruction, therefore, notice issued u/s.143(2) of the Act is bad in law for which the assessment is not sustainable. Ld. AR in defense of his arguments, relied on following series of decisions, wherein similar issue has been decided in favour of the assessee :-
-
- Lavanya Estates Pvt. Ltd. vs. ITO ITA No.: 342/PAT/2023 PATNA ITAT
- Shri Rudraprasad Mondal vs. DCIT ITA No.: 702/K/2024 [08.10.2024] Kolkata ITAT
- Dev Milk Foods Pvt. Ltd. vs. Addl. CIT Spl. R-3,New Delhi Delhi ITAT [ITA No.: 6767/Del/2019] dt. 12.06.2023
- Sukhdham Infrastructure LLP vs. ITO [ITA No.: 2611/Kol/2019] dt. 23.02.2023 Kolkata ITAT
7. Since the facts and issue involved in the present case are identical to the decisions as relied on by the ld. AR above, we are inclined to hold that notice issued u/s.143(2) of the Act is invalid and, therefore, the assessment framed u/s.143(3) of the Act is also invalid and accordingly quashed. Consequently, the additional ground raised by the assessee is allowed.”
10. Considering the facts of the instant case in the light of the decisions of the co-ordinate benches, I am inclined to hold that notice issued u/s 143(2) of the Act is invalid notice and accordingly, the assessment framed consequentially to that is also invalid and is hereby quashed.
11. In the result, the appeal of the assessee is allowed.
Order pronounced in the open court on 17.02.2026.








