
Hemant Shantill Jain Vs Asst. CIT (Madras High Court)
Madras High Court set aside the impugned order as it was based on one basis that writ petitioner’s case is not covered under instruction no. 1914 dated 02.12.1993.
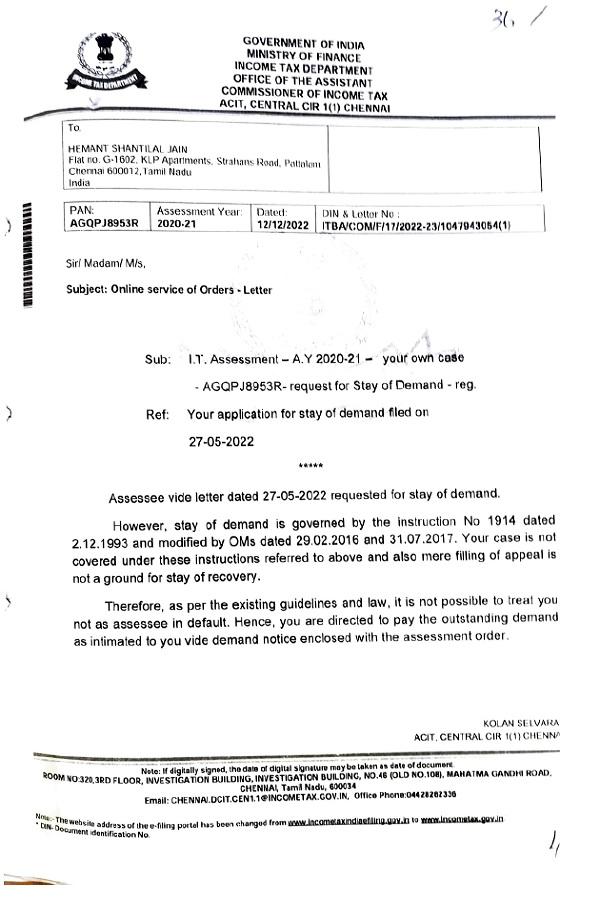
Facts- A search operation qua the writ petitioner u/s. 132 of the ‘Income Tax Act, 1961’; that on the basis of seized material, a notice u/s. 153C of IT Act was issued; that this was followed by a notice dated 14.12.2021 u/s. 143(2) and a notice dated 20.01.2022 u/s. 142(1); that all this culminated in an order dated 28.03.2022 made by the first respondent inter alia u/s. 143(3) read with Section 153 of IT Act; that vide the said order of AO, AO had come to the conclusion that there is unaccounted capital drawings and unexplained interest credit both u/s. 56 of IT Act; that pursuant to such assessment a demand of Rs.73,23,592/- was raised; that the said order of AO was carried in appeal by the writ petitioner by way of an appeal dated 26.04.2022 to the second respondent; that it is to be noted that the second respondent is the Appellate Authority; that this Court is informed that the appeal is u/s. 246A of IT Act; that pending appeal, writ petitioner moved the first respondent (Assessing Officer) u/s. 220(6) of IT Act with an interim prayer; that the first respondent in and by a terse ‘order dated 12.12.2022 bearing reference ITBA/COM/F/17/2022-23/1047943054(1)’ negatived the interim prayer; that captioned writ petition has been filed assailing the impugned order.
Conclusion- The impugned order i.e., order dated 12.12.2022 bearing reference ITBA/COM/F/17/2022-23/1047943054(1) made by the first respondent is set aside. The impugned order is set aside on the sole ground that it has proceeded on the lone erroneous basis that said instruction (Instruction No.1914 dated 02.12.1993 as modified by two office memoranda dated 29.02.2016 and 31.07.2017) does not apply to the writ petitioner.
FULL TEXT OF THE JUDGMENT/ORDER OF MADRAS HIGH COURT
This order will now dispose of the captioned writ petition and captioned ‘Writ Miscellaneous Petition'[‘WMP’ for the sake of brevity].
2. Ms.Vandana Vyas, learned counsel on record for writ petitioner is before this Court. Learned counsel submitted that there was a search operation qua the writ petitioner under Section 132 of the ‘Income Tax Act, 1961’ (‘IT Act’ for the sake of brevity); that on the basis of seized material, a notice under Section 153C of IT Act was issued; that this was followed by a notice dated 14.12.2021 under Section 143(2) and a notice dated 20.01.2022 under Section 142(1); that all this culminated in an order dated 28.03.2022 made by the first respondent inter alia under Section 143(3) read with Section 153 of IT Act [hereinafter ‘said order of Assessing Officer’ for the sake of convenience and clarity]; that vide the said order of Assessing Officer, the Assessing Officer had come to the conclusion that there is unaccounted capital drawings and unexplained interest credit both under Section 56 of IT Act; that pursuant to such assessment a demand of Rs.73,23,592/- was raised; that the said order of Assessing Officer was carried in appeal by the writ petitioner by way of an appeal dated 26.04.2022 to the second respondent; that it is to be noted that the second respondent is the Appellate Authority; that this Court is informed that the appeal is under Section 246A of IT Act; that pending appeal, writ petitioner moved the first respondent (Assessing Officer) under Section 220(6) of IT Act with an interim prayer; that the first respondent in and by a terse ‘order dated 12.12.2022 bearing reference ITBA/COM/F/17/2022-23/1047943054(1)’ [hereinafter ‘impugned order’ for the sake of convenience and clarity] negatived the interim prayer; that captioned writ petition has been filed assailing the impugned order.
3. Considering the narrow compass on which the captioned main writ petition turns, this Court deemed it appropriate to take up the captioned main writ petition with the consent of counsel for writ petitioner and Mr.A.P.Srinivas, learned Senior Standing Counsel (Income Tax) along with Ms.S.Premalatha, learned Junior Standing Counsel (Income Tax) who accepted notice for both the respondents.
4. As already alluded to supra, the impugned order of the first respondent is terse and a scanned reproduction of the same is as follows:
–







