
LTM Limited Vs Commissioner of GST & Central Excise (GSTAT Chennai)
Summary: The GST Appellate Tribunal (GSTAT), Chennai Bench, held that a fresh pre-deposit under Section 112(8) of the CGST Act, 2017, is unnecessary where the amount already deposited under Section 107(6) exceeds the cumulative statutory pre-deposit requirement calculated on the tax demand surviving before the Tribunal. In the present case, the original adjudication order confirmed a tax demand of Rs.3,29,47,353, against which the appellant deposited Rs.32,94,735 through FORM GST DRC-03. The First Appellate Authority subsequently remanded a substantial portion of the demand and upheld only Rs.53,90,420. The cumulative pre-deposit requirement for the surviving demand was consequently Rs.10,78,084.
The Tribunal observed that Sections 107(6) and 112(8) prescribe a cumulative pre-deposit requirement and do not mandate payment through a fresh challan after the first appellate order. Pre-deposit constitutes a portion of the disputed tax rather than an independent levy. Requiring the appellant to obtain a refund of the excess deposit and subsequently redeposit the same amount would serve no revenue purpose. The Tribunal relied upon judicial precedents, CBIC Circular No. 224/18/2024-GST dated 11.07.2024 and the legislative intent behind reducing the GSTAT pre-deposit requirement from 20% to 10%.
Accordingly, the Tribunal held that the pre-deposit requirement stood satisfied and the defect raised by the Registry was cured. It directed appropriation of Rs.10,78,084 against the surviving demand, generation of FORM GST APL-04 within one month, adjustment through FORM GST DRC-03A and submission of an undertaking against double utilisation of the pre-deposit. The Registry was directed to admit the appeal after compliance with these directions.
Cases Discussed
- Manoranjan Dash Vs Commissioner, CT & GST, Odisha (GSTAT Cuttack); 2026 (9) TMI 1651; 21.09.2026 – Reconsideration of additional pre-deposit requirement rejected.
- Manoranjan Dash Vs Commissioner, CT & GST, Odisha (GSTAT Cuttack); 2026 (7) TMI 829; 08.07.2026 – No fresh deposit required.
- Ashirwad Food Industries Vs Union of India (Jharkhand High Court); 2026 (2) TMI 596 (DB); 09.02.2026 – Earlier deposit sufficient after reduction of demand.
- MMTC-PAMP India (P.) Ltd. Vs Deputy Commissioner (Madras High Court); [2024] 164 taxmann.com 37 – Cumulative computation and credit for earlier payments.
- CCE Vs Ratan Melting & Wire Industries (Supreme Court); 2008 (231) ELT 22 (SC) – Cited regarding binding circulars.
- Commissioner of Customs, Calcutta Vs Indian Oil Corporation Ltd. (Supreme Court); (2004) 3 SCC 488 – Cited regarding binding circulars.
FULL TEXT OF THE ORIGINAL JUDGMENT/ORDER
1. The Filing No. 2626059101000236 was taken up by the Bench. The Registry raised the defect relating to payment of pre-deposit under Section 112(8) of the Central Goods and Services Tax Act, 2017. The Ld. Representatives of the Applicant/Appellant and the Respondent are present.
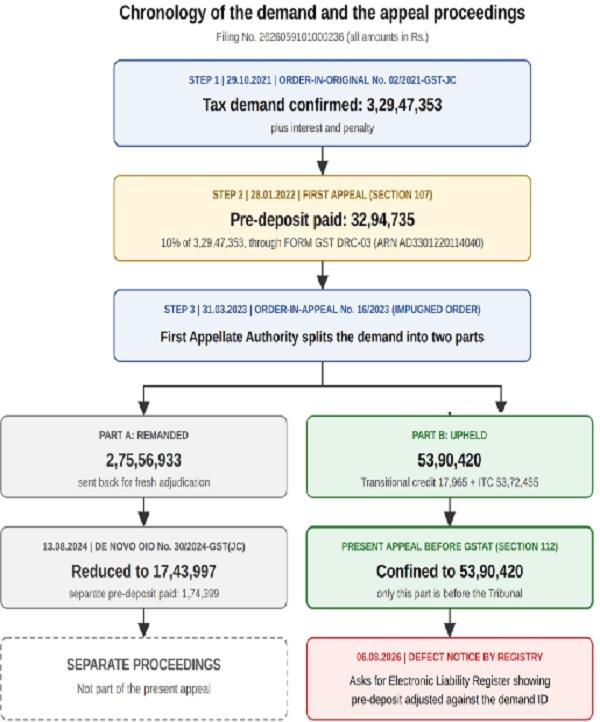
2. The brief facts of the case are that the Order-in-Original No. 02/2021-GST-JC dated 29.10.2021 confirmed a tax demand of Rs.3,29,47,353/- with interest and penalty. The Applicant/Appellant deposited Rs.32,94,735/- (10% of the tax in dispute) through FORM GST DRC-03 (ARN AD3301220114040) dated 28.01.2022 and appealed under Section 107 of the Act. By Order-in-Appeal No. 16/2023 dated 31.03.2023, the First Appellate Authority remanded the demand of Rs.2,75,56,933/- and upheld the demand of Rs.53,90,420/- (transitional credit of Rs.17,965/- and ITC of Rs.53,72,455/-). The remanded demand, since reduced to Rs.17,43,997/- in de novo OIO No. 30/2024-GST(JC) dated 13.08.2024, is the subject of separate proceedings. The present appeal is confined to Rs.53,90,420/-, which was upheld by the First Appellate Authority. The Registry, by Defect Notice dated 06.08.2026, called for the Electronic Liability Register reflecting adjustment of pre-deposit against the relevant demand ID.
3. By written submissions dated 29.09.2026 (Document Sr. No.32), reiterated at the hearing, the Ld. Advocate for the Appellant submitted that the aggregate requirement under Sections 107(6) and 112(8) for the disputed tax of Rs.53,90,420/- is Rs.10,78,084/-, against which Rs.32,94,735/- already stands deposited; that no demand ID/APL-04 has been created on the portal for the impugned order, making DRC-03A adjustment impossible; and relied on Manoranjan Dash (GSTAT Cuttack), Ashirwad Food Industries (Jharkhand HC), CBIC Circular No. 224/18/2024-GST and the 53rd GST Council decisions.
4. By written submissions/verification report dated 07.09.2026 (Document Sr. No.31 on the portal), the Respondent has confirmed the payment of Rs.32,94,735/- (DRC-04 issued), but contended that under Section 112(8)(b) a sum of 10% of the remaining tax in dispute must be paid “in addition to the amount paid under sub-section (6) of section 107”, and hence Rs.5,39,042/- has to be separately paid, notwithstanding that the earlier deposit is in excess.
5. Heard the Appellant Advocate and Authorised on 01.09.2026, 08.09.2026 and 29.09.2026 and perused the records. The issue is whether, when the amount deposited under Section 107(6) exceeds the cumulative pre-deposit under Sections 107(6) and 112(8) computed on the tax surviving in dispute before this Tribunal, a further deposit is required or not for maintaining the appeal.
6. The Section 112(8)(b) says
“(8) No appeal shall be filed under sub-section (1), unless the appellant has paid-
(a) in full, such part of the amount of tax, interest, fine, fee and penalty arising from the impugned order, as is admitted by him, and
(b) a sum equal to ten per cent of the remaining amount of tax in dispute, in addition to the amount paid under sub-section (6) of section 107, arising from the said order, subject to a maximum of twenty crore rupees , in relation to which the appeal has been filed.”
Three features are decisive. (i) The measure is the tax in dispute “arising from the said order” and “in relation to which the appeal has been filed”, i.e. Rs.53,90,420/- under the impugned order; the remanded demand is not before us. (ii) The words “in addition to the amount paid under sub-section (6) of section 107” fix a cumulative quantum, namely 10% at the first stage plus a further 10% at this stage, i.e. 20% of the tax in dispute in this appeal; they do not refer to the entire sum deposited against a much larger original demand. (iii) The opening words “No appeal shall be filed before the Appellate Authority unless the appellant has paid” only require that the requisite amount stands paid on the date of filing. The Act does not require the further 10% to be paid by a fresh challan after the first appellate order, nor does it bar reckoning an amount already lying with the Revenue against the same demand.
7. Computation: The position, undisputed on figures, is as follows:
| Sl. | Particulars | Basis | Amount (Rs.) |
|---|---|---|---|
| (a) | Tax in dispute in the present appeal (upheld by OIA No.16/2023) | — | 53,90,420 |
| (b) | Pre-deposit attributable to first appeal – Section 107(6)(b) | 10% of (a) | 5,39,042 |
| (c) | Further pre-deposit for this appeal – Section 112(8)(b) | 10% of (a) | 5,39,042 |
| (d) | Aggregate pre-deposit required [(b)+(c)] | 20% of (a) | 10,78,084 |
| (e) | Amount actually deposited (DRC-03 dated 28.01.2022) | Verified by Respondent | 32,94,735 |
Even on the Respondent’s reading of the words “in addition to”, the requirement is met. By Order-in-Appeal No. 16/2023 dated 31.03.2023 (the impugned order), which holds the field as on date, the First Appellate Authority upheld a demand of Rs.53,90,420/- (transitional credit of Rs.17,965/- and ITC of Rs.53,72,455/-). With reference to this surviving demand, the amount of Rs.32,94,735/- already deposited by the Applicant/Appellant covers two distinct components: (i) Rs.5,39,042/-, being the pre-deposit attributable to the first appeal under Section 107(6)(b); and (ii) a further Rs.5,39,042/-, being the pre-deposit for the present appeal before this Tribunal under Section 112(8)(b). The second component is thus accounted for over and above the first, and the two together make up the total pre-deposit of Rs.10,78,084/-. The requirement of “in addition to” therefore stands satisfied, and Section 112(8)(b) is complied with both in letter and in spirit.
8. Pre-deposit is not a separate levy: Pre-deposit is a portion of the disputed tax itself, which is adjusted against the demand if the appellant fails and refunded with interest under Section 115 read with Section 56 of the Act if the appellant succeeds. Pre-deposit requirements under Sections 107(6) and 112(8) are not watertight compartments, and book adjustment between them is permissible. The Respondent’s construction would require the Revenue first to refund the excess with interest under Section 115, and the Appellant then to re-deposit Rs.5,39,042/- out of the very same money, a circular exercise that serves no revenue purpose and causes an interest outgo to the Exchequer. A construction leading to such an anomalous result must be avoided. Moreover, Section 112(8) is a procedural condition for access to the appellate remedy and not a charging provision, so a literal reading does not require a meaningless double payment.
9. Judicial precedents: The Hon’ble High Court of Jharkhand in Ashirwad Food Industries v. Union of India, 2026 (2) TMI 596 (DB), vide order dt 09-02-2026 held that where Rs.23.85 lakh had been deposited at the first stage against a demand of about Rs.2.38 crore, later reduced to about Rs.40 lakh, there was “no question of making any further pre-deposit” before the Tribunal. Following it, the GSTAT, Cuttack Bench in Manoranjan Dash v. Commissioner, CT & GST, Odisha, 2026 (7) TMI 829, vide order dt. 08-07-2026 held that no further pre-deposit is required. On the Revenue’s application specifically seeking reconsideration of the expression “in addition to the amount paid under sub-section (6) of section 107”, the same Bench, after hearing the Revenue affirmed this view by order dated 21.09.2026 [2026 (9) TMI 1651], holding that the pre-deposit “is not a payment towards any separate or independent liability” and that a literal insistence would “give only an anomalous or unworkable result”. The Hon’ble jurisdictional High Court of Madras in MMTC-PAMP India (P.) Ltd. v. Deputy Commissioner, [2024] 164 taxmann.com 37, also computed the Section 112(8) requirement cumulatively, giving credit for amounts already remitted and directing payment only of the shortfall. No contrary decision has been cited by the Respondent. We respectfully agree with these decisions.
10. CBIC Circular No. 224/18/2024-GST dated 11.07.2024: Issued under Section 168(1) of the Act, it clarifies in para 7.2 that amounts paid in advance through the Electronic Liability Register, or through FORM GST DRC-03 and adjusted through FORM GST DRC-03A, “shall also be liable to be adjusted towards the amount required to be paid as pre-deposit under Section 107 and Section 112”. Para 8.2 further directs that, “the amount paid vide FORM GST DRC-03 may be adjusted against the pre-deposit under section 107 or section 112 of the CGST Act, as the case may be, as detailed in para 7.2 above”. The CBIC has thus itself recognised that the stage and mode of payment do not matter, so long as the amount stands deposited against the disputed demand. Such circulars bind the departmental officers [Commissioner of Customs, Calcutta v. Indian Oil Corporation Ltd., (2004) 3 SCC 488 and CCE v. Ratan Melting & Wire Industries, 2008 (231) ELT 22 (SC)]. In the present case, the Respondent’s own verification report dated 07.09.2026 sufficiently proves the deposit.
11. Legislative intent and erstwhile law: On the recommendation of the 53rd GST Council, the Finance (No. 2) Act, 2024 reduced the pre-deposit under Section 112(8) from 20% to 10% and the cap from Rs.50 crore to Rs.20 crore, to ease the working-capital burden on appellants and align with the erstwhile law. Under the erstwhile law (Section 35F of the Central Excise Act, 1944 and Section 129E of the Customs Act, 1962), CBEC Circular No. 984/08/2014-CX dated 16.09.2014 recognised that amounts paid even during investigation or audit, before filing the appeal, count towards the pre-deposit. Insisting on a fresh deposit when three times the required amount already lies with the Revenue would defeat this object.
12. Safeguard against double counting: The deposit of Rs.20,40,200/- dated 12.06.2026 (relating to the separate appeal against OIA No. 332/2025) and Rs.1,74,399/- (relating to the remanded demand) have not been reckoned here. Out of Rs.32,94,735/-, an amount of Rs.10,78,084/- shall stand appropriated as pre-deposit under Sections 107(6) and 112(8) for this appeal and shall not be reckoned for any other proceeding. This is without prejudice to the Appellant’s rights in law regarding the balance.
13. In view of the above, it is ordered that:
(i) The pre-deposit requirement under Section 112(8) of the Act stands satisfied; no further pre-deposit is required, and the defect stands cured.
(ii) The jurisdictional proper officer shall map Rs.10,78,084/- against the demand under the impugned order in the Electronic Liability Register as and when the demand ID is generated. The Appellant shall file DRC-03A in terms of CBIC Circular No. 224/18/2024-GST dated 11.07.2024.
(iii) The demand against the Appellant was reduced under Section 107 of the CGST Act, 2017, vide Order-in-Appeal No. 16/2023 dated 31.03.2023, passed by the Office of the Commissioner of GST & Central Excise (Appeals-II), Chennai. However, it is observed that the First Appellate Authority has not electronically generated APL-04, electronically not reflecting the actual amount of tax, interest and penalty, as determined pursuant to the said appellate order. The First Appellate Authority is directed to electronically generate APL-04 within a period of one month from the date of this order. The Learned Authorised Representative appearing for the Respondent is directed to upload the electronically generated APL-04 on the GSTAT Portal in the present appeal, immediately upon its generation. The Appellant is also directed to ensure that the 10% pre-deposit already made shall not be utilised or adjusted against any other demand and shall upload an undertaking to the said effect on the GSTAT Portal in the present appeal.
(iv) The Registry is directed to admit the appeal after the compliance of the above directions.








