
Anand Balvantrai Boghani Vs ITO (ITAT Rajkot)
Section 69 On-Money Addition Cannot Rest on an Unsigned Third-Party Excel Sheet Without Independent Corroboration
₹32 Lakh Added for Alleged Cash Payment on Flat Purchase
The Rajkot ITAT deleted an addition of ₹32 lakh under section 69 of the Income-tax Act, 1961 for alleged on-money paid to a builder. The Assessing Officer had relied on an unsigned Excel sheet recovered during a search of a third party. The Revenue produced no independent material showing that the buyer had actually paid the amount, and the buyer’s request for cross-examination was not granted. Following its coordinate Bench and the Gujarat High Court, the Tribunal held that the addition could not stand.
Builder Search Led to Reassessment of the Buyer
The assessee filed his original return for AY 2019–20 on 29 August 2019, declaring total income of ₹3,66,060. The return was processed under section 143(1) without adjustment. The Department subsequently received information through the Insight Portal following a search on 24 August 2021 covering several real estate groups in Rajkot, including the Gangdev Group.
An Excel workbook titled “TRINITY” was recovered from digital data associated with Praful Gangdev. It contained month-wise receipt data and an instalment sheet with fields for unit details, names, amounts, payables and receivables. The Assessing Officer interpreted the entries concerning unit C-703 in Trinity Towers as showing that the assessee had paid ₹32 lakh in cash. A notice under section 148 was issued on 28 March 2023, and the assessee filed a return in response declaring the same income.
Purchase Deed and Request for Cross-Examination
The assessee stated that he had purchased Flat C-703 from Buildcon Creations LLP for ₹27 lakh and furnished the purchase deed. He specifically denied paying on-money and sought an opportunity to cross-examine the person whose statement was relied upon. He contended that the spreadsheet, which bore neither his signature nor the seller’s, could not establish an actual cash payment.
The Assessing Officer treated the alleged payment as an unexplained investment under section 69, reasoning that the assessee had failed to explain the source of the cash. The CIT(A), National Faceless Appeal Centre, confirmed the addition. Before the Tribunal, the assessee pointed to the distinction between establishing that he had purchased the flat and establishing that he had paid a further amount outside the recorded consideration.
Coordinate Bench Required Proof of the Underlying Transaction
The assessee cited Chatrabhuj Narandas Vithlani, ITA No. 113/Rjt/2026, and Kaushik Jentibhai Rathod, ITA No. 940/Rjt/2026, which concerned additions based on the same workbook for purchases in the same project. The Tribunal principally followed the reasoning in RC Buildcon/RC Heights Pvt. Ltd., where the Rajkot Bench considered the evidentiary value of an unsigned spreadsheet seized from a third party.
The coordinate Bench had held that a spreadsheet entry required independent corroboration showing that the recorded transaction had actually taken place. It also treated the denial of cross-examination as material where the Department relied on a third party’s statement to support the addition. In discussing natural justice, that Bench referred to Kishinchand Chellaram v. CIT (1980) 125 ITR 713 (SC) and Andaman Timber Industries v. CCE (2015) 281 CTR 241 (SC). In Boghani’s case, the Revenue relied on the Assessing Officer’s findings and brought forward no material to distinguish the coordinate Bench’s reasoning.
Gujarat High Court Precedent Supported Deletion
The coordinate Bench had relied on PCIT v. Kaushik Nanubhai Majithia, R/Tax Appeal No. 20 of 2024, decided on 6 March 2024. In that case, the Gujarat High Court found that a developer’s payment of tax on an amount reflected in a spreadsheet did not establish that the particular buyer had actually paid it. The spreadsheet was unsigned, the entry lacked corroboration and the statements recorded during the search had not been supplied to the assessee.
Applying the same evidentiary reasoning, the Rajkot ITAT deleted the entire addition of ₹32 lakh and allowed the assessee’s appeal. The operative finding concerned the sustainability of the addition on the evidence before the Tribunal.
Author’s Comments
The crucial question under section 69 was whether the assessee had actually made the alleged investment. An inquiry into the source of the money presupposes evidence that the payment occurred. Here, the purchase deed identified the flat and the stated consideration. The developer’s spreadsheet supplied a figure that the Department interpreted as an additional cash payment. The missing link was evidence showing that this buyer paid that amount for this flat.
The decision is particularly relevant where a search reveals a developer’s internal records and the Department seeks to use them against individual purchasers. The significance of any entry depends on what supports it and whether the purchaser has had a meaningful opportunity to test the statement used to explain it.
Cases Discussed:
- Kishinchand Chellaram Vs CIT (Supreme Court); (1980) 125 ITR 713 — opportunity to confront adverse evidence.
- K.P. Varghese Vs ITO (Supreme Court); (1981) 131 ITR 597 — proof of actual consideration.
- Andaman Timber Industries Vs Commissioner of Central Excise (Supreme Court); (2015) 281 CTR 241 — cross-examination.
- PCIT Vs Kaushik Nanubhai Majithia (Gujarat High Court); R/Tax Appeal No. 20 of 2024; 06/03/2024 — unsigned spreadsheet and no corroboration.
- RC Heights Pvt. Ltd. Vs DCIT/ACIT (ITAT Rajkot); ITA Nos. 3 & 4/Rjt/2025; 13/04/2026 — uncorroborated third-party records.
- Chatrabhuj Narandas Vithlani (ITAT Rajkot); ITA No. 113/Rjt/2026; 12/06/2026 — same project and Excel sheet.
- Kaushik Jentibhai Rathod (ITAT Rajkot); ITA No. 940/Rjt/2026; 09/09/2026 — related spreadsheet evidence.
FULL TEXT OF THE ORDER OF ITAT RAJKOT
Captioned appeal filed by the assessee, pertaining to Assessment Year 2019- 20, is directed against the order under section 250 of the Income Tax Act, 1961 (hereinafter referred to as “the Act”) by Commissioner of Income-tax (Appeals), National Faceless Appeal Centre (NFAC) Delhi, dated 10.03.2026, which in turn arises out of an assessment order passed by the Assessing Officer u/s 147 of the Act, on 24.03.2024.
2. The grounds of appeal raised by the assessee are as follows:
“1. The assessment order u/s. 147 of the Act is bad in law.
2. The reopening of the assessment is bad in law.
3. The ld. CIT(A) has erred as well as on facts in passing a non speaking order without taking cognizance of and adjudicating the submission of the appellant.
4. The learned Assessing Officer has erred in law as well as on facts in making the addition of Rs. 32,00,000 u/s. 69 of the Act treating it as undisclosed income. The Id. CIT(A) has erred in law as well as on facts in confirming the same.”
3. Brief facts qua the issue are that the in this case, the Return of Income for the year under consideration i.e. A.Y. 2019- 20 was e-filed by the assessee on 29/08/2019, declaring therein total taxable income of Rs.3,66,060/-. The return of income so filed subsequently processed u/s 143(1) of the Act by CPC without making any adjustment to the taxable income of the assessee. Thereafter, assessing officer was in possession of information flagged in Insight Portal under category “High Risk CRU/VRU Information” that a search and seizure operation carried on 24/08/2021 in various concerns of R. K. Group and Gandev Group. During the search operation, it was unearthed that “on-money” in cash was received by the developers/builders of various concerns of Gangdev Group. In search operation from impounded incriminating digital data, documents, books of accounts, loose paper etc; it was found that during the previous year relevant to assessment year under consideration, the assessee gave “on-money” of Rs.32,00,000/-, in cash towards purchase/booking of unit(s) in project “Trinity Tower”. Since, the materials so disseminated pertained to or related to the assessee, a satisfaction was drawn as per the Explanation 2 to section 148 of the Income-tax Act, 1961 with the approval of specified authority i.e. Pr.CIT-1, Rajkot. This case was then reopened u/s 147 of the Income-tax Act, 1961 and a notice u/s 148 of the Income-tax Act, 1961 issued on 28/03/2023, which was delivered through email. In response, the assessee filed return of income on 24/04/2023, declaring total income of Rs.3,66,060/-. A notice u/s 143(2) of the Income-tax Act, 1961 was issued on 18/10/2023. A search and seizure action was carried out on 24.08.2021 by the Investigation wing Rajkot at the premises of leading real estate builders of Rajkot. Mainly four groups including Gangdev Group were covered during search. Gangdev group has completed several Real estate projects in Rajkot. The main person of the group is Shri Praful Gangdev who takes key decisions and is helped by several other partners. The partners vary for each project but Shri Kinjan Faldu, Shri Chandresh Panara, Shri Siddharth Gangdev are the key partners of Shri Praful Gangdev. The Gangdev group has completed projects like The Spire, The Spire-2, Trinity Towers in the city of Rajkot. M/s Buildcon Associates is one of the real estate developer firm of the group and has developed a commercial projects named “The Spire”. During the course of search action, the office premise as well as residence premise of Shri Praful Gangdev were also covered.
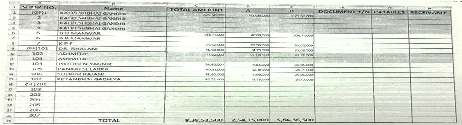
4. During the course of search and seizure action at the residence of Shri Praful Narendrabhai Gangdev, 3 iPhones, 5 Pen drives and 2 laptops were found and mirror imaging of the same along with e- mails, google drive was taken, which was subsequently seized in hard drive. During the analysis of the digital data of the above devices, one excel file named “TRINITY” from Google drive was found. The path of the file is (Working working data\[email protected]\drive\drive- copy):\hdd 2\Extracted download20210825T172410Z-001. (excel file “TRINITY” attached herewith). This excel file contains total of 6 sheets named “Sheet1”, “Sheet2”, “Sheet4”, “Sheet5”, “Instalment” and “Sheet3”. The Excel Sheet named “Sheet1” contains data of month-wise receipts of shops/offices and flats & total of the individual entries of each row has been recorded in the last column of that row. Excel Sheet2, Sheet4, Sheet5 and Sheet3 are blank sheets. The Excel Sheet named “Instalment” contains the columns named SHOP NO., Name, TOTAL AMOUNT, A, B, DOCUMENT Y/N, PAYABLES and RECEIVABLE. One screen print of sheet “instalment” from excel file TRINITY is pasted as under:
5. In response to the notice of the assessing officer, assessee, submitted that he did not pay “on money” and also stated that opportunity of cross-examination should be provided to the assessee, and no addition should be made based on excel sheet.
6. However, from the above pasted screen shot/excel sheets, the assessing officer noted that it can be seen that the excel sheet named contains different columns namely Sr no., Name, Total Amount, A, B, DOC etc. Thus, in such transaction no material details were maintained of Rs.32,00,000/- in cash for purchase of unit no.703. No satisfactory explanation of sources of such cash money is brought on record, in the circumstances and on facts, a sum of Rs.32,00,000/- was treated as deemed income of the assessee for the assessment year under consideration as per the provisions of section 69 of the Income-tax Act, 1961.
7. Being aggrieved by the said order of the Assessing Officer, the assessee filed an appeal before the Ld. CIT(A), but remained unsuccessful. Therefore, assessee is left with no other alternative but to knock on the doors of the Tribunal with this appeal praying for justice.
8. The Ld. Counsel for the assessee submitted written submission, which is reproduced below:
“1. It is submitted that Flat No. C-703 in the project named ‘TRINITY TOWERS’ was purchased by the appellant from M/s. Buildcon Creations LLP for a total consideration of Rs. 27,00,000/-. A copy of the purchase deed is enclosed herewith. [Page No. 1-37]
2. In the appellant’s case, the AO has made an addition of Rs. 32,00,000/- on the allegation that the appellant had made on-money payments for the purchase of the Flat No. C-703 in the project named ‘TRINITY TOWERS’. The above addition was made on the basis of the statement of Shri Praful Narendra Gangdev and the digital data in the form of an Excel Sheet (“Trinity”) found during the search.
3. The appellant’s case is directly covered by the Rajkot ITAT decision in the following identical cases wherein additions were made by the AO on the basis of the very same Excel Sheet titled “Trinity” in respect of purchases of properties in the same project, i.e. “TRINITY TOWERS”, from the same builder. The Hon’ble Tribunal deleted the addition of ‘on-money’ payment by holding that no addition can be made merely on the basis of an unsigned and uncorroborated third-party material, without providing an opportunity of cross-examination and in the absence of any independent corroborative evidence:
Shri Chatrabhuj Narandas Vithlani (ITA No. 113/RJT/2026 decision dated 12.06.2026). [Page No. 38-43]
Kaushik Jentibhai Rathod (TA No. 940/RJT/2026 decision dated 09.09.2026). [Page No. 44-54]
4. Reliance is also placed on the decision of the Jurisdictional Rajkot ITAT in the case of M/s. RC Heights Pvt. Ltd. (ITA No. 3 & 4/RJT/2025) wherein an identical situation of unilateral material seized (Excel sheet) during the search in the case of RK Group and corresponding addition made in the case of a third party came up for consideration before the Hon’ble Tribunal. The Hon’ble ITAT held that no addition can be made merely on the basis of an unsigned and uncorroborated third-party material, without providing an opportunity of cross-examination and in the absence of any independent corroborative evidence. A copy of this decision is enclosed herewith. [Page No. 55-77] While holding so, the Rajkot ITAT has relied upon the judgment of Hon’ble Gujarat High Court in the case of PCIT v. Kaushik Nanubhai Majithia (Judgment dated 06.03.2024 in Tax Appeal No. 20 of 2024). [Page No. 78-80]
5. In view of the above, it is prayed that the addition of Rs. 32,00,000/- made by the AO are unsustainable in law. The same may please be deleted and oblige.
6. It is further requested that if the Hon’ble bench is inclined to take a different view in appellant’s case from that adopted in the aforesaid decisions, an opportunity may please be granted to file a detailed paperbook and make further submissions and oblige.”
9. On the other hand, the Ld. DR for the revenue relied on the findings of the assessing officer.
10. I have heard, both the parties and carefully gone through the submission put forth on behalf of the assessee along with the documents furnished and the case laws relied upon, and perused the fact of the case including the findings of the Ld. CIT(A) and other materials brought on record. Learned Counsel for the assessee argued that the seized digital data contained excel sheet. The addition was made merely on the basis of third-party statement and digital data seized from another person and no cross-examination opportunity was provided. The entries pertained to excel sheet, which is neither signed by the assessee nor signed by the seller, therefore, no addition should be made based on dump document.
11. On the other hand, the Ld. DR for the Revenue has primarily reiterated the stand taken by the Assessing Officer, which I have already noted in my earlier para and is not being repeated for the sake of brevity.
12. I have considered submissions of both the parties. I note that issue under consideration is squarely covered in favour of the assessee by the decision of the Coordinate Bench of ITAT Rajkot in the case of M/s. RC Buildcon/M/s. RC Heights Pvt. Ltd. vide ITA Nos. 941/RJT/2024, for Assessment Year, 2019-20 & 2021-22, wherein, Co-ordinate Bench of ITAT held as follows:
“16. We note that the excel sheet, which was found from the third party’s premises, the opportunity of cross- examination ought to have been provided to the assessee. The owner of such excel sheet was the third party, therefore opportunity of cross examination was compulsory, to examine the veracity of excel sheet, as such excel sheet was neither signed by the assessee nor signed by the opposite party and moreover assessee`s name is not getting reflected on such excel sheet. We note that the assessee has strongly objected that until & unless, an opportunity of cross- examination is granted, such adverse material cannot be used against the assessee. This is strongly objected that until & unless, an opportunity of cross-examination is granted, such adverse material cannot be used against the assessee, as he said excel sheet was found from third party premises, hence, opportunity of cross-examination is necessary. Undoubtedly, apart from this excel -sheet, there is no positive evidence brought on record by the assessing officer to substantiate his findings that the assessee has actually received money out of books of accounts, hence, an opportunity of cross examination was mandatory in the assessee`s case under consideration.
17. It is settled law that any additions made in absence of providing opportunity of cross examinations of persons, whose statement has been relied upon for making the additions is in violation of natural justice, hence cannot be sustained. The Hon’ble Supreme Court of India, in the case of Krishnachand Chelaram Vs. CIT 125 ITR 713 (SC) and Andaman Timber Industries Vs. Commissioner of Central Excise (2015) 281 CTR 0241 (SC) has held that additions without providing the opportunity of cross examination is in violation of natural justice. Thus, we note that additions made in absence of providing opportunity of cross-examination of the persons, whose statement has been relied upon for making the additions is violation of principle of natural justice. We also note that not allowing the assessee to cross examine the witness by the adjudicating authority though the statements of those witnesses were made the basis of the impugned order is a serious flaw which makes the order nullity. We note that same view was expressed by the Hon`ble Calcutta High Court in the case of Eastern Commercial Enterprises 210 ITR 103 (Cal), wherein it was held that it is a trite law that cross examination is the sine qua-non of due process of taking evidence and no adverse inference can be drawn against the party unless the party is put on notice of the case made out against him. Therefore, the addition made by the assessing officer, on this score, only, needs to be deleted.
18. We note that the assessee has contended that the addition made by the assessing officer is just based on the excel file data found and seized from the third party. The addition cannot be made without rejecting the audited books of account u/s 145(3) of the Act. We note that no tangible documents, loose papers found during the course of search. So far, the excel sheet is concerned, there is no signature of the assessee as well as authorized partner of M/s Vivan Infraspace LLP. The Assessing Officer one side has observed that perusal of the excel sheet revealed that the assessee- company has not reported entire receipts, as appearing from the seized excel sheet. Matching of entries on the seized excel -sheet found from the third- party with those on the accounting ledger of the assessee and of M/s Titanium Buildcon LLP (developer of the project The City Centre) has no any nexus in the case since the assessee has worked with company, M/s Titanium Buildcon LLP and has no relevance with any document seized in the form of data/transactions recorded in the excel file from third-party. In absence of any instance of transactions being pointed out by the assessing officer, there is nothing for rebuttal by the person receiving such notice from the assessing officer. A person can offer rebuttal with evidence only where the department provides the details of the transactions which they consider to have led to cash receipt by the assessee. Merely comparing the excel sheet found from the third- party with the accounts of assessee- company, will not be an instance to prove that the assessee- company has received cash from the third- party. The well settled legal position is that a non- speaking document without any corroborative material, evidence on record and finding that such document has materialized into transactions giving rise to income of the assessee which had not been disclosed in regular books of account by such assessee, has to disregarded for the purposes of assessments to be framed pursuant to search and seizure action. From the search and seizure perspective, such non speaking seized documents are referred to as “Dump Documents”.
19. Therefore, we find that no arbitrary addition to the income of the assessee can be made by the Assessing Officer based on the dump documents, loose papers containing scribbling, rough/vague notings in the absence of any corroborative material, evidence recorded and finding that such dump documents had materialized into transactions giving rise to income of the assessee, which had not been disclosed in regular books of accounts by the assessee. For that reliance is placed on the judgement of the Hon’ble Supreme Court in the case of K.P. Varghese vs. ITO [1981] 7 Taxman 13/131 ITR 597 held that the fictional receipt cannot be deemed to be receipt in the absence of any cogent material to support the factum of actual receipt. Moreover, the Hon’ble High Court of Delhi in case of CIT vs. D.K. Gupta [2008] 174 Taxman 476 upheld the order of the Tribunal wherein it was held that Ad-hoc/Dumb Documents without any corroborative evidence and finding, that the alleged documents nave materialized into transactions cannot be deemed to be the income of the assessee. The Hon’ble Calcutta Bench of ITAT in case of T.S. Venkatesan v. Asstt. CIT [2000] 74 ITD 298 held that in the absence of corroborative evidence, addition of undisclosed income could not be made simply on the basis of entries on loose papers recovered from the residence of a third- party and certain general statements of said party. Therefore, the well settled legal position is that a non- speaking document referred to as a “Dump Document” without any corroborative material, evidence on record, has to disregarded for the purposes of assessments to be framed u/s 153A and 153C of the Act. The aforementioned legal position also gathers support from the Judgement of the Hon’ble Supreme Court in case of CBI v. V.C. Shukla 1998 taxmann.com 2155 popularly known as Jain Hawala Case wherein it was held that any presumption of transaction on some vague, tenuous and dubious entries in a sheet of paper is not rational and hence legal unless there is corroboration by corresponding entry in regular accounts of both the parties to the transaction. In this case it was held that entries in Jain Notebooks held on facts admissible under section 34, but file containing loose sheets of papers are not “book” and hence entries therein not admissible under section 34 of the evidence Act. Further it was also held in this case that entries in books of account shall not alone be sufficient evidence to charge any person with liability. The above view further gathers reinforcement from the judgment of the Hon’ble Supreme Court in case of Common Cause v. Union of India [2017] 77 taxmann.com 245/245 Taxman 214/394 ITR 220 popularly known Sahara dairies and Aditya Birla diaries case. In this case, the Hon’ble Supreme Court, following the judgment rendered in case of V.C. Shukla (supra), laid down the following principles:
(i) Entries in loose papers/sheets are irrelevant and not admissible under section 34 of the Evidence Act. It is only where the entries are in the books of account regularly kept, depending on the nature of occupation, that those are admissible;
(ii) As to the value of entries in the books of account, such statement shall not alone be sufficient evidence to charge any person with liability, even if they are relevant and admissible, and that they are only corroborative evidence. Even then independent evidence is necessary as to trustworthiness of those entries which is a requirement to fasten the liability.
(iii) The meaning of account book would be spiral notebook/ped but not loose sheets.
(iv) Entries in books of account are not by themselves sufficient to charge any person with liability, the reason being that a man cannot be allowed to make evidence for himself by what he chooses to write in his own books behind the back of the parties. There must be independent evidence of the transaction to which the entries relate and in absence of such evidence no relief can be given to the party who relies upon such entries to support his claim against another;
(v) Even if books of account are regularly kept in the ordinary course of business, the entries therein shall not alone be sufficient evidence to charge any person with liability. It is not enough merely to prove that the books have been regularly kept in the course of business and the entries therein are correct. It is further incumbent upon the person relying upon those entries to prove that they were in accordance with facts;
(vi) The Court has to be on guard while ordering investigation against any important Constitutional functionary, officers or any person in the absence of some cogent legally cognizable material. When the material on the basis of which investigation is sought is itself irrelevant to constitute evidence it is not admissible in evidence.
20. We note that apart from excel sheet, no evidence has been found to suggest that the assessee had actually received the said amount. In the absence of any documentary evidence to suggest the same, it could not be presumed that the amounts reflected in the excel sheet were the income of the assessee, received from RK Group. The Assessing Officer has not brought on record any evidence to suggest that RK Group has admitted that the amounts were paid to the assessee- company. Hence, simply rough noting on the excel file, which is not signed by any party, does not mean that the addition could be made in the hands of the assessee- company. Since no evidence was found relating to the existence of any transaction between the assessee- company and R K Group and in the absence of any corroborative evidence to suggest that the assessee- company had actually received the said amount, no addition could be made merely on the basis of noting excel file found during the search proceedings from third party.
21. We find that no tangible documents, any loose papers found during the courses of search, which contains the signature of the assessee as well as authorized partner of M/s Titanium Buildcon LLP. In Pankaj Dahyabhai Patel (HUF) Vs. ACIT (1999) 63 TT) (Ahm) 790-where papers were not seized from house of the assessee nor was in his handwriting, of the assessee, the inference of on-money receipt based on such paper was not justified. Additions based on loose papers without corroborative evidence, it was held, by Tribunal, to be not sustainable. Neither evidence to link the seized documents found in the premises of third party, that is, R K Group during the course of search, then the presumption u/s 132(4A) of the Act not applicable. The action of the Assessing Officer in making addition based on the searched person`s excel -sheet data, recording of third party, that the same belongs to the assessee, is incorrect, as the same would be clearly impermissible, as the seized data, admittedly, had no nexus with the assessee and there is no signature of assessee or third-party, on such excel sheet. In the case of Addl. CIT v. Miss Lata Mangeshkar [1974] 97 ITR 696 (Bom), the addition was made in the hands of the assessee on the basis of the entries in the books of third persons. Hon’ble Bombay High Court held that such addition could not be made only on the basis of the nothings in the books of third persons. The entire addition revolving to the excel sheet found and seized from the third- party which is “dump documents” which has no legality in the eyes of the law and the addition exclusively based on such documents needs to be deleted.
22. We note that assessee’s issue under consideration is also covered by the judgement of the Hon’ble High Court of Gujarat in the case of PCIT vs. Kaushik Nanubhai Majithia R/Tax Appeal No. 20 of 2024 order dated 06.03.2024, while passing the order the Hon’ble Gujarat High Court has made the following observations:
“1. Having noted the findings of the facts returned by the Commissioner of Income Tax (Appeals) (‘CITA’, in brief) and the Income Tax Appellate Tribunal (‘ITAT’, herein after), we may record that, essentially, the proceedings under Section 153C of the Income Tax Act, 1961 (in short, ‘IT Act of 1961′) were initiated against the Respondent- assessee on the basis of an excel sheet found from the computer of a person, associated with the Company, namely Navratna Organizers and Developers Private Limited (in short as “the Developer’), in the premises of whom the search was conducted.
2. The excel sheet, according to the learned Counsel for the Revenue, contained the details of payment made by the assessee to the developer, with respect to which tax had been paid by the developer before the Settlement Commissioner. The findings returned by the CITA and ITAT on the issue is sought to be assailed on the ground that the payment of tax by the developer, in whose premises search was conducted, before the Settlement Commissioner, with respect to the amount entered in the excel sheet found from the possession of the assistant working with the developer, is sufficient proof of the transaction between the assessee and the developer.
3. We find Inherent fallacy in this submission, inasmuch as, there is no basis for conducting proceedings against the assessee merely for the fact that the developer had paid tax on the amount shown in the excel-sheet There is no adjudication with regard to the payment, which was shown in the excel-sheet to the effect that the same was actually paid by the assessee to the developer. Even otherwise, the concurrent findings written by the CITA and ITAT are that the document found from the premises of the third party namely excel-sheet, which is the basis the proceedings was without any signature and there is no corroborative material to substantia the said document. The nature of the document has not been explained by the Assessing Officer while proceeding against the assessee. The statements of the persons recorded during search with reference to the alleged, seized material, was not provided to the assessee and hence, the entire proceedings under Section 153C of the IT Act of 1961 stood vitiated.
4. Learned Counsel for the petitioner could not successfully demolish the facts, which ai recorded concurrently by the CITA and ITAT.
5. No question of law much less any substantial question of law arises to entertain this appeal. The same is accordingly, dismissed.”
13. As the issue is squarely covered in favour of the assessee by the decision of the Coordinate Bench, of ITAT Rajkot in the case of M/s. RC Buildcon/M/s. RC Heights Pvt. Ltd. (supra), wherein it was held that addition should not be made based on the excel sheet, which was neither signed by the purchaser, nor signed by the seller, and while delivering the judgement, the Tribunal has relied on the judgement of the jurisdictional Hon’ble High Court of Gujarat in the case of Kaushik Nanubhai Majithia R/Tax Appeal No. 20 of 2024 order dated 06.03.2024. Since the issue is covered in favour of the assessee, and there is no change in facts and law and the Revenue is unable to produce any material to controvert the aforesaid findings of the Coordinate Bench (supra). I find no reason to interfere in the said order of the Coordinate Bench (supra), therefore, respectfully following the binding decision of the Coordinate Bench (supra), I delete the addition and allow the appeal of the assessee.
14. In the result, appeal of the assessee is allowed.
Order is pronounced in the open Court on 19/11/2026.





