
Devdarshan Diamonds Private Limited Vs ITO (ITAT Surat)
Accepted Sales Support Diamond Purchases: ITAT Deletes Rs. 4 Lakh Addition Based on Retracted Statement
Summary: The Income Tax Appellate Tribunal, Surat Bench, in Devdarshan Diamonds Private Limited v. Income Tax Officer, ITA No. 1434/SRT/2025, deleted additions concerning Rs. 4 lakh in alleged bogus purchases and Rs. 2,000 in estimated commission. The Tribunal found that the lower authorities had ignored the retraction of the statement relied upon and the evidence establishing purchases corresponding to accepted sales.
The decision, pronounced on 22 October 2026, concerned Assessment Year 2012–13. The Bench comprised Ms. Suchitra Kamble, Judicial Member, and Shri B. M. Biyani, Accountant Member. The appeal was partly allowed, while a separate challenge concerning the absence of a Document Identification Number was dismissed as not pressed.
Background of the Original Assessment
The assessee-company carried on the business of trading in diamonds. It filed its original return on 29 September 2012, declaring total income of Rs. 50,580.
An assessment under Section 143(3) of the Income-tax Act, 1961, was completed on 21 October 2014, determining income at Rs. 1,25,580 after disallowing expenses of Rs. 75,000.
Subsequently, the Department received investigation information concerning M/s Delight Diam Private Limited. The investigation alleged that transactions through that company’s bank accounts were accommodation entries rather than genuine purchases, sales or loans.
The information included a statement by Shri Deepak Babel concerning the provision of accommodation entries. The assessee was identified as a beneficiary.
Reassessment and Additions Made
After recording reasons and obtaining approval from the competent authority, the Assessing Officer issued a notice under Section 148 on 29 March 2019.
The assessee responded by filing a return on 25 April 2019, declaring the same income as in its original return. The reopening reasons were furnished, and its objections were disposed of through a speaking order dated 23 August 2019.
During reassessment, the Assessing Officer issued a Section 133(6) notice to Delight Diam Private Limited, but received no reply.
He added Rs. 4,00,000 as a bogus or sham transaction and estimated commission at 0.5%, resulting in a further Rs. 2,000 addition under Section 69C.
The CIT(A) confirmed the additions, leading to the Tribunal appeal.
Assessee Challenges Reliance on Retracted Statement
The assessee argued that the addition was based on Shri Deepak Babel’s statement, which had subsequently been retracted.
It submitted that no incriminating documents had been found against it and that details of its purchase and sale transactions had been furnished. According to the assessee, these details were ignored by the Assessing Officer and the first appellate authority.
It relied on ACIT v. Krishnaavtar J. Kabra (HUF) and other Tribunal decisions involving similar allegations.
The assessee’s central contention was that a retracted statement could not justify disregarding the documentary record supporting the disputed transactions.
Revenue Supports the Assessment
The Departmental Representative maintained that the assessee had obtained accommodation entries through Delight Diam Private Limited and supported the findings of both lower authorities.
The Revenue relied on CIT v. Kanak Impex, decided by the Bombay High Court, and PCIT v. Surya Impex, decided by the Gujarat High Court.
The Tribunal considered these submissions against the particular facts of the case. Its examination focused on whether the retraction and the relationship between documented purchases and accepted sales had been properly addressed.
Coordinate Bench Decision Considered Relevant
The Tribunal reproduced the reasoning in Krishnaavtar J. Kabra (HUF), which also involved transactions with Delight Diam Private Limited.
In that decision, the Tribunal had noted that the Assessing Officer had not considered the retraction of Shri Deepak Babel’s statement.
The earlier ruling also examined purchases against corresponding sales accepted by the Revenue. It reasoned that accepted sales necessarily involved goods having been purchased, whether from the named supplier or otherwise.
Further, the Revenue had not undertaken the necessary inquiry to establish that the assessee acted merely as a conduit for transferring funds. These factual considerations supported the outcome in that precedent.
Corresponding Sales Supported the Purchases
Applying the coordinate Bench’s reasoning, the Surat Tribunal found that the present assessee had shown sales corresponding to the disputed purchases.
It held that, once sales were accepted and purchases had been established by the assessee, the Revenue could not contradict those purchases on the reasoning adopted by the lower authorities.
The Tribunal also observed that the Assessing Officer relied on the statement without mentioning its subsequent retraction.
These aspects had been ignored by both the Assessing Officer and the CIT(A). The High Court decisions cited by the Revenue were held inapplicable to the present facts.
DIN Ground Not Adjudicated
The assessee had separately challenged the reassessment order for allegedly failing to mention and generate a Document Identification Number, referring to the CBDT circular dated 14 August 2019.
However, its representative did not press this ground. The Tribunal therefore dismissed it without deciding its legal merits.
Final Decision
The Tribunal held that the disputed additions could not survive. Relief extended to the Rs. 4 lakh purchase addition and the connected Rs. 2,000 estimated commission addition.
The appeal was partly allowed, based on the evidentiary record, retraction and accepted corresponding sales.
Cases Discussed
- ACIT Vs Krishnaavtar J. Kabra (HUF) (ITAT Ahmedabad); (2015) 170 taxmann.com 502: Relied upon for the treatment of transactions with Delight Diam Pvt. Ltd., the retracted statement of Shri Deepak Babel and corresponding sales.
- Raj Enterprises Vs DCIT (ITAT Ahmedabad); ITA No. 1166/Ahd/2016; 31/03/2022: Cited by the assessee.
- Grishma Hemanshu Mody Vs CIT(A) (ITAT Mumbai); ITA No. 895/Mum/2023; 25/10/2023: Cited by the assessee and discussed in the quoted coordinate Bench order.
- Smt. Pooja Jain L/H of Late Shri Gautam Bhanwarlal Jain Vs DCIT (ITAT Mumbai); ITA Nos. 885 to 891/Mum/2019; 31/03/2023: Cited by the assessee.
- CIT Vs Kanak Impex (Bombay High Court); ITA No. 791 of 2021; 03/03/2025: Relied upon by the Revenue but found inapplicable to the facts.
- PCIT Vs Surya Impex (Gujarat High Court); (2023) 451 ITR 395: Relied upon by the Revenue but found inapplicable to the facts.
- Siddheshwar Impex Pvt. Ltd. (ITAT Mumbai); ITA No. 153/Mum/2024: Discussed in the quoted coordinate Bench decision.
FULL TEXT OF THE ORDER OF ITAT SURAT
The appeal filed by the assessee is against the order passed by the Commissioner of Income Tax (Appeals), ADDL/JCIT, Mumbai [in short “CIT(A)”] dated 22.11.2025 for the Assessment Year (in short “AY”) 2012-13.
2. The assessee has raised the following grounds of appeal:
“1. Whether on the facts and circumstances of the case, the Learned Commissioner of Income Tax – (Appeals) was justified in affirming the addition made by Learned Assessing Officer, solely based on the statement of Shri Deepak Babel which was later retracted, specifically in the light of the judicial precedents laid down by Hon’ble jurisdictional Surat ITAТ.
2. Whether on the facts and circumstances of the case, the assessment order passed by the learned Assessing Officer dated 29.11.2019 in instant case, in contravention of the CBDT circular dated 14.08.2019, i.e. without mentioning and generating DIN in the assessment order, is valid in law.
3. Whether on the facts and circumstances of the case, the Learned Commissioner of Income Tax – (Appeals) was justified in affirming the addition of Rs. 4,00,000 made by the Learned Assessing Officer, to the income of the appellant, on account of bogus purchases made from M/s Delight Diam Private Limited.
4. Whether on the facts and circumstances of the case, the Learned Commissioner of Income Tax – (Appeals) was justified in affirming the addition of Rs. 2,000 made by the Learned Assessing Officer to the income of the appellant under section 69C of the Act on account of commission paid for obtaining the aforesaid accommodation entry.”
3. During the year under consideration, assessee was engaged in trading of diamonds. The assessee company filed original return of income for A.Y. 2012-13 on 29.09.2012 declaring total income at Rs.50,580/-. Assessment proceedings u/s. 143(3) of the Income Tax Act, 1961 (in short “the Act”) were finalized on 21.10.2014 at Rs. 1,25,580/- by disallowing various expenses to the tune of Rs.75,000/-. As per information, investigation report based on documentary evidences and statement of director i.e. Shri Deepak Babel, concluded that the company, M/s. Delight Diam P. Ltd. was having several bank accounts in different banks and all the credit & debit transaction in the said bank accounts are not in the nature of real transactions of purchase & sale or loans. Further, the director stated that his company was indulged in providing accommodation entry. The assessee was one of the beneficiaries which availed accommodation entry from M/s. Delight Diam P. Ltd. Accordingly, after recording reasons for reopening for AY 2012-13 and obtaining approval from the Competent Authority, the case of the company was reopened for A.Y. 2012-13 by issuing notice u/s. 148 of the Act dated 29.03.2019. In response to notice u/s. 148 of the Act, the assessee filed return of income on 25.04.2019 declaring total income at Rs. 50,580/-. The reasons for reopening of the assessment were provided to the assessee. The objections filed by the assessee against the reopening of the assessment were disposed of by passing speaking order on 23.08.2019. The assessee filed reply to show cause notice dated 21.11.2019. During the reopening proceedings, notice u/s. 133(6) of the Act was issued to M/s. Delight Diam P. Ltd. to examine the facts of the case, but no reply was received. The Assessing Officer made addition of Rs.4,00,000/- as bogus/sham transactions. Further, the Assessing Officer held that to obtain this accommodation entry of share capital & share premium, the assessee incurred expenses in the nature of commission @ 0.5% on total accommodation entry received. The said commission @ 0.5% i.e. Rs.2,000/- was treated as unexplained expenditure u/s. 69C of the Act.
4. Being aggrieved by the assessment order, the assessee filed appeal before CIT(A). The CIT(A) dismissed the appeal.
5. The Ld. Authoritised Representative (in short “the Ld. AR”) submitted that the addition is solely based on the statement of Shri Deepak Babel which was later retracted, specifically in the light of the various judicial precedents. The Ld. AR relied upon following decisions:
i) ACIT vs. Krishnaavtar J. Kabra (HUF) (2015) 170 taxmann.com 502 (Ahd.-Tri.)
ii) Raj Enterprises vs. DCIT (ITA No. 1166/Ahd/2016 A.Y. 2009-10 order dt. 31.03.2022)
iii) Grishma Hemanshu Mody vs. CIT(A) (ITA 895/Mum/2023 order dt. 25.10.2023)
iv) Smt. Pooja Jain L/H of Late Shri Gautam Bhanwarlal Jain vs. DCIT (ITA Nos. 885 to 891/Mum/2019 order dt. 31.03.2023)
The Ld. AR submitted that no incriminating documents were found against the assessee. In fact, retracted statement does not have evidentiary value as the assessee provided the details of its transactions of purchase and sale which were totally ignored by the Assessing Officer and the CIT(A). In fact, the sale made by M/s. Delight Diam Pvt. Ltd. was found genuine as held by the Tribunal in case of Krishnaavtar J. Kabra HUF (supra). The Ld. AR did not press ground no. 2.
6. The Ld. Departmental Representative (in short “Ld. DR”) relied upon the Assessment Order and order of the CIT(A). The Ld. DR also emphasized that the bogus purchase by the assessee and the assessee is a beneficial of accommodation entry in respect of the business conducted by M/s Delight Diam Pvt. Ltd. The Ld. DR relied upon the decision of Hon’ble Bombay High Court in case of CIT vs Kanak Impex (ITA No. 791 of 2021 order dt. 3.3.2025) & decision of Hon’ble Gujarat High Court in case of PCIT vs. M/s Surya Impex (2023) 451 ITR 395.
7. We have heard both the parties and perused all the relevant material available on record. Gr. No. 2 is not pressed hence dismissed. As regards Ground No. 1, 3 & 4, the Ld. AR submitted that the addition is based on statement which was retracted. From the perusal of record, it is clearly mentioned in para 5.4 of the assessment order that “Since, from the statement recorded on oath of Shri Deepak Kailash Kabra Babel, director of assessee company, it was established that M/s. Delight Diam Pvt. Ltd. was involved in accommodation entry.” But the said statement was later on retracted, this fact was not mentioned by the Assessing Officer. Besides that, the decision submitted by the Ld. AR that of Ahmedabad Tribunal in case of Krishnaavtar Kabra (supra) the Tribunal held as under:
“10. We have heard the arguments of both the parties and perused the records. The undisputable facts emanate from the records before us are that Shri Deepak Babel has given a statement on 05.08.2018 about the nature of accommodation entries provided and retracted the same on 28.03.2018 before the Revenue Authorities. This fact has not been considered by the Assessing Officer or mentioned anywhere in the proceedings taken up by the Revenue Authorities. Further, it is an undisputable fact that the assessee has received amounts from two entities, namely M/s. Isabelle Tours N Travels and M/s. Shreeji Overseas (I) Pvt. Ltd., against the diamonds sold. It cannot be expected that these two entities have paid amounts to the assessee without receiving any goods – whether it be diamonds or otherwise. Hence, such diamonds have been duly purchased from M/s. Delight Diam Pvt. Ltd. Even if the argument is considered, there were certain goods which were purchased by the assessee for Rs.3.53 crores which in turn have been sold to two entities at Rs.3.56 crores, then this leads to a situation where the Revenue has accepted the sales and, as a natural corollary, there have been purchases – whether from M/s. Delight Diam Pvt. Ltd. or any other parties. If there were no purchases, then there would be no corresponding sales; then the income of the assessee will be reduced as there is some margin towards the sales and purchase difference and the same has to be taken as profit. But, in a situation where the corresponding sales have been accepted, it cannot be said that there were no purchases.
11. In the instant case, the issue of cross-examination does not arise as the assessee has also not attended the office of the Revenue Authorities, though Shri Deepak Babel has also not attended on the said date. In case both the purchase and sales have been treated as bogus, then the difference amount of Rs.2,81,914/- is to be treated as the amount earned by the assessee after receiving the money from two parties namely M/s. Isabelle Tours N Travels and M/s. Shreeji Overseas (I) Pvt. Ltd., and sending it to a third party namely M/s. Delight Diam Pvt. Ltd. In that way, the assessee is acted as a conduit for transferring money through his account. The Revenue has failed to undertake any inquiry to prove that the assessee is operating as a conduit for transfer of money to various persons. The Revenue has also not disputed that the sales parties were bogus to buttress the arguments that the assessee is acting as a conduit for transfer of money. The Assessing Officer has held that the assessee has inflated the purchases by taking accommodation entries to reduce the legitimate tax liability (para 4.5 of the AO). If that is the case, the contention of the Assessing Officer cannot be accepted that, in order to sell goods worth Rs.3.56 crores the assessee has inflated the purchases by Rs. 3.51 crores. Further, we find that there was a total of 10 transactions entered by the assessee with regard to the sale and purchase of goods. All the 10 transactions involved selling of goods/diamonds which has been purchased and the details are as under:-
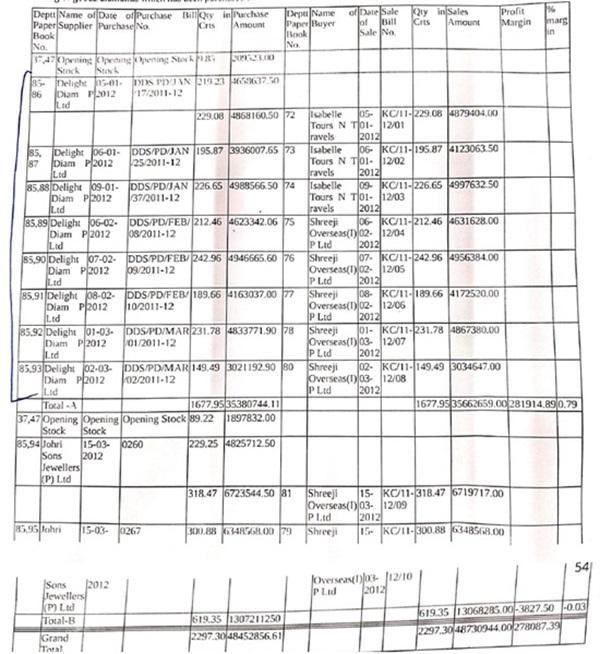
12. Hence, keeping in view the facts before us and the order of the Co-ordinate Bench of the Tribunal in the case of Grishma Hemanshu Mody Vs. CIT(A) in ITA No. 895/Mum/2023 (supra), and in the case of Siddheshwar Impex Pvt. Ltd. in ITA No. 153/Mum/2024 wherein the issue of bogus purchases pertaining to M/s. Delight Diam Pvt. Ltd. involving Shri Deepak Babel have been adjudicated, we decline to interfere with the order of the Ld. CIT(A).
13. In the result, the appeal of the Revenue is dismissed.”
Thus, it is clearly the identical facts as the director of assessee’s company retraction was taken on record and finding to that extent was given. Therefore in present case, the assessee company has shown corresponding sale to the purchases and once sales accepted the revenue cannot contradict purchase which was established by assessee. These aspects were totally ignored by the AO & CIT(A). The decision relied by Ld. DR of the Hon’ble High Court will not be applicable in present facts of the case. Thus, the addition does not sustain.
8. In result appeal of the assessee is partly allowed.
Order pronounced in the open court on 22.10.2026



