H.I. International Vs Himanshu Verma (GSTAT Lucknow)
Summary: GSTAT Lucknow allowed H.I. International’s appeal against an order restoring its GST registration subject to depositing ₹26,26,000 in cash within seven days, with an automatic-void clause for non-compliance. The appellant, engaged in chemicals and leather fittings, faced cancellation of registration by an order dated 19 May 2026 following a show cause notice dated 30 April 2026 alleging non-existence at its declared business premises. During the first appeal, re-inspection negated that ground. The First Appellate Authority accordingly set aside the cancellation but attached the cash-deposit condition concerning disputed ITC from four suppliers, referring to the appellant’s affidavit expressing willingness to reverse the credit.
The appellant argued that the cancellation appeal could not be converted into an ITC-demand proceeding without the prescribed notice, adjudication and hearing. It disputed mandatory payment in cash, submitted that its willingness to reverse ITC was subject to verification, and pointed to the absence of supplier-wise or invoice-wise examination of the transactions. It also contended that cancellation did not extinguish tax liabilities, but that this did not authorise the appellate authority to impose an otherwise unauthorised recovery condition. Alternatively, it sought reversal through the electronic credit ledger to the extent available and within a reasonable period. The Department maintained that the condition arose from the appellant’s undertaking and was attached to restoration rather than constituting an independent adjudication of ITC liability.
The Tribunal found that the notice concerned non-existence of the business, whereas the original cancellation order relied on alleged wrongful ITC from suppliers whose registrations had been cancelled. The original order therefore travelled beyond the notice. Referring to Section 75(7) and the provisos to Section 107(11), it held that the appellate authority could confirm, modify or annul the challenged order but could not depart from the statutory procedure. Determination of disputed ITC required separate proceedings, investigation, notice and a meaningful opportunity to contest the allegations. A conditional admission or an averment in an affidavit could not substitute legal requirements without proper examination.
The Tribunal further held that no notice had been given before imposing the cash-payment condition and that the resulting ITC demand violated the GST legislation and principles of natural justice. It declared the orders of both the adjudicating authority and the First Appellate Authority null and void, allowed the appeal and revoked the cancellation of registration. The respondent remained at liberty to initiate proceedings de novo to protect the Revenue. The decision therefore removed the impugned cancellation and cash condition without finally determining the appellant’s substantive entitlement to the disputed ITC.
Cases Discussed
- M/s Shyam Sundar Sita Ram Traders Vs State of U.P. — Allahabad High Court, decided 20 March 2023. The appellant relied on this decision to submit that cancellation must remain within Section 29(2) and that ITC irregularities must be addressed through the appropriate statutory machinery.
- M/s Saboo Tor Pvt. Ltd. Vs State of Himachal Pradesh — Himachal Pradesh High Court. The appellant cited this decision for a reasoned order and meaningful consideration of the taxpayer’s reply and supporting documents.
FULL TEXT OF THE ORIGINAL GSTAT JUDGMENT/ORDER
1. BRIEF FACTS OF THE CASE
1.1 The Appellant is a registered taxable person under the UPGST Act, 2017 bearing GSTIN: 09ABIPF6765A1ZQ, engaged in the business of chemicals and leather fittings. Its GST registration was cancelled vide order dated 19.05.2026, pursuant to SCN dated 30.04.2026 issued under Rule 21(a) of the UPGST Rules, 2017. Aggrieved by the cancellation, the Appellant preferred an appeal under Section 107 of the UPGST Act, 2017. During the appellate proceedings, a re-inspection of the business premises was conducted and the Appellant also filed an affidavit expressing willingness to reverse the disputed ITC.
1.2 The First Appellate Authority, vide Order-in-Appeal dated 20.07.2026, set aside the cancellation and directed restoration of registration, subject to deposit of Rs.26,26,000/- in cash within seven days, failing which the order to become void. Aggrieved by the cash-deposit condition and the consequential automatic-void clause, the Appellant has preferred the present appeal, contending that the First Appellate Authority travelled beyond its statutory jurisdiction and imposed a condition without following the prescribed procedure.
1. SUBMISSIONS OF THE APPELLANT
2.1 The appellant submitted that the Order-in-Appeal dated 20.07.2026, while setting aside the cancellation of registration and directing restoration thereof, has illegally imposed a condition requiring deposit of Rs.26,26,000/- in cash within seven days, coupled with an automatic-void clause in the event of non-compliance. Such a condition is beyond the statutory powers conferred upon the Appellate Authority under Section 107 of the SGST/CGST Act 2017. Section 107(11) empowers the Appellate Authority to confirm, modify or annul the order under appeal, but does not confer any independent or residuary power to impose a cash-deposit condition as a pre-condition for restoration of registration. Neither the SGST/CGST Act 2017 nor the Rules prescribe such a condition in registration-cancellation appeals.
2.2 The appellant submitted that the question of directing a cash deposit of Rs. 26,26,000/- was never put to it during the appellate proceedings. The Appellant had only furnished an affidavit expressing willingness to return/reverse the disputed ITC, subject to verification. No opportunity was afforded to the Appellant to address the specific issue of mandatory cash payment, its mode, quantum, or feasibility. The impugned condition was therefore imposed without an effective opportunity of hearing and is violative of the principle of audi alteram partem.
2.3 The appellant submitted that the statutory framework provides mechanisms for reversal/payment of wrongly availed ITC through the prescribed GST system, including the return mechanism and Form DRC-03, subject to the applicable provisions. There is no general statutory mandate that every ITC reversal must necessarily be made by a separate cash deposit, to the exclusion of available eligible credit.
2.4 The original proceedings arose out of cancellation of registration under Rule 21(a), and the First Appellate Authority itself found, on the basis of the re-inspection report, that the principal ground of non-existence at the declared place of business was not established. The appellant submitted that determination of the substantive eligibility or otherwise of ITC is a separate matter governed by the statutory provisions relating to determination of tax/ITC liability and cannot be conclusively adjudicated as a condition in a registration-cancellation appeal without the prescribed notice and adjudicatory process.
2.5 The Appellant relied upon Section 75(7) of the SGST/CGST Act, which prohibits confirmation of demand on grounds other than those specified in the notice. The appellant submitted that the same principle reinforces the requirement that an authority must act within the jurisdiction and statutory framework of the proceedings before it. The cancellation proceedings cannot be converted into an independent ITC-demand proceeding.
2.6 The disputed ITC of Rs.26,26,000/- relates to transactions with four suppliers. The appellant submitted that the impugned order does not contain a proper invoice-wise or supplier-wise determination regarding the genuineness of the underlying transactions, payment of consideration, movement of goods, e-way bills, banking transactions, or the status of the suppliers at the relevant time. Consequently, directing reversal of the entire amount as a pre-condition for restoration was premature.
2.7 The Appellant does not dispute that cancellation of registration does not extinguish statutory tax liabilities. However, Section 29(3) cannot itself be treated as conferring jurisdiction upon the Appellate Authority to determine an ITC liability or prescribe a mode of recovery which is otherwise not authorised by the Act.
2.8 The Appellant relies, inter alia, upon M/s Shyam Sundar Sita Ram Traders v. State of U.P. (Allahabad High Court, 20.03.2023), for the proposition that cancellation of registration must remain within the statutory grounds prescribed under Section 29(2), and that ITC-related irregularities are to be dealt with under the appropriate statutory machinery. The Appellant also relies upon M/s Saboo Tor Pvt. Ltd. v. State of Himachal Pradesh for the requirement of a reasoned order and meaningful consideration of the taxpayer’s reply and supporting documents.
2.9 The appellant submitted that making restoration of registration conditional upon immediate payment of the entire disputed ITC amount of Rs.26,26,000/- is excessive and disproportionate, particularly when the Appellate Authority had already found the principal ground for cancellation to be unsustainable. The automatic-void clause further operates harshly by providing for automatic cessation of the appellate relief without any subsequent notice or opportunity of hearing.
2.10 The appellant submitted that the impugned condition also raises issues under Articles 14 and 19(1)(g) of the Constitution, as it places an onerous and arbitrary restriction on the Appellant’s ability to carry on business despite restoration of registration. The Appellant further relies upon Article 265 in contending that collection of any tax must have statutory authority.
2.11 The Appellant therefore prayed that the cash-deposit condition of Rs.26,26,000/- and the automatic-void clause contained in the Order-in-Appeal dated 20.07.2026 be set aside, while retaining the finding quashing the cancellation and restoring the Appellant’s GST registration. Alternatively, the condition may be suitably modified to permit compliance through the statutory ITC reversal/payment mechanism within a reasonable period.
3. CONTENTION OF THE RESPONDENT
3.1 The Respondent submits that the contention of the Appellant that the First Appellate Authority travelled beyond the scope of the Show Cause Notice is not sustainable. The Show Cause Notice was issued for cancellation of the Appellant’s registration, and the First Appellate Authority, while considering the appeal against such cancellation, exercised its appellate jurisdiction under Section 107 of the UPGST Act, 2017.
3.2 The condition requiring deposit of Rs.26,26,000/- was not imposed by the First Appellate Authority as an independent adjudication or confirmation of any fresh ITC demand. Rather, the said condition was attached to the restoration of the cancelled registration, in view of the Appellant’s own undertaking/admission regarding reversal/return of the disputed ITC.
Thus, the impugned direction is required to be viewed as a condition for restoration of registration and not as a determination of the substantive eligibility or liability of the Appellant in respect of the disputed ITC. The First Appellate Authority had already set aside the cancellation and granted the Appellant the benefit of restoration, subject to compliance with the condition prescribed in the Order-in-Appeal.
3.3 Accordingly, the plea that the First Appellate Authority adjudicated an ITC dispute beyond the scope of the Show Cause Notice is misconceived. The condition was consequential to and inseparably connected with the relief of restoration of registration and did not amount to a separate adjudication of ITC liability.
4. ISSUES FOR DETERMINATION
Whether the First Appellate Authority had jurisdiction under Section 107 of the UPGST Act to impose such a condition in restoring registration subject to payment of Rs.26,26,000/- in cash and whether the automatic-void clause attached to non-payment within seven days is legally sustainable under law?
4.1 Whether the impugned condition violates the principles of natural justice?
4.2 Whether on the grounds of SCN, Order of Adjudicating Authority is sustainable.
There is a question of law involved, hence the Division Bench heard this case.
5. Heard Both the Parties and perused the record.
6. FINDINGS
Issue No. 1
6.1 The Appellant has contended that the First Appellate Authority had no jurisdiction under Section 107 to restore the registration subject to payment of Rs.26,26,000/- and to provide for an automatic-void clause in case of non-compliance.
6.2 The Show cause notice was issued for the cancellation of Registration for non-existence on verification not for wrong availment of ITC.
As per Section 75(7) of CGST/SGST Act 2017
“(7) The amount of tax, interest and penalty demanded in the order shall not be in excess of the amount specified in the notice and no demand shall be confirmed on the grounds other than the grounds specified in the notice.”
6.3 This Bench finds that the Proper Officer neither raised any demand in the Show Cause Notice nor discussed any allegation regarding the demand of tax or the wrongful availment of Input Tax Credit (ITC). It is pertinent to mention that the crux of the Show Cause Notice was the alleged non-existence of the registered firm and the consequent cancellation of registration, and not the alleged wrongful availment of ITC. However, the Proper Officer proceeded to pass the Order-in-Original on an entirely new & different ground of wrongful availment of ITC and cancelled the registration with retrospective effect. Such an order, having been passed beyond the scope and allegations contained in the Show Cause Notice, is legally unsustainable and bad in law.
6.4 Further, this Bench finds that the First Appellate Authority passed the order dated 20.07.2026 proceeding to hold that the Input Tax Credit (“ITC”) amounting to Rs.26,26,000/- availed from the four vendors was liable to be reversed. Without doubt such a determination, travels entirely beyond the subject matter and scope of the proceedings arising from the appeal against cancellation of registration. The determination of ITC entitlement is a distinct and substantive adjudicatory proceeding, governed by Sections 73 and 74 of the CGST Act, which contemplate the issuance of a notice in Form DRC-01 (or, where applicable, DRC-01A), followed by adjudication by the proper officer and a specific and meaningful opportunity to the taxpayer to contest the allegations and place relevant evidence on record. In the present case, none of these mandatory procedural safeguards were followed. Consequently, the impugned finding directing reversal of ITC could not have been rendered in proceedings concerning cancellation of registration.
As per Section 107(11) of CGST/SGST Act 2017-
(11) The Appellate Authority shall, after making such further inquiry as may be necessary, pass such order, as it thinks just and proper, confirming, modifying or annulling the decision or order appealed against but shall not refer the case back to the adjudicating authority that passed the said decision or order:
Provided that an order enhancing any fee or penalty or fine in lieu of confiscation or confiscating goods of greater value or reducing the amount of refund or input tax credit shall not be passed unless the appellant has been given a reasonable opportunity of showing cause against the proposed order:
Provided further that where the Appellate Authority is of the opinion that any tax has not been paid or short-paid or erroneously refunded, or where input tax credit has been wrongly availed or utilised, no order requiring the appellant to pay such tax or input tax credit shall be passed unless the appellant is given notice to show cause against the proposed order and the order is passed within the time limit specified under section 73 or section 74 4[or section 74A].
6.7 In the present case, the condition was imposed while granting restoration of registration was the registration connected or with the disputed ITC. As the SCN dated 30.04.2026 was issued on the basis of non-existence of the firm on site verification and Order in Original was passed by the Proper Officer on 19.05.2026, wherein the Proper Officer passed an Order discussing the facts of Wrong availment of ITC from the supplier whose registrations were cancelled.
6.8 The Bench holds that The First Appellate Authority has jurisdiction to modify, annul and confirm the impugned order which has been challenged but cannot travel beyond without following the procedure established by law. There is clear violation of provisos of Section 107 (11) and Section 75(7) of CGST/SGST Act 2017 Admission must be conclusive in nature. Conditional admission or simple averment in affidavit cannot substitute the law without proper examination. Order must be justified within the four corners of the Act. The impugned order of First Appellate Authority regarding deposition of 26 lakhs rupees within seven days is not sustainable in the eye of law.
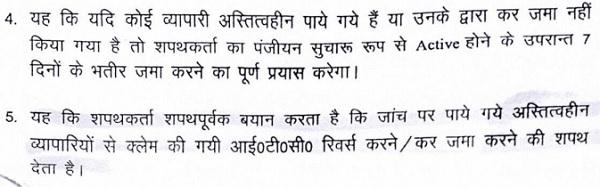
6.9 Before the First Appellate Authority. The Appellant had itself furnished an affidavit expressing willingness to reverse the disputed ITC, subject to verification. The appellant specifically stated in the para 4& 5 of his affidavit, which is being reproduced below-
Issue No. 2
7. The appellant filed written submission on 29.09.2026 onto the portal and made the following prayers, which are reproduced below-
“(a)Set aside and quash the cash-deposit condition and the automatic-void clause in the Order-in Appeal (Form GST APL-04) dated 20.07.2026, thereby leaving intact that part of the OIA which quashes the Original Cancellation Order and restores the Appellant’s registration, and to declare that the restoration is unconditional and subsisting;
(b) In the alternative, and without prejudice to prayer (a) above, modify the impugned condition by directing the Appellant to reverse the disputed ITC of Rs.26,26,000/- through the Electronic Credit Ledger to the extent of the balance available and in reasonable period as this Hon’ble Tribunal may fix, with the Appellant’s registration being protected from cancellation during the period of compliance.”
7.1 This Bench finds that though the Appellant submitted an affidavit for submission of repayment of wrongly availed ITC. But it is another issue to be determined by issuing another Show Cause Notice to the Appellant by the Proper Officer with a proper investigation with detailed inquiry in this subject matter to safeguard the Revenue.
7.2 The First Appellate Authority should not impose condition which was not in SCN or OIO unless the appellant is given notice to show cause against the proposed amount of tax under section 107 of GST and the order is passed within the time limit specified under section 73 or section 74 4[or section 74A]. The impugned order does not show that any notice was given to appellant before imposing condition of cash or tax. Effective and meaningful opportunity must be given before imposing any tax or penalty. Imposing tax without affording opportunity is clear violation of principles of natural justice. If there is wrong availment of ITC by Appellant there will interest and penalty also under law. Maxim audi alteram partem is touch stone of principal of natural justice. Notice was not given by First Appellate Authority to appellant hence demand of Rs. 26,26,000/any such ITC demand is void and violative not only the provisions of GST Act 2017 but also principles of natural justice.
Issue no 3
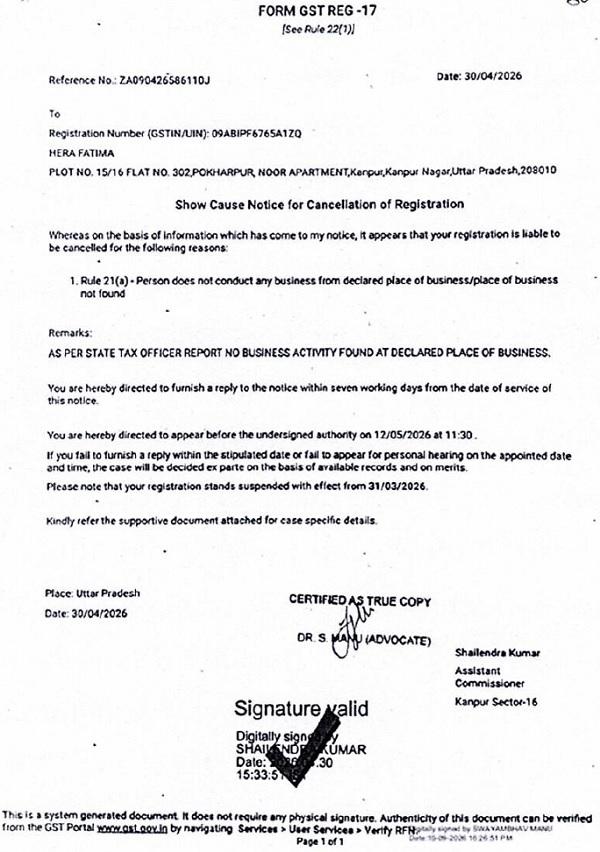
8. For this issue the Show Cause Notice and OIO both are important to discuss, which are produced below-
–
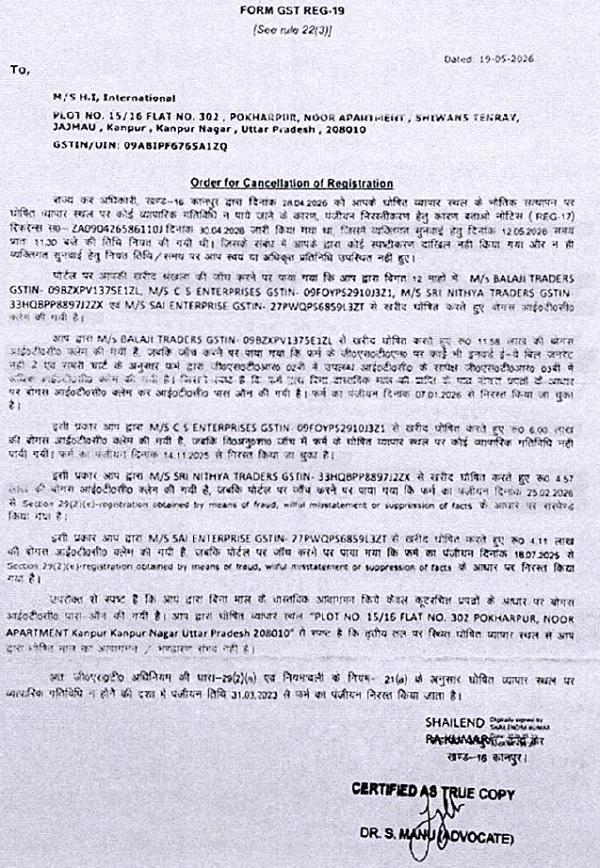
8.1 The Case before this Tribunal regarding the cancellation of the Registration of the Appellant. The Show cause notice was issued for the cancellation of Registration for non-existence on verification and not for wrong availment of ITC. the Order in Original passed by proper officer shows that Appellant firm availed wrong ITC from four firms whose registration numbers have been cancelled by department. That is not in consonance with SCN, which mentioned there is no work place hence registration is cancelled whereas OIO endorses wrong availment of ITC. If there is wrong availment of ITC how it can be said that there is no place of work, grounds of SCN and grounds in OIO; both are two apparently different and contradictory, they are not cohesive to each other.
8.2 Therefore, this Bench holds that the Order passed by the First Appellate Authority and the Order passed by the Adjudicating Authority stands null & void.
9. Order
(i) The Appeal is allowed. The cancellation of registration is hereby revoked. The respondent is at liberty to initiate the proceedings de novo to protect the revenue. Copy of this order be communicated to the Commissioner of State Goods and Services Tax, Lucknow for necessary action.
The Order is pronounced in Open Court.