
ITO Vs Nihal Khandelwal (ITAT Jaipur)
The Income Tax Appellate Tribunal, Jaipur Bench, dismissed the Revenue’s appeal against deletion of additions aggregating to ₹5,21,64,013 concerning unexplained money and alleged unexplained import expenditure.
The Tribunal upheld the finding that a party’s returned income alone does not determine its capacity to advance business funds. It also accepted documentary evidence establishing that the alleged difference in import purchases arose from incorrect invoice values reported in CBIC data, rather than unexplained expenditure by the assessee.
Background of the Case
The assessee, Nihal Khandelwal, traded in gemstones and jewellery under the name KGS Gems.
His return for assessment year 2022-23 was selected for scrutiny because export-import information reflected high-value imports. The Assessing Officer examined the genuineness of purchases and the sources used to finance them.
The officer rejected the explanation concerning funds received from different concerns, holding that their creditworthiness had not been established. An addition of ₹1,82,63,955 under section 69A followed.
Separately, the officer compared recorded purchases of ₹1,82,63,955 with imports of ₹5,21,64,013 appearing in the CBIC information. The resulting difference of ₹3,39,00,058 was added under section 69C.
The CIT(A), National Faceless Appeal Centre, Delhi, deleted both additions through an order dated 26 December 2025. The Revenue challenged that relief.
Revenue Questions Creditworthiness
The Revenue argued that the income declared by the parties did not justify the amounts advanced. It also submitted that transactions through banking channels do not, by themselves, establish genuineness.
The disputed dealings involved concerns associated with the assessee’s brother, mother and father’s HUF.
The assessee had furnished income-tax return acknowledgements, computations, bank statements and account confirmations. He also explained the credit entries in the parties’ bank accounts.
The CIT(A) found that the Assessing Officer had not identified suspicious cash deposits preceding the transfers or other doubtful credits supporting an adverse inference.
Ledger Accounts Showed the Nature of Receipts
The CIT(A)’s examination revealed that Chantaburi Ruby Jewels Expo was a debtor, with an opening debit balance of ₹7,87,000 and a closing debit balance of ₹54,37,000.
The ₹19 lakh received from that concern represented settlement of funds earlier advanced by the assessee. It could not therefore be treated simply as unexplained money received from an unproven lender.
Similarly, Jai Paplaj Mata Exports had an opening debit balance of ₹10 lakh. The appellate authority found that the receipts from that concern also represented settlement of amounts advanced.
With Shree Gordhan Gems, the assessee maintained a running account involving both receipts and payments.
These findings required the transactions to be evaluated in their commercial context rather than solely against the parties’ annual taxable income.
Returned Income Was Not the Sole Test
The Bench, comprising Judicial Member Kuldip Singh and Accountant Member Prakash, agreed that business funds could be advanced and received to meet commercial requirements without a direct correlation to returned profits.
It noted that a business could have funds available even where its profit was nil.
Importantly, there was no finding of cash deposits, round-tripping or doubtful credit entries establishing that the transfers were accommodation transactions.
The Tribunal therefore found no reason to interfere with deletion of the section 69A addition. Its conclusion rested on the ledger and banking evidence, rather than banking-channel transfers alone.
Import Difference Traced to CBIC Reporting Error
The section 69C dispute concerned imports from Radhey Gems & Jewellery Limited and Sambhav Gems Co.
The CIT(A) examined the bills of entry, assessable values and customs payments. The assessable values were ₹88,72,727 and ₹96,94,961, respectively.
Customs payments of ₹71,104 and ₹77,693 corresponded with those values. The figures did not support the substantially higher invoice amount appearing in the departmental information.
The assessee also produced a certificate dated 17 April 2024 from the Assistant Commissioner of Customs, Air Cargo Complex, Sanganer, Jaipur.
That certificate confirmed invoice values of ₹85,48,173 and ₹92,74,351 for the relevant imports, together with the corresponding assessable values.
Tribunal Accepts Customs Confirmation
The Tribunal independently examined the Customs certificate and accepted that it supported the assessee’s recorded purchases.
It agreed that the purchase figures were consistent with the import invoice values and taxes paid. Consequently, the alleged discrepancy reflected misreporting in the CBIC information, rather than expenditure omitted from the books.
Although the Revenue also raised an objection concerning additional evidence and absence of a remand report under Rule 46A, the Tribunal upheld the appellate findings without laying down a separate general ruling on that procedure.
Conclusion
The Revenue’s appeal was dismissed, preserving deletion of both additions.
The decision underscores the need to examine actual account movements, available funds and primary import documents before drawing adverse conclusions. Here, the evidence contradicted both the assumption of insufficient funding capacity and the alleged excess import expenditure.
FULL TEXT OF THE ORDER OF ITAT JAIPUR
The Appellant, Income Tax Officer by filing the present appeal, sought to set aside the impugned order dated 26.12.2025 passed by the National Faceless Appeal Centre (NFAC), Delhi [hereinafter referred to as the ‘CIT(A)’] qua assessment year 2022-23 on the grounds inter-alia that:-
“1. Whether on the facts and in the circumstances of the case and in law, the ld. CIT(A) is justified in holding that there is no material to doubt the creditworthiness of the parties from whom the assessee has taken unsecured loan totalling to Rs. 1,82,63,955/- ignoring the fact the income declared by the lenders does not commensurate with the unsecured loan advanced?.
2. Whether on the facts and in the circumstances of the case and in law, the ld. CIT(A) is justified in ignoring the fact the mere transaction through banking channel does not make a transaction genuine in spite of the fact that the assessee failed to prove the creditworthiness of the person from whom the assessee raised the unsecured loan?
3. Whether on the facts and in the circumstances of the case and in law, the ld. CIT(A) is deleting the addition of Rs. 5,21,64,013/- by ignoring the fact that the assessee has not provided any justification during assessment proceeding before the AO about the misreported invoice totalling to Rs. 3,34,47,528/- (i.e. Rs. 52015216-18567688) by the CBIC to the department and in this regard certificate/invoice has not been sent to verification to the jurisdictional AO?
4. Whether on the facts and in the circumstances of the case and in law, the ld. CIT(A) is justified in deleting the total addition of Rs. 5,21,64,013/- and admitting the additional evidences by ignoring the fact that no remand report has been called for from the AO under Rule 46A of the Income Tax Rules, 1962?
5. The appellant craves leave to add, alter, amend, or withdraw any of the above Grounds of appeal at or before the time of hearing of the appeal.”
2. Briefly stated, facts necessary for consideration and adjudication of the issues at hand are : Assessee is engaged in the business of trading of gem stones and jewellery in the name and style of M/s KGS Gems. The return of income filed by him was subjected to scrutiny for the reasons that large value of imports were shown in export import data. In order to verify the source of investment and genuineness of the purchases, the Assessing Officer has not accepted the explanation given by the assessee that sources of purchase was by raising unsecured loan from different concerns on different dates on the ground that the assessee has failed to prove the creditworthiness of the unsecure creditors and thereby made addition of Rs. 1,82,63,955/- u/s 69A of the Income Tax Act, 1961 (hereinafter referred to as the “Act”). It was also noticed that purchases by the assessee in the form of imports were to the tune of Rs. 5,21,64,013/-. On failure of the assessee to reconcile difference of Rs. 5,21,64,013/- on account of purchases shown by the assessee and appearing in CBIC Data proceeded to make further addition of Rs. 3,39,00,058/-u/s 69C of the Act and thereby made addition by framing assessment u/s 143(3) r.w.s. 144B of the Act.
3. Assessee carried the matter before the Ld. CIT(A) by way of filing appeal, who has deleted the addition by allowing the appeal filed by the assessee. Being aggrieved with the impugned order passed by the Ld. CIT(A), Revenue has come up before the Tribunal by way of filing the present appeal.
4. Ld. DR for the Revenue by relying upon the order passed by the Assessing Officer contended that when the unsecured creditors were not in a position to lend heavy loan to the assessee as is evident from their returns of income, the impugned order is liable to be set aside.
5. We have heard Ld. ARs for the assessee and Ld. DR for the Revenue and perused the record available on file.
6. On ground Nos. 1 and 2, we have perused the impugned order passed by Ld. CIT(A), who has, after considering the submissions made by the assessee and documents brought on record, proceeded to delete the addition by returning following findings as under:-
“4.1.1 Ground No. 1:-Vide this ground, the appellant has questioned the addition of Rs.1,82,63,955/- on account of unexplained money u/s 69A of the Act. The AO has reached a conclusion that the appellant had taken the above amount from three parties namely
-
- Sh. Mridul Khandelwal, Prop. M/s Chantaburi Ruby Jewels Expo, an amount of Rs.19,00,000/- on different dates whereas but her ITR shows returned income of only Rs. 12,02,000/-.
- Girraj Khandelwal (HUF), Prop. M/s Jai Paplaj Mata Exports has given loan amounting to Rs.71,00,000/- whereas shown a returned income of only Rs.15,89,890/-.
- Ms. Sangita Khandewal, Prop. M/s Shree Gordhan Gems has advanced amounts of Rs.86,51,119/- whereas shown returned income of only Rs. 13,01,685/- during the year.
Based on the above facts, the AO reached a conclusion that as the creditworthiness of these parties was not established by the appellant, hence he selectively chose the above amounts received from these three parties as unexplained money u/s 69A of the Act.
4.1.2 The appellant has claimed that the above transactions have been made with three family firms namely a) Chantaburi Ruby Jewels Expo, a proprietary firm of appellant’s brother b) Shree Gordhan Gems; a proprietary firm of appellant’s mother c) Paplaj Mata Export, a proprietary firm of HUF of appellant’s father. The appellant has submitted before the AO copy of acknowledgement of ITR, Copy of Computation of Total Income, Copy of Bank Statement and copy of confirmation of accounts of all three parties. All three are family member having sufficient source of income and filing their return of income regularly. The appellant has also explained each and every credit entry of their bank. The assessing officer has accepted identity and genuineness of Transactions on Page No 9 line No 11 of assessment order but has not accepted creditworthiness of the parties without bringing any material on records. There is not a single entry in the bank statement of all three parties which were given after depositing cash. All credit entries are well explained with their source. The appellant claims that as all the transactions are made through banking system and all three parties are filing their return of income regularly more than Rs 10.00 lacs, there is no basis for the addition.
4.1.3 I have gone through the case record and the submission made by the appellant. From the ledger account of M/s Chantaburi Ruby Jewels Expo shown below:-
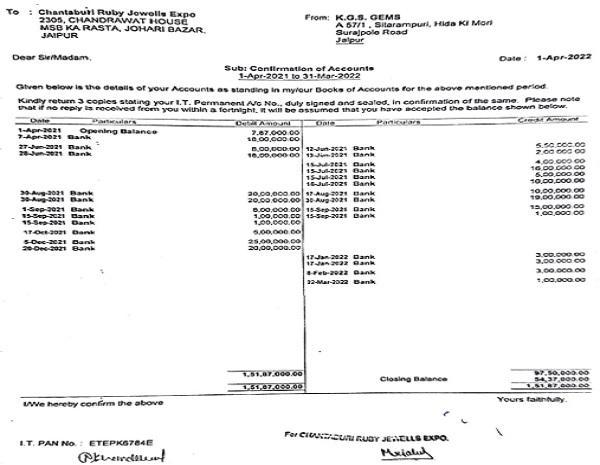
4.1.4 It is clearly seen that the said person is a debtor in the books of the appellant with an opening debit balance of Rs.7,87,000/- and a closing debit balance of Rs.54,37,000/-. It is correct that during the year the appellant has received the amount of Rs. 19,00,000/- on two dates but nevertheless the facts remains that these are receipt as settlement of money advanced by the appellant and hence the person in question is without a doubt a debtor. It is also to be seen that these amounts were transferred to the appellant as a settlement of the money advanced by the appellant and hence the said amount of Rs. 19,00,000/- is a settlement of the same and hence by no means can be treated as unexplained money u/s 69A of the Act. Besides from the persual of the bank statement of the said person, it is clear that there is no suspicious deposit of cash in the account of M/s Chantaburi Ruby Jewels Expo, before such amounts were transferred to the appellant. All the transfer to the appellant are also made through banking channels duly showing in the bank statement. It is also seen that Sh. Mridul Khandelwal Prop. has in his return of income shown a total income of Rs. 12,02,000/- and hence there is no material to doubt the creditworthiness of the said party as done by the AO. It is also interesting to note that during the FY there are almost two dozen debit and credit transactions with the party. It is even more intriguing to note that on what basis the AO chose three out of such entries for addition u/s 69A of the Act. Apparently, the AO had pre-decided that he has to chose entries just before the payment of money for purchase of stock as suspicious and add it u/s 69A to tally with the claimed purchase amount of Rs.1,82,63,955/- recorded in the books. If the creditworthiness of the party was treated as unproven then the entire amount received from the same should have been treated as unexplained and added u/s 69A of the Act. But the AO chose not to do so as the result would have been negative as the appellant has advanced more to the party than has received during the year. Even the conclusion of total income declared being insufficient, is without any basis as there is no doubtful credit entry in the book of the third party pointed out by the AO before advancement of such money and the total income returned can by no means be considered meagre. Also, the appellant has rightly pointed out that there is no suspicious cash deposit in the account of M/s Chantaburi Ruby Jewels Expo before the transfer in question was made. In view of the above, the addition made by the AO is clearly unsustainable and has to be deleted.
4.1.5 From the ledger account of M/s Jai Paplaj Mata Exports shown below-
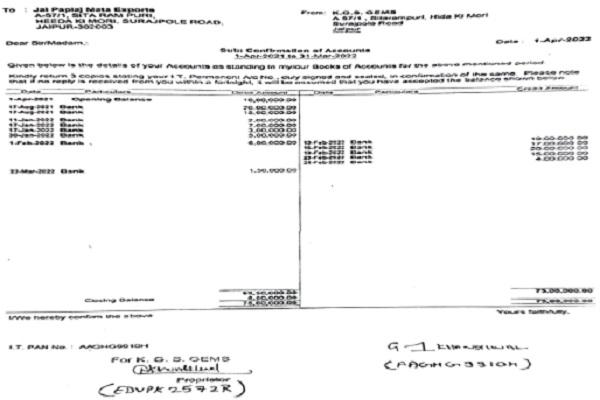
4.1.6 It is clearly seen that the said person is a debtor in the books of the appellant with an opening debit balance of Rs. 10,00,000/-. It is correct that during the year the appellant has received the amount of Rs.71,00,000/- but nevertheless the facts remains that these are receipt as settlement of money advanced by the appellant and hence the person in question is without a doubt a debtor. The facts of this case are identical to the earlier party discussed in detail in para 4.1.3.
4.1.7 It is also seen that Girraj Khandelwal (HUF) Prop. has in the return of income shown a total income of Rs.15,89,890/- and hence there is no material to doubt the creditworthiness of the said party as done by the AO. It is also interesting to note that during the FY there are almost a dozen debit and credit transactions with the party and just as in the case of the other parties there is no basis given by the AO that why he chose these particular entries out of many entries for addition u/s 69A of the Act. If the creditworthiness of the party was treated as unproven then the entire amount received from the same should have been treated as unexplained and added u/s 69A of the Act. But the AO chose not to do so as the result would have been negative as the appellant has advanced more to the party than has received during the year. Even the conclusion of total income declared being insufficient, is without any basis as there is no doubtful credit entry in the books of the third party pointed out by the AO before advancement of such money and the total income returned can by no means be considered meagre. Also, the appellant has rightly pointed out that there is no suspicious cash deposit in the account of M/s Jai Paplaj Mata Exports before the transfer in question was made. In view of the above, the addition made by the AO is clearly unsustainable and has to be deleted.
4.18 From the ledger account of M/s Shree Gordhan Gems shown below:-
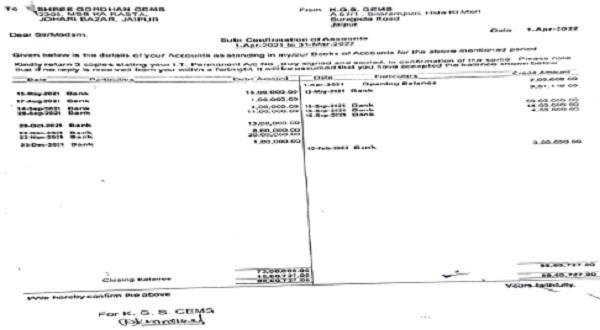
4.1.9 It is clearly seen that the appellant is having a running account with the said party and that there are receipt as well as payment of money by the appellant as well.
4.1.10 It is also seen that Sangeeta Khandelwal Prop. has in the return of income shown a total income of Rs. 13,01,685/- and hence there is no material to doubt the creditworthiness of the said party as done by the AO. The only basis for making this as well as the other two additions discussed above are based on the conclusion by the AO that their total income declared was insufficient. The said conclusion is at best a sweeping one and is totally devoid of any facts brought on record by the AO. The AO apparently is of the view that the total income shown in the return should be matching or more with the amount advanced. Such a view is totally wrong and unjustified. In the course of business money is often advanced and received from various parties to meet the requirements of the business, and has no apparent connection with the total income of a person. It has already been pointed out that there is no doubtful credit entry in the books any of the three parties before advancement of such money. Also, the appellant has rightly pointed out that there is no suspicious cash deposit in the accounts of any of the three parties before the transfer in question was made. The AO has not pointed out any fact other than the insufficiency of the returned income for treating the creditworthiness of the parties as doubtful, which in any case is not meagre by any means. In view of the above, the addition made by the AO is clearly unsustainable and has to be deleted.
4.1.11 Accordingly, this ground of appeal is allowed.”
7. It was the case of the assessee that he has taken unsecured loans of Rs. 19,00,000/-, Rs. 71,00,000/- and 86,51,119/-from M/s Mridul Khandelwal, Prop. M/s Chantaburi ruby Expo, from Griraj Khandelwal (HUF) Prop. M/s Jai Paplaj Mata Exports and Ms. Sangita Khandelwal Prp. M/s Shree Gordhan Gems respectively. It was the case of the assessee that the entire amount has been taken through banking channel and placed on record copy of letters dated 01.04.2022 regarding confirmation on account of Chantaburi ruby Jewells Export, M/s Jai Paplaj Mata Exports and Shree Gordhan Gems duly discussed in para 4.13, 4.1.5 and 4.1.8 of the impugned order.
8. The Assessing Officer had made the addition on the sole ground that unsecured creditors had meager return of income and was not in a position to advance the same however when it is proved on record that Ms Sangita Khandelwal was into the business of gems and jewellery she was having running account with the assessee and in the business setup. The Ld. CIT(A) has rightly decided that in the business setup money is advanced and received from various parties to meet the requirement of business, which has no direct connection with the return of income. Sometimes businessman has sufficient income to advance and to receive the same from other businessman even if his/her profit used to be Nil. Even there are no findings by the AO, if there is cash deposit and round tripping of the money through banking channel, nor there is any doubtful credit entry in the books of account of 3rd party. As such we have no ground to interfere into the findings returned by Ld. CIT(A).
9. On ground No. 3 and 4, we have perused the impugned order passed by Ld. CIT(A) on this ground qua addition of Rs. 3,39,00,058/- on account of unexplained expenditure u/s 69C of the Act, which is based upon the CBIC data, which shows that the assessee has imported Gems and Precious stone from two parties namely M/s M/s Radhey Gems & Jewellery Ltd. and M/s M/s Sambhav Gems co. to the tune of Rs. 5,21,64,013/- as against the recorded purchases of Rs. 1,82,63,955/- and the AO found the difference as unexplained. However Ld. CIT(A) by examining the issue at length deleted the addition by returning following findings as under:-
“4.2.3 The above submission of the appellant was examined with respect to the details filed and was also match with the bill of entries regarding the following details. For imports made from M/s Radhey Gems & Jewellery Ltd., the following details are seen:-
| Particulars | Amount (in Rs.) |
|---|---|
| Assessable Value as per CIF | 88,72,727 |
| (i) Basic Custom Duty Paid @ 0.50% of CIF value | 44,363.70 |
| (ii) Surcharge paid @ 10% of BCD | 4,436.30 |
| (iii) IGST paid @ 0.25% of CIF Value + BCD + Sur. (Rs 89,21,527) | 22,304.00 |
| Total Custom Duty Paid (i+ii+iii) | 71,104.00 |
4.2.4 The above details regarding payment of taxes is also verified from the bill of entry. It is also seen that the assessable value as per CIF and custom duty paid matches with the bill of entry.
4.2.5 Similar is the case for imports made from M/s Sambhav Gems Co., the following details are seen:-
| Particulars | Amount (in Rs.) |
|---|---|
| Assessable Value as per CIF | 96,94,961 |
| Basic Custom duty paid @ 0.50 of CIF | 48,474.70 |
| Surcharge paid @ 10% of BCD | 4,847.30 |
| IGST paid @ 0.25% of CIF value+ BCD+Sur. I.e. Rs. 97,48,283.30 | 24,371.00 |
| Total Custom Duty paid (i+ii+iii) | 77,693.00 |
4.2.6 The above details regarding payment of taxes are again verified from the bill of entry. It is also seen that the assessable value as per CIF and custom duty paid matches with the bill of entry.
4.2.7 The AO has annexed a copy of information received from CBIC in the SCN dated 16.03.2024, which is reproduced below:-
Transaction Month |
IEC Code |
Importer’s Name |
Importer’s Address |
Invoice Value (Rs.) |
Duty Paid (Rs.) |
Total |
Cumulative No. of Bills of Entry |
|---|---|---|---|---|---|---|---|
August |
1316912655 |
K.G.S. GEMS |
A57/1 SITARAM PURI HIDA KI MORI A57/1 SITARAM PURI HIDA KI MORI |
42740865 |
71104 |
42811969 |
1.00 |
September |
1316912655 |
K.G.S. GEMS |
A57/1 SITARAM PURI HIDA KI MORI SURAJ POLE CONTACT NO: 919057910180 JAIPUR |
9274351 |
77693 |
9352044 |
2.00 |
Total |
52015216 |
148797 |
52164013 |
4.2.8 From the above, it is clearly visible that the duty paid for the above invoices was Rs.71,104/- for import made in August and Rs.77,693/- for the import made in September. The invoice value could not have been Rs.5,20,15,216/- as stated there and clearly misreported because there was no way that duty of only Rs.1,48,797-could have been charged on the above invoice value. This clearly establishes that it is a case of misreporting of invoice value in the CBIC data.
4.2.9 The above fact is clearly established from a copy of certificate dated 17.04.2024 issued by Assistant Commissioner of Customs, Air Cargo Complex Sanganer Jaipur regarding the details pertaining to Bill of Entry submitted by the appellant. As per the certificate furnished, the details of BE No 4918153 Dated 03.08.2021 and 5482994 dated 17.09.2021, the total invoice value for imports made by appellant were USD 1,13,371 i.e. INR 85,48,173/- and assessable value was at Rs.88,72,727/- from M/s Radhey Gems and the invoice value was USD 1,24,655.25 i.e. INR 92,74,351/- and assessable value was Rs.96,94,961/- for the imports made from M/s Sambhav Gems Co. The above facts clearly reveal that the contention of the appellant and the figures of purchase as recorded in the books clearly tally with the invoice value of imports and the taxes paid thereon for which the information was given by the CBIC to the AO was correct in respect of calculation of stamp duty but was apparently misreported for the assessable value. Thus, the addition made by the AO is therefore deleted and this ground of appeal is accordingly allowed.”
10. Perusal of the aforesaid findings goes to prove that ld. CIT(A) has examined the matter in detail particularly copy of certificate dated 17.04.2024 issued by Assistant Commissioner of Customs, Air Cargo Complex Sanganer, Jaipur, which shows the total invoice value for imports made by the assessee to the tune of USD 1,13,371 i.e. Rs. 85,48,173/- and the assessable value at Rs. 88,72,727/- from M/s Radhey Gems and the invoice value was USD 1,24,655.25 i.e. Rs. 92,74,351/-. It also shows that the assessable value of Rs. 96,94,961/- from the import made from M/s Sambhav Gems Co., so the figures of purchase as recorded in the books clearly tallies with the invoice value of imports and the taxes paid thereon. We have examined the certificate dated 17.04.2024, which proves the contentions of the assessee to prove the figure of purchase recorded in the books, which are in consonance with the invoice value of imports and tax paid thereon.
11. In view of what has been discussed above, findings no illegality or perversity in the impugned order passed by the Ld. CIT(A), no ground has come on record to interfere into the impugned order..
12. Resultantly, the appeal filed by the Revenue is dismissed.
Order pronounced in the open court on 13-10-2026.






