
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

ITAT Criticises AO’s Inaction as Remand Reports & Upholds Section 54 Denial
Guide to HRA Exemption Claims under Scrutiny by Income Tax Authorities

ITR-4 for AY 2026-27: Quiet Tightening of Presumptive Taxation

Income Tax Appeal Dismissed due to 754-Day Delay & Uncured Incorrect Appeal Fee Payment
Complete Guide to Income Tax Appeal Mechanism and Procedure
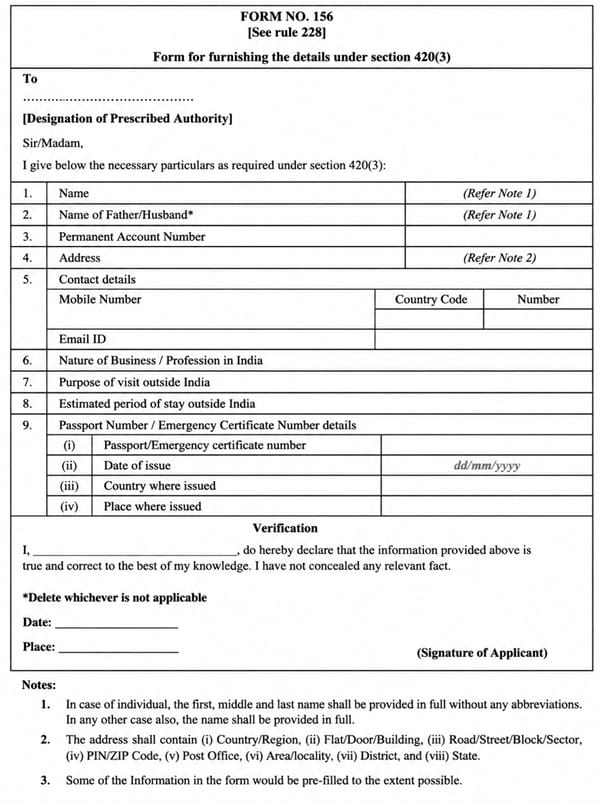
New Income Tax Form 156 Mandatory for Foreign Travel
No Section 69A Addition on Cash Deposits Recorded in Audited Books Where Source Is Explained

ITAT Deletes ₹76.45 Crore TP Addition as CCDs Cannot Be Recharacterized as Equity
ITAT Grants Fresh Hearing but Imposes Cost as Different Email Does Not Excuse Earlier Non-Compliance
ITAT Partly Allows TP Appeal, Revises Comparable Selection for ALP Determination
Goodwill Depreciation Denied as Business Transfer Agreement Was Unsigned & Unregistered
ITAT Upholds Demonetisation Cash Deposit as Because No Cash Book or Sales Evidence Produced
Section 234B Interest Not Leviable When Seized Cash Exceeds Tax Liability: ITAT Jabalpur
Understanding Tax Responsibilities After The Death of A Taxpayer
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

