Devi Singh Vs ITO (ITAT Delhi)
Illiteracy & Wrong Service of Notices Saved ₹2.61 Cr Addition; Ex-parte 144/147 Assessment Set Aside – ITAT Delhi
The Delhi Bench of the ITAT, in Devi Singh vs. ITO, Ward-5(1)(2), Noida (ITA No.3360/Del/2025, AY 2013-14, order dated 19-12-2025), condoned a delay of 111 days and set aside an ex-parte reassessment involving a massive addition of ₹2.61 crore on account of alleged unexplained bank credits.
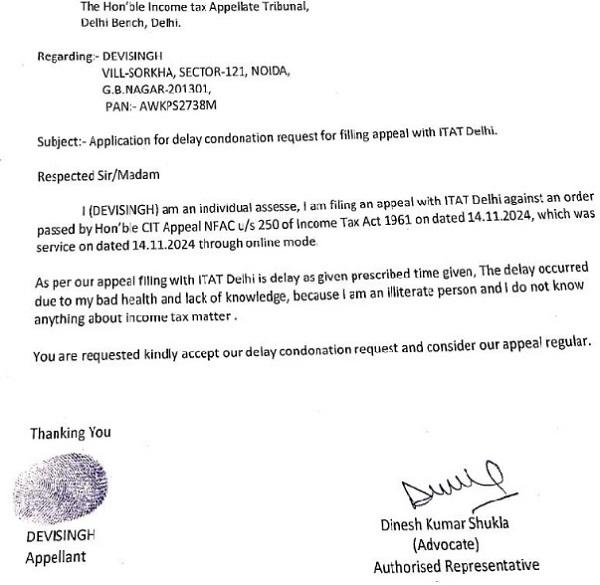
The Tribunal took note of the peculiar facts that the Assessee was totally illiterate, incapable of even signing documents, and had affixed a thumb impression on the delay-condonation application. It was further found that notices u/s 148 and subsequent statutory notices were served at a wrong address, depriving the Assessee of any effective opportunity of being heard. Both the assessment u/s 144 r.w.s. 147 and the appellate proceedings before CIT(A)/NFAC were completed ex-parte.
On merits, ITAT observed that the entire bank credits of ₹2,06.36 lakh (treated as ₹2.61 crore including other adjustments) were added mechanically u/s 69, despite the Assessee having plausible explanations such as land compensation from Noida Authority (exempt), sale of house property, bank loans, interest income and cash receipts, all summarised in a reconciliation statement placed on record.
Holding that principles of natural justice were grossly violated, the Tribunal set aside the assessment and appellate orders and restored the matter to the file of the AO for fresh adjudication on merits, with a direction to grant proper opportunity and examine the evidences in accordance with law. The appeal was allowed for statistical purposes.
FULL TEXT OF THE ORDER OF ITAT DELHI
This appeal filed by the assessee is preferred against the order of the Ld.Commissioner of Income Tax (Appeals)/NFAC, Delhi [herein after referred as “CIT(A)”] dated 14.11.2024 for the A.Y. 2013-14. The assessee has raised following grounds of appeal :-
“1. The impugned assessment is bad in law and on facts.
2. The Ld. Income Tax officer has erred in law and on facts in making the addition of Rs.2,61,36,104/- as transaction in bank account of assessee as income without concluding of the clarification, ignoring the fact.
3. The Ld. Tax Officer has erred in law and on facts in making addition of Rs.2,61,36,104/- on account of assessee return income of the assessee ignoring the facts and submissions of the appellant.
4. The Ld. Income Officer ought to have given proper opportunity to the appellant to make a representation in this regard and consider the same on merits before arriving at an adverse conclusion.
5. The impugned assessment is bad and unfair on the principle of natural justice.
6. The appellant cannot complied reply of any notice issued by the Hon’ble CIT Appeal” due to health issue and not awareness about faceless process of compliances.
7. The appellant is praying for one more opportunity for complying facts.”
2. The application for condonation of delay has been filed by the Ld. Counsel for the assessee for the delay of 111 days. The Assessee in his application for the delay stated as under :-