
Mukund Das Heda Vs ITO (ITAT Hyderabad)
Assessee appealed against a reassessment order passed u/s 147 r/w 144 & 144B, but before CIT(A) he did not respond to notices, leading to an ex-parte dismissal. However, ITAT found that CIT(A) failed to adjudicate several legal grounds, including challenges to the validity of reassessment, which were clearly raised before him.
U/s 250(6), the CIT(A) must pass a speaking, reasoned order addressing each ground. Since CIT(A) ignored all grounds & dismissed the appeal mechanically, ITAT held that this amounted to denial of proper appellate remedy.
Tribunal therefore set aside CIT(A)’s order & restored the matter to him for fresh adjudication on merits, directing that Assessee be given proper opportunity & also asked not to delay proceedings.
Held: Ex-parte dismissal without adjudicating grounds violates Section 250(6); appeal restored for de novo consideration.
FULL TEXT OF THE ORDER OF ITAT HYDERABAD
This appeal is filed by Shri Mukund Das Heda (“the assessee”), feeling aggrieved by the order passed by the Learned Commissioner of Income Tax (Appeals), National Faceless Appeal Centre (NFAC), Delhi (“Ld. CIT(A)”) dated 04.03.2025 for the A.Y. 2016-17.
2. The assessee has raised the following grounds of appeal: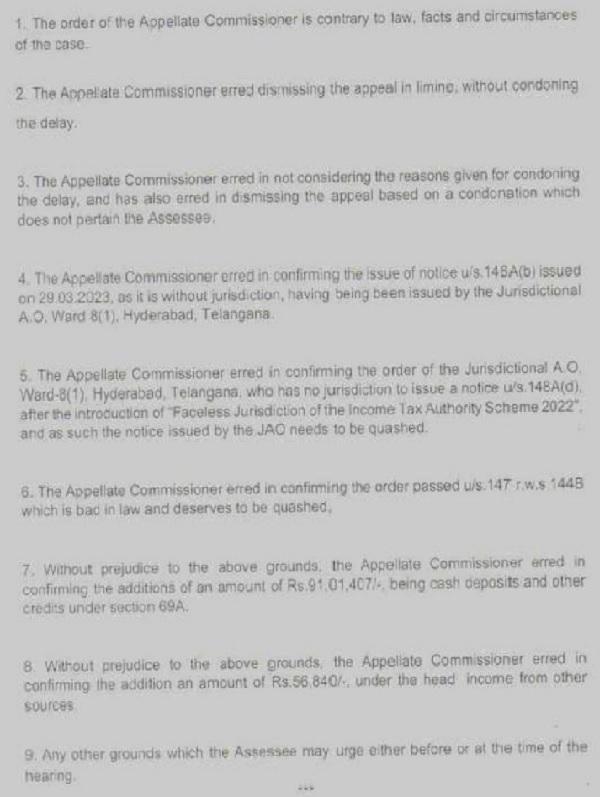
3. The brief facts of the case are that the assessee had filed an appeal before the Ld. CIT(A) against the order passed by the Learned Assessing Officer (“Ld. AO”) under section 147 read with sections 144 and 144B of the Income Tax Act, 1961 (“the Act”) dated 16.03.2024 for the Assessment Year 2016–17. However, the assessee could not respond to the notices issued by the Ld. CIT(A) during the course of appellate proceedings. Consequently, the Ld. CIT(A) proceeded ex-parte and dismissed the appeal filed by the assessee.







