
Ziyauddin Traders Vs ITO (ITAT Agra)
Computer-Generated Bills, Absence of GST Number or Thumb Impressions Cannot Turn Genuine Livestock Purchases into Bogus Purchases: ITAT Deletes ₹9.45 Crore Addition
Summary: In a significant decision concerning ad hoc disallowance of purchases, the Agra Bench of the Income Tax Appellate Tribunal held that purchases cannot be treated as bogus merely because the invoices are computer-generated, do not mention a GST number, or contain the thumb impressions of rural sellers. Where the assessee had maintained quantitative records, produced purchase details and bank statements, and the corresponding sales had been accepted, an arbitrary disallowance of 30% of purchases was held to be unsustainable.
The assessee, M/s Ziyauddin Traders, was engaged in purchasing live buffaloes from local village markets, individual agriculturists and dairies and supplying them to slaughterhouses and dealers. For Assessment Year 2022-23, it disclosed total purchases of approximately ₹106.05 crore, sales of ₹108.46 crore and gross profit of ₹2.41 crore, representing a gross-profit rate of about 2.22%.
The case was selected for scrutiny because substantial payments had been made to persons who were not registered under GST. In the original assessment order, the Assessing Officer disallowed 20% of the entire purchases, resulting in an addition of approximately ₹21.21 crore under Section 69C. The Allahabad High Court subsequently set aside that order and directed the Assessing Officer to reconsider the matter after granting the assessee an opportunity to respond.
In the fresh assessment, the Assessing Officer noticed that TDS under Section 194Q was reflected in the assessee’s Form 26AS in respect of transactions amounting to approximately ₹74.56 crore. However, these entries actually represented TDS deducted by the assessee’s customers on purchases made by them from the assessee—that is, they related to the assessee’s sales and not its purchases.
Nevertheless, the Assessing Officer treated the balance amount of approximately ₹31.49 crore as purchases insufficiently verified and disallowed 30% thereof. Consequently, an addition of ₹9,44,60,438 was made as business income. The principal objections of the Assessing Officer were that the invoices were computer-generated, did not contain sales tax or GST registration numbers and, in the case of cash purchases, contained only the thumb impressions of the sellers. The CIT(A) upheld the addition.
Before the Tribunal, the assessee explained that out of its total purchases of approximately ₹106.05 crore, purchases of ₹53.42 crore were subject to TDS under Section 194Q and were paid through banking channels. Another ₹50.95 crore was also paid through banking channels, though TDS was not deducted because purchases from each individual supplier did not cross the statutory threshold of ₹50 lakh. Only ₹1.67 crore, constituting approximately 1.57% of the total purchases, was paid in cash to small agriculturists and other occasional suppliers.
The assessee also produced supplier-wise purchase details, confirmations, bank statements, income-tax returns of suppliers wherever available, purchase invoices and cash purchase bills. It further maintained a quantitative stock register showing the purchase and sale of 49,546 live animals. Significantly, the Assessing Officer had accepted the entire sales and had not rejected the assessee’s books of account.
The Tribunal observed that the Assessing Officer had made a general statement that the assessee failed to produce relevant documentary evidence but had not identified the particular documents allegedly not furnished. The material placed before the Tribunal, including screenshots from the income-tax portal, demonstrated that extensive supporting documents had, in fact, been uploaded during the assessment proceedings.
The Tribunal also noticed that the Assessing Officer had not conducted any meaningful enquiry into the documents furnished by the assessee. No specific purchase transaction was identified as false, inflated or fictitious. Neither any defect in the stock register nor any quantitative mismatch between purchases and sales was brought on record.
An important aspect considered by the Tribunal was the nature of the assessee’s business. Live bovine animals falling under HSN 0102 are exempt from GST under Notification No. 02/2017-Central Tax (Rate), dated 28 June 2017. Therefore, the absence of GST registration numbers on the invoices could not be regarded as an adverse circumstance. When the underlying goods were themselves exempt and the suppliers were agriculturists and persons operating in the unorganised rural sector, GST registration could not be expected as a matter of course.
The Tribunal categorically held that the mere fact that purchase invoices were computer-generated did not make the purchases bogus. Similarly, the presence of thumb impressions on cash purchase vouchers could not, by itself, establish that the purchases were non-genuine. This was particularly so when cash purchases constituted only 1.57% of the total purchases and were supported by 45 purchase bills.
The assessee also explained that transportation of livestock was arranged by the suppliers or agriculturists, while the diesel expenditure for the vehicles was borne by the assessee. The transportation-related fuel expenditure of approximately ₹1.77 crore was incurred through an identified fuel supplier, paid entirely through banking channels and subjected to TDS under Section 194Q.
Considering the purchase records, bank payments, supplier confirmations, quantitative stock details, transportation expenditure and accepted sales, the Tribunal held that the ad hoc disallowance of 30% had no rational or evidentiary foundation. Accordingly, the entire addition of ₹9,44,60,438 was deleted, and the assessee’s appeal was allowed.
Author’s Comments
The decision reinforces the settled principle that suspicion cannot substitute evidence. If the Revenue accepts the sales, the quantitative records and the movement of goods, it cannot arbitrarily disallow a substantial portion of the corresponding purchases without demonstrating which purchases are fictitious or inflated.
The Assessing Officer must also appreciate the commercial realities of the particular trade. Transactions with agriculturists and rural livestock sellers cannot be judged solely by the documentation standards ordinarily expected from organised corporate suppliers. More importantly, absence of a GST number cannot be treated as evidence of bogus purchases where the goods themselves are exempt from GST.
The ruling also exposes the danger of mechanically relying on Form 26AS. TDS under Section 194Q appearing in the assessee’s Form 26AS represented purchases made by its customers and consequently proved the assessee’s sales. It could not be used to divide the assessee’s own purchases into “verified” and “unverified” categories. Without rejection of books, identification of specific defects or independent evidence of inflation, an arbitrary estimate of 30% of purchases cannot withstand judicial scrutiny.
Cases Discussed
- ACIT Vs. Ajit Ramakant Phatarpekar (2015) 119 DTR 27 (Panaji) (Trib.) — relied upon for the proposition that where quantitative details and sales are accepted, disallowance of cash purchases merely because the identity of sellers was not proved is unjustified.
- ACIT Vs. Inlay Marketing Pvt. Ltd. (2015) 113 DTR 121 (Del.) (Trib.) — relied upon to contend that where no defect is found in the books and sales are accepted, addition under section 69C towards purchases cannot be sustained merely by rejecting the purchases.
- PCIT Vs. Vaman International Pvt. Ltd., ITA No. 1940 of 2017, order dated 29.01.2020 (Bombay High Court) — relied upon for the proposition that an addition under section 69C for alleged bogus purchases requires supporting material and appropriate enquiry.
FULL TEXT OF THE JUDGMENT/ORDER OF ITAT AGRA
1. This appeal is directed against the impugned order dated 07.10.2025 passed in appeal No NFAC/2021-22/10505417 by the ld. Commissioner of Income Tax/ National Faceless Appeal Centre (NFAC), Delhi (hereinafter referred to as the “CIT(A) u/s. 250 of the Income Tax Act, 1961 (hereinafter referred to as the “Act”) for the A.Y. 2022-23, wherein ld. CIT(A) has dismissed the appeal of the assessee.
2. In this case we note that there is a delay of 121 days in filing this present appeal before the Tribunal. In this regard, the assessee has filed an application dated 20.04.2026 seeking condonation of delay. The relevant extracts of the same are reproduced as under:
“Sub: Application for condonation of delay in filing the appeal
With reference to above it is to submit that the Ld. CIT(A), NFAC vide order dt. 07.10.2025 has upheld the order passed by AO assessing the total income at Rs.9,44,60,438/-. The appeal was to be filed on or before 31.12.2025. However, for the reasons stated hereunder, the appeal could not be filed in time:-
1. I am Partner of M/s Ziyauddin Traders which is engaged in the business of supply of live animals stock (buffalo) to the different slaughter houses & dealers after procuring the same from local markets/ persons
2. AO passed the assessment order of the firm for AY 2022-23 on 27.03.2024 making addition of Rs.21.21 crore by disallowing 20% of the purchases of Rs.106.05 crore. This order was challenged by way of writ in the Allahabad High Court. The Hon’ble High Court vide order dt. 08.05.2024 set aside the order to the AO to pass appropriate order by considering the assessment order dt. 27.03.2024 as the show cause notice.
3. In pursuance to the direction of Hon’ble High Court, we filed our reply on 25.05.2024. However, the AO without considering the said reply, issued show cause notice dt. 09.05.2025 proposing addition of Rs.31,48,60,130/-, being the amount of purchase on which tax was not deducted u/s 194Q of the Act. Against the show cause notice, reply was filed raising various objections including not following the direction of Hon’ble High Court and the mistake in the show cause notice but AO by ignoring the same, vide order dt. 31.05.2025 made addition of Rs.9,44,60,438/- by disallowing 30% of the purchases of Rs.31,48,68,129/-. Against this order, appeal was filed before Ld. CIT(A) on 28.06.2025.
4. The National Faceless Appeal Centre (NFAC) issued notices of hearing at e-mail id [email protected] on 03.07.2025, 29.07.2025 & 08.08.2025 though on the income tax e-filing portal and in Form No.35, e-mail id mentioned is [email protected]. The NFAC passed the order on 07.10.2025. This order did not come to our notice nor to the notice of CA Raj Kumar and therefore no appeal could be filed against this order.
5. The AO also initiated assessment proceedings for AY 2024-25 by issuing notice dt. 24.06.2025 at the e-mail id [email protected] and the subsequent notices dt. 22.8.2025, 02.12.2025, 17.02.2026, 25.02.2026, 03.03.2026 & 10.03.2026 at e-mail id [email protected]. The assessment order was passed on 24.03.2026. When I approached to our tax auditor CA Rahul Mittal with the assessment order on 26.03.2026, he browsed the e- filing portal when it came to the notice that the appellate order has been passed on 07.10.2025. This fact was then intimated to CA Raj Kumar who was also surprised to know this fact as he was under the impression that the appeal for AY 2022- 23 is still pending before the NFAC.
6. For the above reason there is delay in filing the appeal from the date of passing of the appellate order. However, as advised, I am now filing the appeal before Hon’ble ITAT along with the request to condone the delay in filing the appeal. +the delay in filing the appeal before Hon’ble ITAT is due to a reasonable cause and therefore, the same be condoned and appeal be admitted for hearing for imparting substantial justice.”
2.1 The above facts have also been supported by an affidavit dated 16.04.2026 by Shri Tahir, partner of the assessee firm.
2.2 We have perused the aforesaid reasons and the affidavit filed by the assessee. In view of the facts stated therein, we are satisfied that the assessee was prevented by sufficient cause for the delay in filing the appeal. Accordingly, the delay of 121 days in filing the appeal before us is condoned and the appeal is admitted for hearing.
3. Brief facts of the case: The assessee is a partnership firm and during the year the AO noted that the assessee was engaged in the business of supply of live animal stock (Buffalo) to the different slaughter houses and dealers after being procured from the local village markets, individual agriculturist and dairies. The AO noted that during the year under consideration, the assessee had shown substantial payments to the entities which were not registered under GST and the case of the assessee was selected through CASS to verify the same.
3.1 The AO in this case passed an assessment order u/s 143(3) r.w.s 144B of the Act on 27.03.2024 in which the AO disallowed an amount of Rs. 21,20,93,812/- being 20% of the total purchases of Rs. 106,04,69,062/- as unexplained expenditure u/s 69C of the Act. Against this order, the assessee filed a Writ Tax number 709 of 2024 before the Hon’ble Allahabad High Court wherein the Hon’ble Court in para no. 12 of its order dated 08.05.2024 set aside the impugned assessment order and directed as under:
“The present petition is disposed of, at this stage. The impugned assessment order dated 27.03.2024 is set aside. The petitioner may treat the adverse findings in the impugned assessment order as points on which he may show cause. The petitioner may furnish his further/final reply within a period of three weeks and no more, from today. Thereupon, appropriate date may be fixed for personal hearing with at least 15 days advance notice. The petitioner undertakes to appear before the assessing authority on the date fixed. Thereafter, appropriate order may be passed.”
3.2 Pursuant to the above directions of the Hon’ble Allahabad High Court, the AO passed an assessment order on 31.05.2025 u/s 144 r.w.s 143(3) read with section 144B of the Act. In this assessment order the AO considered 30% of the purchases of Rs. 31,48,68,129/- amounting to Rs. 9,44,60,438/- as business income and added the same to the total income of the assessee.
3.3 During the course of assessment proceedings, the AO vide notice u/s 142(1) of the Act dated 01.05.2025 at serial no. 4 (placed at page no. 42-43 of the paper book) had inter alia asked for the following details:
“4. With respect to Purchases, for an amount of Rs. 106,04,69,063/-, made by you, kindly provide complete details as under:
a) Name, address, PAN and GST registration number of the parties from which the purchases have been made.
b) Date of purchase.
c) Copy of agreement if any
d) Product details-
i. Item no.
ii. Quantity
iii. Amount
e) Details of transportation:
i. Date of transportation.
ii. Name and address of the transporter.
iii. Vehicle number.
iv. Weight.
v. Amount paid.
vi. TDS deducted.
f) Details of payment:
i. Date of payment
ii. Amount
iii. Mode of payment with supporting documentary evidence.
iv. Amount payable at the end of the financial year”
3.4 In reply the assessee furnished the following details:
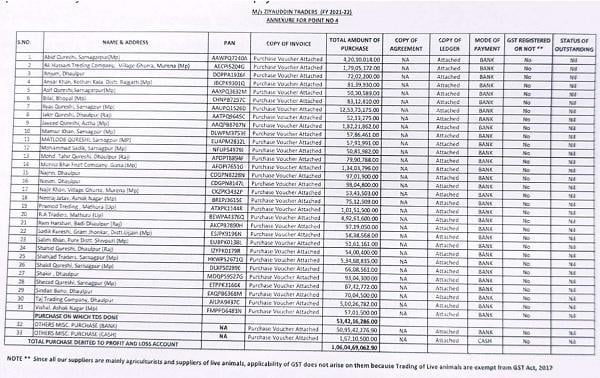
3.5 The AO upon examining the above details of purchases noted that there were more than 10 suppliers from whom almost one crore of purchases was made and 4 suppliers from whom almost Rs. 5 crores (from each) of purchases have been made and from 1 supplier from whom purchases more than Rs. 12 crore was made. In the earlier assessment proceedings, the AO had issued notices to the above purchasers and had noted that the replies were received only from 2 suppliers. In the present assessment proceedings, the AO taking note of the above fact and upon the perusal of the reply of the assessee which stated that the confirmation of the suppliers could not be submitted in compliance to notice u/s 133(6) of the Act on IT portal as very short time was provided and some of the suppliers were not filing their income tax return as their income was below the taxable limit for AY. 2022-23 and they were all agriculturist commented that the said reply was self-contradictory. The AO also took note of the fact that in respect of 133(6) notices issued to the purchasers reply from only 2 were received and hence the genuineness and the credit worthiness of the suppliers could not be proved. The AO also noted that on perusal of the invoices submitted by the assessee in respect of purchases that the same were only computer-generated invoices, not having any Sales Tax No and GST no on those invoices and the transaction of each invoice in lakhs with each supplier without GST no. was not acceptable
3.6 Thereafter the AO reproduced the submission of the assessee which stated that in respect of sale of Rs. 74,56,08,933/- made by the assessee, wherein the respective purchasers had deducted TDS u/s 194Q of the Act, shows that the sale to that extent was genuine. However, it appears that the AO considered the said amount of Rs. 74,56,08,933/- appearing in the 26AS to be purchases made by the assessee. Therefore, the AO for the balance amount of the purchases i.e. (Rs. 106,04,69,063 – 74,56,08,933), which came to Rs. 31,48,60,130/- vide show cause notice dated 09.05.2025 in para no. 3.4.1 (placed at page no. 45 to 58 of the paper book, particularly at page no. 56 to 57) asked the assessee to submit the following details:
| Name of the party | Amount | Date of Payment | Mode of Payment (By cheque/cash) |
“1. If payment is done through cheque, entries maintain in the above list, please specify name of the bank, page no. of the bank statement, specifying the highlighted entry only will be considered.
2. vouchers and bills for the transactions should be submitted in the same order as per the serial no. of the transactions.
3. As per assessee’s reply dated 28.04.2025 purchase vouchers for an amount on Rs. 1,67,10,500/- appeal submitted by the assessee that also comes under the preview of section 269T.
Hence the Assessee is show caused as to why the balance amount of purchases i.e. Rs. 31,48,60,130/- for which no TDS u/s 194Q has been deducted and section 269T is also applicable, should not be added to be total income of the assessee.”
(Addition- 31,48,60,130/-)
3.7 In reply (placed at page no. 59-67 of the paper book) the assessee submitted that the assessee dealt in trading of live animals procured in local village markets colloquially called “painth” and the live animals were not subject to levy of GST since GST is not leviable on the live animals (HSN0102) as exempted under serial no. 2 of notification no. 02/2017-CTR dated 28.06.2017 and therefore, the suppliers of the live animals are not required by law to be registered under CGST/SGST Act. The assessee further submitted that purchases amounting to Rs. 53,42,16,286/- have been made from traders/large suppliers on which TDS u/s 194Q of the Act as applicable was duly deducted and deposited. Further, it was submitted that entire payment to the suppliers were only through banking channels and filed a reconciliation statement with the copies of bank statements as an attachment before the AO. It was further submitted that in respect of purchases amounting to Rs. 50,95,42,276/- the same were made from different individual agriculturists/ suppliers to whom payments were made through banking channels and also filed a reconciliation statement with the copies of bank statements as an attachment before the AO. It was further submitted that in respect of these purchases the volume and value of purchases from these individual suppliers was not large and therefore, these transactions did not come under the preview of TDS u/s 194Q of the Act. Regarding the purchases amounting to Rs. 1,67,10,500/- in cash it was submitted that these sellers were individual agriculturist not being their regular suppliers who required immediate payments and, therefore, it was made in cash. It was also submitted that the cash purchases were mere 1.57% of the total purchases which was even below the standard limit set out in first proviso to section 44AB(a) of the Act. The assessee also submitted that entire sales were made through banking channel and all though the assessee was dealing in rural sector which is mostly unorganized managed a 99% banking transaction ratio for its sales and purchases. The assessee in its reply also furnished the confirmations from suppliers to whom notices u/s 133(6) were sent during the earlier assessment proceedings. Further, in respect of the above query vide show cause notice dated 09.05.2025 in para no. 3.4.1, as reproduced above the assessee submitted 250 purchases invoices as a representative sample in which the assessee had specified entry and the same was claimed to have been reconciled/ numbered in the bank statement. In this regard, the assessee also submitted that the assessee can also furnish the specific invoices as directed by the AO from the said list. The relevant extract of the reply submitted by the assessee vide letter dated nil placed at page no. 59 to 67 of the paper book is reproduced as under:
“1. Para 3.4 of the Show Cause Notice proposes a variance of Rs. 31,48,60,130/- being amount of purchases on which no TDS u/s 194Q of the Income tax Act 1961 (Act) has been deducted and that section 269T of the Act is also allegedly applicable.
In this regard it is most respectfully submitted as under:
a) The assessee deals in trading of live animals whereby these animals are sourced mainly through other traders and also directly through individual agriculturists. The deals are done in local village markets colloquially called “painth”/ “पैंठ”.
b) Whenever the volume of purchases with other traders becomes large during the year it comes under the purview of TDS u/s 194Q of the Act.
c) The purchases made through individual agriculturists are small in size and volume and is an adhoc purchase. As a normal practice, they require immediate payment and insist on cash payments. The purchase from these individual agriculturists do not cross the threshold of TDS U/s 194Q of the Act. These agriculturists are not regular suppliers.
d) The total purchases of the assessee during the year under consideration were Rs. 1,06,09,69,063/-
e) Out of these total purchases, purchases amounting to Rs. 53,42,16,286 have been made from traders/large suppliers. TDS u/s 194Q of the Act as applicable has been duly deducted and deposited. The entire payments made to these suppliers are only through banking channel and the same are being reconciled with the copies of bank statements of the assessee in a separate attachment.
The assessee has been able to secure confirmation from these suppliers. Copies of confirmations from suppliers along with copies of their Income Tax Returns and Bank statements (wherever received) are being furnished. The confirmation also mentions PAN of the supplier. The assessee has been able to secure confirmation from these suppliers. Copies of confirmations from suppliers along with copies of their Income Tax Returns and Bank statements (wherever received) are being furnished. The confirmation also mentions PAN of the supplier.
f) Further, purchases amounting to Rs. 50,95,42,276.90 were made during the year from different individual agriculturists/suppliers to whom payments were made directly into their bank accounts. As the volume and value of purchases from these individual suppliers was not large, these transactions did not come under the purview of TDS u/s 194Q of the Act. The entire payments made to these suppliers are only through banking channel and the same are being reconciled with the copies of bank statements of the assessee in a separate attachment.
g) Further, purchases amounting to Rs. 1,67,10,500 were made during the year from different small individual agriculturists to whom payments were made in cash. As the volume and value of purchases from these suppliers did not cross the threshold, these transactions did not come under the purview of TDS U/s 1940 of the Act.
h) It shall not be out of place to mention here that the cash purchases are a mere 1.57% which is even below the standard limit set out in first proviso to section 44AB (a) of the Act. The entire sales of the assessee are through banking channel.
i) The assessee, as a good business practice, follows and insists transactions via banking channel and uses cash only in unavoidable circumstances.
This is a very important point to note that the assessee, although dealing in rural sector which is mostly unorganized, has managed a 99% banking transactions ratio for its sales and purchases.
j) The assessee also wishes to draw your honour’s kind attention to the fact that there are no creditors during the year. The entire payment of the purchases has been duly made (mostly by bank and a small ratio by cash).
k) The sales are undisputed, quantity wise stock register is duly maintained, furnished and reconciled. Disputing the purchases without any kind of incrimination material against the assessee will not be in the interest of natural justice. Sales cannot be made without making purchases.
l) Another important point to note ever here is that the assessee is dealing in an sector whereby mostly the sellers. Individual agriculturists/farmers without an organized business setup. They bring their animals to the local village markets colloquially “पœठ” for selling and the deal is done then and there with immediate payment. Full payments have been made to the suppliers, there are no creditors.
m) It will not be out of place to mention here that live animals are not subject to levy of GST since the GST is not leviable on the Live Animals (HSN0102) as exempted under Sr.No.2 of Notification No.02/2017-CTR dated 28/06/2017 and therefore the suppliers of live animals are not required by law to be registered under GST and hence none of the suppliers are registered under CSGT/SGST Act. This is in full compliance to the legal provisions of the GST Act. Since the suppliers are from unorganized sector and exempt from GST, one would not expect a formal agreement or other formal documentation from these suppliers. The assessee as a prudent business practice has maintained purchase invoices and the same are being furnished.
n) As desired in para 3.4.1 of the show cause notice, the assessee is furnishing the following:
Confirmations from suppliers to whom notices u/s 133(6) were sent during the earlier assessment proceedings.
Details of transactions of purchase in the following format-
| Name of the party | Amount | Date of Payment | of Mode of Payment (By Cheque/Bank Transfer/Cash) |
If payment is done through bank, the entry has been specified as such and the same has been reconciled/numbered in the bank statement.
Voucher and bills for the transactions are being submitted and the serial number of the entry has been marked on the voucher. However the assessee calculated the total purchase vouchers which came to approximately more than 8000. Scanning each one of them appears to be extremely voluminous and time taking process. The assessee is furnishing about 250 purchase invoices as a representative sample to expediate the review process. The assessee can also furnish the specific invoices as difected by your honour from the list.”
3.8 The above reply of the assessee was considered by the AO but the AO was not satisfied in the above reply stating that in spite of being allowed repeated opportunities of being heard and to file the supporting details/documents required as per notices issued, the assessee has not filed the relevant documentary evidences in support of his claim. Accordingly, he observed that this office was left with no other alternative but to pass the assessment order on the basis of details/documents available on record. Thereafter, the AO stated that the assessee was issued show cause notice on 09.05.2025 which was replied by the assessee on 12.05.2025 and 13.05.2025 which was considered but found not satisfactory. The AO remarked that the assessee had failed to submit any other relevant documentary evidences in support of his claim. Further, the AO also noted that the assessee had sought video conference (VC) which was fixed for 26.05.2025, wherein the assessee did not appear on the VC scheduled on 26.05.2025. The AO held that in view of the above facts, reply of the assessee was not found to be satisfactory and he treated 30% of the balance purchases (Rs.31,48,68,129/-) which came to Rs. 9,44,60,438/- and considered the same as business income and added the same to the total income of the assessee. The relevant extracts of the order of the AO are reproduced as under:
“3.2 Summary of information evidence collected after SCN (if any): NA. 3.3 Point-wise rebuttal of reply of the assessee including analysis of any case law relied upon –The assessee was issued show-cause notice on 09.05.2025 fixing the case for hearing on 13.05.2025. The assessee has filed his reply on 12.05.2025 and 13.05.2025. It may be clearly Noted:-
With reference to the TDS deductions reflected in Form 26AS of the assessee under Section 194Q of the Income-tax Act, 1961, it is respectfully submitted that these entries pertain to transactions where Ziyauddin Traders acted as the seller of goods. The said TDS has been deducted by various buyers on purchases made from the assessee, in compliance with their obligations under Section 194Q. This clearly establishes that sales to the extent of approximately 74 crore were made by the assessee during the relevant financial year, and such sales have been duly recorded in the books of accounts and reported in the audited financial statements and income tax return. These transactions are also supported by proper banking channels. Accordingly, while these entries confirm the genuineness of the assessee’s sales, it may be noted that the TDS under Section 194Q in 26AS does not relate to the assessee’s own purchases. Rather, it evidences that buyers who crossed the specified threshold deducted TDS while making payments to the assessee. Furthermore, the existence of genuine sales in such substantial volume strongly supports the fact that corresponding purchases have actually taken place. The assessee has already submitted complete details and reconciliation of purchases, payments, and sales, including stock register and supplier confirmations wherever available. Therefore, there is no basis to question the genuineness of any part of the purchases, and no adverse inference is warranted under Section 69C or any other provision on this part of purchases made by the Assessee. However for the rest of almost 31crore plus of purchases made by the Assessee the Assessee is saying that the purchases have been made from small agriculturist , most of them are non filers however the transactions done with them are in crores in the F.Y 2021-22 relevant to A.Y 2022-23. On perusal of the invoices submitted by the Assessee it is seen that the invoices are only computer generatedinvoices, not having any Sales Tax No and GST no on those invoices and the transaction of each invoice is in lakhs with each supplier, hence not acceptable. As for the invoices submitted by the Assessee for cash purchases for an amount of Rs 1.67 crores there is only thumb impression given on these invoices and the amount of transaction is in lakhs for each of these transactions, hence can not be considered genuine.
3.4 Conclusion drawn: In view of the facts narrated above, it can be seen that the assessee in spite of being allowed repeated opportunities of being heard and to file the supporting details/documents required as per notices issued, the assessee has not filed the relevant documentary evidences in support of his claim. Hence, this office is left with no other alternative but to pass the assessment order on the basis of details/documents available on record. As discussed above, the assessee was issued show cause notice on 09.05.2025. The assessee has filed his reply on 12.05.2025 and 13.05.2025. The reply of the assessee is considered but found not satisfactory. He has failed to submit any other relevant documentary evidences in support of his claim. Further, assessee had sought VC. The VC was fix for 26.05.2025. The Assessee did not appear on the VC scheduled on 26.05.2025. In view of the above facts, reply of the assessee is not found to be satisfactory. Hence, 30% of the balance purchases (Rs.31,48,68,129/-) which is Rs. 9,44,60,438/- is considered as business income and is added to the total income of the Assessee.”
(emphasis supplied by us)
4. Aggrieved with the said order the assessee filed an appeal before the Ld. CIT (A) who dismissed the appeal of the assessee. In this regard, the relevant extracts of the order of the Ld. CIT A are reproduced as under:
“8. The ground No.3 is related to making addition of variation of Rs.9,44,60,438/- in respect of business income.
8.1 The appellant has contended that the learned AO has erred in law and on facts by making an arbitrary variation of Rs.9,44,60,438/- being 30% of the balance purchases of Rs.31.49 crores, without proper justification. The disallowance is based merely on the allegation that invoices were computer-generated without sales tax or GST numbers and that certain cash purchases bore thumb impressions, ignoring that livestock transactions are not subject to GST and all invoices in this trade are computer-generated. The appellant had duly maintained audited books of accounts, stock registers, and provided all details sought, none of which were rejected by the AO. While the gross profit of 2.22% was accepted on purchases of Rs. 74.56 crores, the AO disallowed 30% of the balance purchases without clarifying whether such disallowance implied that livestock was never purchased or that purchases were inflated.
8.2 On perusal, it is evident that the variation of Rs.9,44,60,438/- made by the learned AO in respect of business income is fully justified and does not merit interference. The AO has clearly brought out that the balance purchases of Rs.31.49 crores were supported only by computer-generated invoices without sales tax or GST numbers, and in respect of cash purchases of Rs.1.67 crores, the invoices merely bore thumb impressions, thereby rendering their genuineness highly doubtful. The assessee failed to substantiate the authenticity of such purchases with reliable documentary evidence, and the AO was left with no option but to make a reasonable disallowance of 30% of the unverifiable purchases. The disallowance is thus based on cogent reasoning and material facts and not on mere conjectures as alleged. Accordingly, Ground No. 3 challenging the addition of Rs.9,44,60,438/- is hereby dismissed.”
5. Aggrieved with the said order the assessee is an appeal before us on the following ground of appeal:
“The Ld. CIT(A), NFAC has erred on facts and in law in confirming the addition of Rs.9,44,60,438/- made by the AO by disallowing 30% of the purchases of Rs.31,48,68,129/- by (i) not following the direction of Hon’ble Allahabad High Court (ii) not appreciating that entire purchase of Rs.106.05 crore made by the assessee is verifiable (iii) assessee has maintained the complete stock record and (iv) the g.p. rate declared during the year is better than the earlier years g.p. rate.”
6. At the time of hearing, the Ld. AR relied upon the submissions filed by the assessee before the Ld. CIT (A) placed at 1 to 5 of the paper book. Further, the Ld. AR also filed a written submission before us which is reproduced as under:
“The Ld. CIT(A), NFAC has erred on facts and in law in confirming the addition of Rs.9,44,60,438/- made by the AO by disallowing 30% of the purchases of Rs.31,48,68,129/- by (i) not following the direction of Hon’ble Allahabad High Court (ii) not appreciating that entire purchase of Rs.106.05 crore made by the assessee is verifiable (iii) assessee has maintained the complete stock record and (iv) the g.p. rate declared during the year is better than the earlier years’ g.p. rate.
Facts:-
1. The assessee is engaged in the business of supply of livestock. It filed the return of income on 23.09.2022 declaring total income of Rs.3,08,090/- (PB 6-10).
2. The AO passed the assessment order u/s 143(3) r.w.s. 1443 dt.27.03.2024 (PB 14-27), where he disallowed 20% of the purchases of Rs. 1,06,04,69,063/- and thus made addition of Rs.21,20,93,812/- even when in the show cause notice dt. 15.03.2024, the AO proposed to make disallowance of Rs.33,42,100/- being 20% of the cash purchase of Rs. 1,67,10,500/-.
3. The assessee filed writ petition against this order in Hon’ble Allahabad High Court who vide order dt.08.05.2024 (PB 28-31) after reproducing para 17 of the petition set aside the assessment order dt.27.03.2024 with the direction that the petitioner may treat the adverse finding in the said order as points on which he may show cause and file the reply within a period of 3 weeks from the date of the order.
4. In view of the above direction of Hon’ble High Court, assessee filed the reply on 25.05.2024 (PB 32-37) where he explained in detail as to why the addition of 20% of the cash purchases of Rs. 1,67,10,500/- as proposed in the show cause notice is unjustified and uncalled for and why the addition of 20% of total purchases made by the AO in the assessment order is unjustified and uncalled for.
5. The AO, thereafter, for the first time issued notice u/s 142(1) dt.07.04.2025 which was replied on 28.04.2025. Thereafter, notice u/s 142(1) dt.01.05.2025 (PB 38-44) was issued against which adjournment was sought. Finally, AO issued show cause notice dt.09.05.2025 (PB 45-58) against which reply was filed on 13.05.2025 (PB 59-67).
6. The AO after considering the reply of the assessee, at para 3.4.1, pg 16-17 of the assessment order observed that TDS of Rs.74,56,00,934/- reflected in Form No.26AS u/s 194Q is in respect of goods sold by the assessee which confirms the genuineness of assessee’s sales. CHE TA The-existence of genuine sales in such substantial volume strongly supports the fact that corresponding purchases have actually taken place. The assessee has submitted complete details and reconciliation of purchases, payments, sales including stock register and supplier there is no basis to question the genuineness of purchases and no adverse inference is warranted u/s 69C or any other provisions on this part of purchase made by the assessee. However, the balance purchases of more than Rs.31 cr. claimed to be made from small agriculturist are mostly non-filers of return though the transactions with them are in crores. It includes cash purchase of Rs.1.67 cr., invoices of which contain only thumb impression which cannot be considered genuine. Accordingly, AO disallowed 30% of the balance purchase of Rs.31,48,68,129/- resulting into addition of Rs.9,44,60,438/-.
7. The Ld. CIT(A), NFAC after reproducing the submission of the assessee, at para 8.2 of the order held that addition made by the AO is fully justified as AO has brought on record that purchases of Rs.31.49 cr. are supported only by computer generated invoices without sale tax or GST number and in respect of cash purchases of Rs.1.67 cr., invoices merely bore thumb impression, rendering their genuineness highly doubtful. Assessee failed to substantiate the authenticity of such purchases with reliable documentary evidences. Accordingly, addition made by the AO is confirmed.
Submission:-
1. The only issue in the present appeal is whether the purchases derived by the lower authorities to the extent of Rs.31,48,68,129/- has been substantiated by the assessee with reliable documentary evidences or not and whether addition of 30% of such purchases is justified.
2. It is submitted that assessee is engaged in the business of the supply of live animals. There is no GST leviable on supply of live animals. The assessee maintains day-to-day books of accounts along with the stock record which are duly audited. The g.p. rate of the assessee for the year on turnover of Rs. 108,45,87,690/- is 2.22% as compared to g.p. rate of 1.66% on turnover of Rs.93,34,23,151/- declared in the last year.
3. The total purchases of the assessee is Rs. 106,04,69,063/-, breakup of which is as under: –
| Particulars | Amount (in Rs.) |
|---|---|
| Purchases subject to TDS and payment made by bank | 53,42,16,286 |
| Purchases not subject to TDS but payment made by bank | 50,95,42,277 |
| Purchases made in cash | 1,67,10,500 |
| Total | 106,04,69,063 |
To verify the authenticity and genuineness of the purchases, the assessee vide reply dt. 13.05.2025 (PB 5-67) furnished the copies of the bank statement to evidence that payment against purchases is through banking channel to the extent mentioned above. Confirmation of the suppliers and copy of their income tax return, wherever received were furnished. Tax is deducted at source u/s 194Q on the purchases amounting to Rs.53,42,16,286/- where the payment to individual supplier exceeded Rs.50 lacs. In respect of purchases amount to Rs.50,95,42,277/- made from different individual agriculturist/suppliers, tax was not deducted at source since the payment to the individual supplier was less than Rs.50 lacs but payment to all these suppliers are through banking channel. The remaining purchase of Rs.1,67,10,500/- made in cash is from small individual agriculturists in support of which the purchase invoices were filed. Thus, assessee has furnished authentic and reliable documentary evidences in support of its purchases and therefore, adhoc addition of purchases confirmed by Ld. CIT(A), NFAC is unjustified and unwarranted.
4. It may be noted that assessee maintains day to day stock record (PB 68-76). The total purchases of live animals during the year are 49.546 numbers and all the purchases made during the year are sold. There cannot be sale without purchase. The lower authorities have accepted the sales. Hence, no part of purchase can be disallowed unless any evidence is brought on record that the purchases are inflated/ not made. Infact, the case of the assessee was selected for the reason that substantial payment is made to the entities not registered under GST ignoring the fact that on livestock there is no GST leviable and therefore, when the assessee has substantiated its purchases with corresponding sales, the addition made by AO and confirmed by Ld. CIT(A), NFAC is uncalled for.
5. The AO himself has accepted that buyers have deducted tax at source on the sales of Rs.74,56,00,933/- made to them and therefore, the corresponding purchases are genuine. Therefore, only because on the sales made w.r.t. remaining purchases of Rs.31,48,68,129/-, no tax is deducted at source by the buyer for the reason that either their purchases do not exceed the basic limit of Rs.50 lacs or their turnover does not exceed Rs.10 cr. which is the basic threshold for deduction of tax at source u/s 194Q, such purchases cannot be held to be unverifiable more particularly when the payment is made in respect of such purchases through banking channel.
6. It is further submitted that AO has not rejected the books of accounts of the assessee. No specific purchase has been identified to be non-genuine or inflated. Hence, adhoc disallowance of 30% of the purchases of Rs.31,48,68,129/- is without basis and therefore, the addition confirmed by Ld. CIT(A), NFAC be deleted.
7. It is also submitted that in the show cause notice dt. 15.03.2024 issued during the original assessment proceeding, AO proposed addition of 20% of cash purchases of Rs.1,67,10,500/-that is Rs.33,42,100/- (PB 21-22). However, AO in completing the assessment made addition of 20% of the total purchases in order dt.27.03.2024. Hon’ble High Court has therefore set aside the original assessment order. Now in the present order, AO has disallowed 30% of the purchases of Rs.31,48,68,129/-. On what basis the disallowance is increased to 30% and on what basis purchases of Rs.31,48,68,129/- was identified for disallowance is not ascertainable. Hence, such adhoc disallowance do not stand the test of judicial scrutiny as held in the following cases: –
ACIT Vs. Ajit Ramakant Phatarpekar (2015) 119 DTR 27 (Panaji) (Trib.)
AO having not disputed the quantitative details of opening stock, sales and closing stock as given in the tax audit report and also accepted the sales, the disallowance of cash purchases made by the AO on the ground that the assessee has not proved the identity of the sellers has no justification.
ACIT Vs. Inlay Marketing Pvt. Ltd. (2015) 113 DTR 121 (Del.) (Trib.) AO having not pointed out any defect, infirmity or ambiguity in the assessee’s books of accounts and accepted the opening stock in the beginning of the year and the sales, and the sales tax authorities having made no adverse remark in the sales tax assessment order as regards the purchases shown by the assessee, there can be no reason for not accepting the amount of purchases and therefore the impugned addition u/s 69C made by the AO towards unexplained purchases cannot be sustained.
PCIT Vs. Vaman International Pvt. Ltd. ITA No.1940 of 2017 order dt.29.01.2020 (Bom.) (HC)
S. 69C Bogus Purchases: (i) The onus is on the revenue to prove that the income really belongs to the assessee (ii) The assessee has filed copies of purchase/ sale invoices, challan cum tax invoices, stock ledger showing entry/exit of materials purchased, bank statements to show payment for purchases were made through banking channels, etc., to establish genuineness of purchases (iii) The AO has not brought on record any material evidence to show that the purchases were bogus (iv) Mere reliance by the AO on information obtained from Sales Tax Department or statements of persons made before the Sales Tax Department is not sufficient to treat the purchases as bogus (v) If the AO doubts the genuineness of the purchases, he has to do further enquiries and give an opportunity to the assessee to examine/cross-examine the parties vis-a-vis the statements made by them before the Sales Tax Department. Without causing such further enquiries in respect of the purchases, it is not open to the AO to make addition u/s 69C.
In view of above, addition made by AO and confirmed by Ld. CIT(A), NFAC be deleted.”
6.1 Further, to appreciate the facts in this case the relevant extracts of the submission dated Nil filed by the assessee before the Ld. CIT A (placed at page no. 1 to 5 of the paper book) are also reproduced as under:
“Ground No:-3
That the learned AO has erred in law and on facts of the case in making the variation of Rs. 9,44,60,438 in respect of business income.
Submission of the appellant
1 The learned AO has made a variation in respect of business income amounting to Rs. 9,44,60,438 being 30% of the balance purchases amounting to Rs. 31,48,68,129.
2 The balance purchases of Rs. 31,48,68,129 has been calculated by learned AO as under
| Total Purchases | 1,06,04,69,063 |
| Less: Purchases subject to TDS | 74,56,00,934 |
| Balance Purchases | 31,48,68,129 |
According to Learned AO for balance purchases of Rs.31.48 Crores:-
(a) The invoices are only computer generated invoices, not having any sales tax number and GST number.
(b) For cash purchases of Rs. 1.67 Crores there is only thumb impression given on these invoices and therefore in his opinion the same cannot be considered genuine.
(Please refer to Para 5 and 6 on page 20 of the Assessment Order)
Your honour would appreciate that this is no reason for disallowing 30% of balance purchases without considering the facts of the case and thereafter reaching to the conclusion as to why disallowance is needed.
4. According to the records of the appellant the breakup of purchases is as under:
| Total Purchases | 1,06,04,69,063 |
| Purchases subject to TDS and payment made by bank | 53,42,16,286 |
| Purchases where payments made by bank | 50,95,42,277 |
| Purchases where cash payment is made | 1,67,10,500 |
5. Quantity wise details are as under:
| Purchases of Live Stock | 49,546 Numbers |
| Sales of Live Stock | 49,546 Numbers |
6. The trading results of the appellant are as under:
| Sales | 1,08,45,87,590 |
| Purchases | 1,06,04,69,063 |
| Gross Profit | 2,41,18,527 |
| Net Profit before partner remuneration | 9.95.217 |
| Net Profit after partner remuneration | 3,08,087 |
7.
(a) The appellant has provided all the details asked for by the Learned AO. (there is no such allegation in the Assessment Order)
(b) Books of accounts have been accepted. (the same have not been rejected)
(c) All expenses of the appellant except purchases have been accepted.
(d) Books of accounts have been duly audited under the law.
(e) Stock register of live stock has been duly maintained and submitted before the Learned AO.
(f) There is no GST on sale and purchase of live stock.
(g) It will not be out of place to mention here that all purchase invoices whether subject to TDS or without TDS are computer generated invoices and are not having any sale tax or GST number. Since there is no GST on sale and purchase of live stock, the question of mentioning GST No. does not arise.
8.
a) The Learned AO has accepted the gross profit of 2.2% as declared by the appellant on purchases to the extent of Rs.74.56 Crores being purchases subject to TDS but he has disallowed 30% of balance purchases of Rs.31.49 Crores. He has not clarified whether this 30% disallowance is with reference quantity of animals meaning thereby that whether in his opinion 30% of live stock was not at all purchased and purchases shown are fake. In this case the question arises that if 30% of live stock was not at all purchased, how the same was sold. It is impossible to sell goods without first purchasing them. Further he has not clarified whether this 30% disallowance is with reference to gross profit (goods have been shown to be purchased at a 30% higher price.) This proposition is also an impossible proposition because if the assessee is earning 2.22% profit on sales with reference to purchases on 74.56 Crores, how anyone can earn 32.22% profit (30% +2.22%) on the balance purchases of Rs.31.49 Crores. There cannot be any third proposition. The Learned AO ought to have discussed the actual proposition and his conclusion before coming to final decision of disallowing 30% of balance purchases. Hence the action of Learned AO is totally arbitrary and without any base.
9. The assessment is totally based on surmises and conjectures and the Learned AO could not reach to his conclusion before taking the decision of disallowing 30% of balance purchases.
10. In the view of the above it is humbly prayed that the variation of Rs. 9,44,60,438/- may please be deleted.”
7. On the other hand, the Ld. CIT DR supported the orders of the authorities below.
8. We have heard both the parties and perused the material available on record. The assessee is a partnership firm and during the year the assessee was engaged in supply of live animal stock (Buffalo) to the different slaughter houses and dealers after being procured from the local village markets, individual agriculturist and dairies. The AO noted that during the year under consideration, the assessee had shown substantial payments to entities which were not registered under GST and the case of the assessee was selected though CASS to verify this issue. During the year the assessee had total purchases of live stock amounting to Rs. 106,04,69,063/- and total sales was 108,45,87,590/- on which the gross profit was Rs. 2,41,18,527/-. Further, as submitted by the assessee the total purchases quantity wise was 49,546/- and total sales of live stock was also 49,546/-. The details of purchases as summarised of the assessee is reproduced as under:
| Total Purchases | 1,06,04,69,063 |
| Purchases subject to TDS and payment made by bank | 53,42,16,286 |
| Purchases where payments made by bank | 50,95,42,277 |
| Purchases where cash payment is made | 1,67,10,500 |
8.1 Regarding, the above purchases and the queries raised by the AO the assessee in its reply submitted that it had filed the necessary evidences including the confirmation from the suppliers to whom notices u/s 133(6) were sent during the earlier assessment proceedings, the details of purchases amounting to Rs. 53,42,16,286/- on which TDS u/s 194Q was deducted, alongwith a reconciliation statement with copies of bank statements. Similar details in respect of purchases amounting to Rs. 50,95,42,276.90 on which TDS u/s 194Q was not deducted due to the purchases being less than Rs 50 lacs from each or such purchases, a reconciliation statement with copies of bank statements was submitted.
8.2 However, as noted above, according to the AO the assessee did not furnish supporting details in respect of the notices issued to the assessee during the course of assessment proceedings and also noted that the assessee did not appear on the VC scheduled on 26.05.2025. Further, the AO observed that the assessee filed its reply on 12.05.2025 and 13.05.2025 which was not found to be satisfactory by the AO as according to him the assessee failed to submit any other relevant documentary evidences in support of its claim. However, we note that the AO has not specified the said documents which the assessee failed to submit in its in support of its claim.
8.3 Further, we note that the AO vide notice u/s 142(1) of the Act dated 01.05.2025 at serial no. 4 (placed at page no. 42-43 of the paper book) had inter alia asked for the following details:
“4. With respect to Purchases, for an amount of Rs. 106,04,69,063/-, made by you, kindly provide complete details as under:
e) Details of transportation:
i. Date of transportation.
ii. Name and address of the transporter.
iii. Vehicle number.
iv. Weight.
v. Amount paid.
vi. TDS deducted.”
8.4 On perusal of the replies filed by the assessee and placed in the paper book filed before us, we noticed that the assessee had not mentioned anything about the details regarding the transportation of the live stock as sought at serial no. (e) with related queries at serial no. (i)to(vi). Further, on perusal of the details before us it was noticed that the details as claimed by the assessee to have been filed before the AO and the details in respect of the transportation expenses were not filed by the assessee before us. Therefore, a clarification hearing in this case was fixed on 01.09.2026 vide order sheet noting dated 21.08.2026 which is reproduced as under:
“During dictation it emerged that certain details as submitted by the assessee before the AO vide reply dated Nil (placed at page no. 59 to 67 of the paper book) in response to the show cause notice dated 09.05.2025 (placed at page no. 45 to 58 of the paper book) have not been submitted before us in the paper book filed before us. The assessee is directed to furnish the followings documents as mentioned in para no. 1(c), 1(f) and 1(n) the said reply, which are as under:
(i) reconciliation statement with the copies of the bank statement in respect of purchases amounting to Rs. 53,42,16,286/- in which TDS under section 194Q was deducted.
(ii) reconciliation statement with the copies of the bank statement in respect of purchases amounting to Rs. 50,95,42,276.90 in which TDS under section 194Q was not deducted.
(iii) confirmation from suppliers to whom notices u/s 133(6) were sent during the earlier assessment proceeding.
(iv) The details submitted in respect of the following query alongwith the reconciliation statement in respect of cash purchases amounting to Rs. 1,67,10,500/-
| Name of the party | Amount | Date of Payment | Mode of Payment (By cheque/cash) |
2. Further, the assessee is also directed to furnish the details if any submitted during the course of assessment/ appellate proceedings to the AO’s query vide notice u/s 142(1) of the Act dated 01.05.2025 in respect of details of transportation as asked at serial no. 4(e) (i to vi) placed at page no. 42 to 43 of the paper book.
3. in view of the above, the registry is directed to fix this case for clarification hearing on 01.09.2026 after informing both the parties. Notice be issued to both parties and e-mail.”
8.5 During the course of clarification hearing on 01.09.2026 the assessee filed a reply which is reproduced as under:
M/s Ziyauddin Traders
ITA 388/Agr/2026 AY 2022-23
Response to Clarificatory Notice dated 21.08.2026
Fixed for hearing on 1.09.2026
“This is with regard to the Clarificatory Notice dated 21.08.2026, requiring the Appellant to furnish certain documents. In this regard, the Appellant wishes to furnish the following documents for your kind consideration:
At the outset, it is humbly submitted that the documents asked in the subject clarificatory notice was duly submitted by the Appellant in response to the show cause notice dated 09.05.2025. Screenshot of e-filing portal evidencing filing of the response is enclosed at PB 1-4.
Point-wise reply to the documents required to be furnished is as under:
1. Reconciliation statement with copies of banks statement in respect of purchases amounting to Rs 53,42,16,286 on which TDS under section 194Q was deducted.
Out of total purchases of Rs 106,04,69,063, purchases of Rs 53,42,16,286 were made from 31 parties on which TDS u/s 194Q of the Act was done by the Appellant (PB 5). Payment to these parties were made through banking channel only. Signed confirmation statement of all 31 parties along with bank statement and ITR copies (wherever available) of these parties is enclosed at PB 6-114.
2. Reconciliation statement with the copies of the banks statement in respect of purchases amounting to Rs 50,95,42,277 In which TDS under section 194Q was not deducted.
Out of total purchases of Rs 106,04,69,063, purchases of Rs 50,95,42,277 were made from various parties to whom payment was made through banking channel. TDS u/s 194Q of the Act was not done as the aggregate purchases from these parties was below the threshold of Rs 50 lakhs as provided in section 194Q of the Act. Complete party wise purchase list of entire purchases of Rs 106,04,69,063 along with copy of bank statement evidencing the payment made through banking channel is enclosed at PB 115-555. Further, purchase bills in respect of purchases against which payment was made through banking channel but TDS u/s 194Q of the Act was not done as payment was below the threshold limit of Rs 50 lakhs is enclosed at PB 556-805.
3. Confirmation from suppliers to whom notices under section 133(6) were sent during the earlier assessment proceedings.
Confirmation from suppliers to whom notices under section 133(6) were sent during the earlier assessment proceedings is enclosed at PB 6-114.
4. The details submitted in respect of the following query along with the reconciliation statement of wheel fofods Furchases amounting to Rs 1,67.10.550.
Complete party wise purchase list of entire purchases of Rs 106,04,69,063 which includes cash purchase of Rs 1,67,10,550 in the specified format (name of party, amount, date of payment, mode of payment) is enclosed at PB 115-276. Further, 45 bills for cash purchase of Rs 1,67,10,550 as furnished during the course of assessment proceedings is enclosed at PB 806-850.
5. Further the assessee is also directed to furnish the details if any submitted during the course of assessment/ appellate proceedings to the AO’s query vide notice under section 142(1) of the Act dated 01.05.2025 in respect of details of transportation as asked at serial no. 4(e) (i to vi) placed at page no. 42 to 43 of the paperbook.
In relation to transportation expenditure, it was submitted that the supply of animal stock was arranged by the suppliers/agriculturist from the place of procurement to the slaughter houses, however, the fuel (diesel) expenditure for their vehicle was incurred by the Appellant. The entire transportation expenditure was incurred on procurement of fuel from M/s M.S. Fuel Point, Aligarh (GSTN-09ABSPV5746K5ZG). The entire payment to M/s M.S. Fuel Point, Aligarh was made through banking channel only and due TDS are also deducted u/s 194Q of the Act. The ledger account of transportation expenditure is enclosed at PB 851-856.”
8.6 Further, the Ld. AR filed a certificate certifying the submission of the above documents before the AO as under:
| S.No. | Particulars | Page No. |
|---|---|---|
| 1. | Screenshot of E-filing portal evidencing filing of response by the Appellant | 1-4 |
| 2. | Summary of parties having pan on which TDS was done under section 194Q of the Income-tax Act, 1961 (“Act”) | 5 |
| 3. | Signed confirmation statement of all parties along with bank statement and ITR copies (wherever available) of parties having pan on which TDS was done under section 194Q of the Act. | 6-114 |
| 4. | Complete party wise purchase list of entire purchases in the specified format (name of party, amount, date of payment, mode of payment) | 115-276 |
| 5. | Copy of bank statements of Appellant highlighting and evidencing payment made | 277-555 |
| 6. | Purchase bills in respect of purchases against which payment was made through banking channel but TDS under section 194Q of the Act was not done as payment was below the threshold limit of Rs 50 lakhs | 556-805 |
| 7. | Purchases bills for purchases made in cash | 806-850 |
| 8. | Ledger account of transportation expenditure | 851-856 |
It is certified that the documents at S. No. 2 to 7 were filed before the Ld. AO vide submission dated 12 may 2025 and at S. No. 8 was filed before the Ld. AO vide submission dated 26 December 2023
-sd/-
Yogesh Parwal
Authorized Representative
8.7 As noted above, the AO stated that the assessee did not file the relevant documentary evidence in support of the claims made by the assessee but the AO did not specify any such document which was not filed. (as highlighted by us in the relevant extracts of the order of the AO reproduced in para no.3.8 on page no. 15 of this order). On the other hand, during the course of above clarification hearing the assessee filed the necessary details (placed at page no. 5 to 856) along with the screenshot of E-filing portal evidencing filing of response by the Appellant (placed at page no. 1 to 4 of the paper book) along with a certificate that the above documents were filed by the assessee before the AO as requisitioned by the AO as per the various notices u/s 142 (1) of the Act issued by the AO from time to time. Further, we notice that despite such documents filed by the assessee during the course of assessment proceedings before the AO, no enquiry (except for the enquiry u/s 133(6) of the Act was conducted by the AO for which the assessee had filed the signed confirmation statement of all parties along with bank statement and ITR copies (wherever available) of parties having PAN on which TDS was done under section 194Q of the Act placed at page no. 6-114 of the paper book) was conducted by the AO nor any defect/shortcoming (except the fact that in there were only thumb impression of the sellers in respect of the cash purchases bills/vouchers) was pointed out in the documents filed by the assessee.
8.8 Further, the AO noted that on perusal of the invoices submitted by the assessee in respect of purchases that the same were only computer-generated invoices, not having any Sales Tax No. and GST No. on those invoices and the transaction of each invoice in lakhs with each supplier without GST no. was not acceptable. In reply the assessee submitted that the assessee dealt in trading of live animals and procured in local village markets colloquially could “painth” and the live animals were not subjected to levy of GST since GST was not leviable on the live animals (HSN0102) as exempted under serial no. 2 of notification no. 02/2017-CTR dated 28.06.2017 and therefore, the suppliers of the live animals are not required by law to be registered under CGST/SGST Act. In this regard, notification no. 02/2017-CTR dated 28.06.2017 is reproduced as under:
NOTIFICATION NO. 2/2017-CENTRAL TAX (RATE), DATED 28-6-2017
[As Amended by Corrigendum Gsr 868(E), dated 12-7-2017, Corrigendum Gsr 959(E), dated 27-7-2017, Notification No. 28/2017-Central Tax (Rate), dated 22-9-2017, Notification No. 35/2017-Central Tax (Rate), dated 13-10-2017, Notification No. 42/2017-Central Tax (Rate), dated 14-11-2017, Notification No. 7/2018-Central Tax (Rate), dated 25-1-2018, Notification No. 19/2018-Central Tax (Rate), dated 26-7-2018, Notification No. 25/2018-Central Tax (Rate), dated 31-12-2018, Notification No. 15/2019-Central Tax (Rate), dated 30-9-2019, Notification No. 9/2021-Central Tax (Rate), dated 30-9-2021, Notification No. 19/2021-Central Tax (Rate), dated 28-12-2021, Notification No. 7/2022-Central Tax (Rate), dated 13-7-2022, Notification No. 13/2022-Central Tax (Rate), dated 30-12-2022, Notification No. 4/2023-Central Tax (Rate), dated 28-2-2023, Notification No. 18/2023-Central Tax (Rate), dated 19-10-2023 and Notification No. 3/2024-Central Tax (Rate), dated 12-7-2024]
In exercise of the powers conferred by sub-section (1) of section 11 of the Central Goods and Services Tax Act, 2017 (12 of 2017), the Central Government, being satisfied that it is necessary in the public interest so to do, on the recommendations of the Council, hereby exempts intra-State supplies of goods, the description of which is specified in column (3) of the Schedule appended to this notification, falling under the tariff item, sub-heading, heading or Chapter, as the case may be, as specified in the corresponding entry in column (2) of the said Schedule, from the whole of the central tax leviable thereon under section 9 of the Central Goods and Services Tax Act, 2017 (12 of 2017).
SCHEDULE
| S. No. | Chapter/Heading/Sub-heading/Tariff item | Description of Goods |
|---|---|---|
| (1) | (2) | (3) |
| 1. | 0101 | Live asses, mules and hinnies |
| 2. | 0102 | Live bovine animals |
| 3. | 0103 | Live swine |
| 4. | 0104 | Live sheep and goats |
| 5. | 0105 | Live poultry, that is to say, fowls of the species Gallus domesticus, ducks, geese, turkeys and guinea fowls. |
| 6. | 0106 | Other live animal such as Mammals, Birds, Insects |
| 7. | 0201 | Meat of bovine animals, fresh and chilled. |
| 1[8. | 0203, 0204, 0205, 0206, 0207, 0208, 0209 | All goods, fresh or chilled |
| 9. | 0202, 0203, 0204, 0205, 0206, 0207, 0208, 0209, 0210 | All goods [other than fresh or chilled] and 2[, other than pre-packaged and labelled]] |
| 10. to 17. | 3[***] | |
| 18. | 3 | Fish seeds, prawn/shrimp seeds whether or not processed, cured or in frozen state [other than goods falling under Chapter 3 and attracting 2.5%] |
| 19. | 0301 | Live fish. |
| 20. | 0302 | Fish, fresh or chilled, excluding fish fillets and other fish meat of heading 0304 |
| 4[21. | 0304, 0306, 0307, 0308 | All goods, fresh or chilled |
| 22. | 5[0303, 0304, 0305, 0306, 0307, 0308, 0309] | All goods [other than fresh or chilled] and 6[, other than pre-packaged and labelled]] |
1 Substituted by Notification No. 42/2017-Central Tax (Rate), dated 14-11-2017, w.e.f. 15-11-2017, before it was read as:
| 8. | 0202 | Meat of bovine animals frozen [other than frozen and put up in unit container] |
| 9. | 0203 | Meat of swine, fresh, chilled or frozen [other than frozen and put up in unit container] |
8.9 Thus, on perusal of the above notification, we note that ‘Live bovine animals’ in which the assessee has dealt its business during the year is exempt from GST and therefore in this regard, the contention of the assessee that the live animals are not required by law to be registered under CGST/SGST Act is acceptable. Further, we are also satisfied that purchase invoices were only computer-generated invoices does not make the purchases as bogus purchases unless adverse findings regarding its non-genuineness are brought on record by the AO which has not been done by the AO in this case as discussed above. Similarly, for the same reasons the thumb impressions on the cash vouchers will by itself not make the purchases bogus and in the present case, the cash purchases amount only to Rs. 1,67,10,550/- out of total purchases of Rs. 106,04,69,063/- which constitutes only 1.57% of the total purchases.
8.10 Thus, considering the above facts and the details submitted by the assessee before the AO during the assessment proceedings and as per our observations regarding the non-acceptance about the defects pointed by the AO and further the fact that out of the total purchases of Rs. 106,04,69,063/-, purchases subjected to TDS and payments through bank amounted to Rs. 53,42,16,286/-, purchases where payments were made through bank amounted to 50,95,42,277/- and the cash payment purchases amounted to Rs. 1,67,10,500/- which is only 1.57% of the total purchases for which 45 bills for cash purchase (placed at page no. 806 – 850 of the paper book) was filed by the assessee and further, the details of transportation expenses amounting to Rs. 1,77,41,507/- which was purchased from M/s Fuel Point, Aligarh where the entire payment was made through banking channel on which due TDS was deducted u/s 194Q of the Act (ledger account of transportation expenditure placed at PB 851-856 of the paper book), the ad hoc disallowance being 30% of the purchases (Rs.31,48,68,129/-) which came to Rs. 9,44,60,438/- and considered as business income is not justified and the same is deleted. Ground no. 1 of the appeal is allowed.
9. In the result, the appeal of the assessee is allowed.
Order pronounced in the Open Court on- 18.09.2026





